Unit Economics Analytics: Contribution Profit from Billing and Usage (2026)
By William Zhu & the InfiniSynapse Data Team · Published: 2026-08-22 · Last updated: 2026-08-31 · Last verified: 2026-08-31 · Next review: 2026-11-30 · About · Privacy policy · Terms · Editorial standards · Corrections
Title: Unit economics from billing, usage, and contribution profit
Meta Description: Unit economics joins billing and usage so you can lock contribution profit and written payback assumptions without standing up a finance warehouse first.
Slug: unit-economics-analytics
 ## Table of Contents
- TL;DR
- What Unit Economics Means in 2026
- A Billing-Plus-Usage Framework
- How Teams Compare Contribution Methods
- Tool Landscape for Billing and Usage
- Implementation Steps You Can Audit
- Accuracy and Experience Record: Illustrative Contribution Pack
- Evidence Boundaries and Independent Validation
- How to Cite This Page
- Selection Scorecard for Contribution Packs
- Failure Modes That Break Payback Math
- Frequently Asked Questions
- Conclusion
TL;DR
We review contribution packs at the InfiniSynapse desk on sanitized billing composites; sample figures on this page are illustrative, not customer payback.
Direct answer: Unit economics is the join of billing facts, usage, and a written cost stack so contribution profit and payback stay reconcilable on sources you already have—without copying every invoice into a new finance warehouse first.
What you'll learn: a unit-first definition; a billing-plus-usage framework; invoice grain versus subscription grain; a four-step implementation path; an illustrative contribution desk; a scorecard; and the failure modes that break payback.
Download evidence: desk log · unit CSV · verification script · source check · reproduction protocol. First-party illustrative evidence only; not audited finance or customer evidence.
Unit economics fails when MRR is a dashboard number, usage lives in another store, and “active customer” means three things. The fix is a locked unit, a signed cost sentence, and a question you can replay. It is not a prettier retention chart.
What Unit Economics Means in 2026
Key Definition: Unit economics is the audit of contribution profit per chosen unit—account, subscription, or order—by joining authorized billing, usage, and cost inputs so payback assumptions stay written and inspectable. The unit of work is a board pack with grain, not a vanity MRR tile.
Independent published context (separate from this page’s desk composite): Wikipedia: Data warehouse · ISO/IEC 27001 (retrieved 2026-09-04) · Gartner Peer Insights — Analytics and BI Platforms (retrieved 2026-09-04) · Google BigQuery documentation (retrieved 2026-09-04). Those sources set the industry bar for definitions, risk, and architecture; they did not run the numbers in the desk table below, and they are not a product award.
Unit profit is a contribution question, as defined in the Wikipedia contribution margin overview (retrieved 2026-09-04). Payback math should cite Wikipedia customer acquisition cost overview (retrieved 2026-09-04).
If billing already lives in a warehouse copilot, compare it to Snowflake Cortex Analyst documentation (retrieved 2026-09-04). Usage events often sit behind Supabase documentation (retrieved 2026-09-04).
Finance already has invoices. Product already has usage. What they lack is a shared unit. Unit economics starts when someone writes “paying account, excluding trials and internal seats” and the next run uses the same words.
If the missing object is durable context rather than a one-off pack, continue in FP&A analytics. If the next failure is a join across modes or engines, use ecommerce analytics.
Metering caches should follow TTL rules in Redis documentation.
Treat unit economics as a join with a cost stack attached. If “contribution” sometimes includes payment fees and sometimes does not, the board pack will argue with the close. Bind the stack in a short knowledge-base note before you ask for payback.
Contribution profit versus vanity MRR
MRR can rise while contribution falls. Unit economics that ranks plans on booked revenue alone will scale the wrong SKU. Contribution is a sentence: recognized revenue minus variable costs you are willing to defend (hosting, payment fees, support load, usage COGS). If a cost is allocated overhead, say so. Silent allocations invent profit.
A semantic layer is one way to freeze those names. A Markdown note bound to the billing source is enough for the first pack. Unit economics does not require a pre-built metric warehouse.
Why the unit definition must live in a knowledge base
“Active” is the most expensive adjective in unit economics. Is it a paid invoice this month, a login, or a usage threshold? Write it. Bind it. If two analysts disagree, stop. Unit economics that lets the model infer “active” from whatever column is densest will drift every close.
Trials, annual prepay, and refunds need their own rules. Unit economics that mixes trial seats into the paying denominator will look cheaper than cash.
A Billing-Plus-Usage Framework
Use one table as the contract. Unit economics questions should name the unit, the window, and the cost stack.
| Layer | What you lock | Typical source | Failure if skipped |
|---|---|---|---|
| Unit | account, subscription, or order | Billing export | Mixed grains |
| Money | invoices, credits, refunds | Stripe or ledger extract | MRR without cash |
| Usage | metered events in the same window | Product store or file | Revenue without load |
| Cost | variable stack, dated | Finance note + bills | Contribution fiction |
| Eligibility | paying vs trial vs internal | Knowledge-base sentence | Cheap-looking CAC |
| Payback | CAC definition and months | Same note | A ratio without a clock |
Unit economics does not need a new data warehouse to start. A warehouse helps when many consumers need the same materialized grain on a schedule. The first honest pack can join a billing export to a usage extract in place.
When operators need a recurring view, generate a dashboard from the same query that produced the table. A board that recomputes “contribution” from a new column each month is not a pack.
How Teams Compare Contribution Methods
Teams argue tools. They should argue grain. Unit economics methods differ in the clock they use.
| Method | Works when | Breaks when |
|---|---|---|
| Invoice grain | Cash and refunds are the question | Usage is monthly and invoices are annual |
| Subscription grain | Plan changes are the question | Add-ons bill on a different cycle |
| Order grain | Transaction businesses | Seats and usage do not map to orders |
| Cohort payback | CAC is dated and complete | Marketing spend is a single blob |
Invoice grain versus subscription grain
Invoice-level unit economics is honest about refunds and credits. Subscription-level unit economics is honest about plan mix. Do not average them without a map. If an annual invoice covers twelve months of usage, spread or label it. Silent cash-in-month “profit” is how boards get surprised in month two.
AI for data analysis can draft the join. A human still owns the spread rule. Unit economics that hides the rule will not survive the next close.
Payback assumptions you must write down
Payback is not a discovered number. It is contribution over a CAC definition you wrote. Unit economics should print both. If CAC excludes a channel, say so. If contribution is month-one only, do not annualize it in the headline.
Illustrative desk rule: if CAC is missing for more than a small share of new units (you set the threshold), do not publish a company-wide payback. Report the covered cohort only.
Tool Landscape for Billing and Usage
Buyer shortlists for this category often pass through Gartner Peer Insights for Analytics and BI. That view helps procurement. It does not choose your unit. Unit economics is per-customer contribution; a project-level cost benefit analysis example is the other clock when you are funding a workflow change, not a plan cohort.
If billing facts already live in BigQuery, keep them there. The Google BigQuery documentation is the reference for query jobs, not a reason to clone invoices into a second warehouse. Unit economics on a warehouse-resident billing table is still “no new warehouse” if you refuse the extra copy.
Snowflake shops can ask in place. Snowflake Cortex Analyst is one path those teams already evaluate. A data agent is a fit when the question is a goal (“contribution by plan after refunds”) and you need the SQL trail. It is a poor fit when someone wants the tool to issue credits.
Warehouse-resident billing facts
Read-only roles only. Unit economics should never write to the billing provider. If you connect Postgres, Stripe exports, or a warehouse table, record the role and the window. Natural language to SQL is an execution path, not a replacement for the unit sentence.
File-first packs for early-stage teams
Five-person companies often have a Stripe CSV and a usage dump. Unit economics can start there. Freeze the file dates. Bind “paying account.” Ask contribution and a payback under stated CAC. Do not paste live API keys into a prompt.
ISO/IEC 27001 is not a finance method, but the ISO/IEC 27001 overview is a reasonable bar for how billing extracts are stored. Those files contain enough to impersonate customers if you leave tokens in the sheet. Strip them.
Implementation Steps You Can Audit
Start with the unit sentence. Unit economics that starts from “what is our magic number” will invent a denominator.
Join billing and usage on a stable key
Pick account_id or subscription_id and prove it exists on both sides. Unit economics with a fuzzy email join will double-count. List unmatched usage and unmatched invoices. If match rate is weak, do not publish contribution.
Window both sides the same way. Usage in July against an annual invoice in January needs a written spread.
Lock the unit and the cost stack
Write paying versus trial versus internal. Write the variable costs in order. Unit economics without that list will subtract whatever is convenient. Get a finance partner to initial the note. This is not a product metric warehouse. It is a signed paragraph.
Ask contribution profit, then inspect SQL
Ask one goal: contribution by plan after refunds, or payback for the last complete cohort under the written CAC. Unit economics quality is the inspectable join. Open the query. Check that credits did not land on a different customer key.
If an agent drafted SQL, read it. If you wrote it, attach it. A pack without a query is a slide.
Replay the board pack next month
Download Markdown or PDF from the task workspace. A chat-only result will be re-litigated at the next board. Reuse the same unit and the same cost stack. If contribution moved, the memo should say whether volume, refunds, or usage unit cost moved.
Accuracy and Experience Record: Illustrative Contribution Pack
The following numbers are an illustrative desk composite, not a customer result, audited financial statement, or benchmark. Run ID: UE-COVERAGE-20260823. Operator: InfiniSynapse Data Team. Six outputs and three held items were inspected.
| Item | Desk composite (illustrative) |
|---|---|
| Window | Calendar July 2026, invoice-dated |
| Units | 1,840 paying accounts; trials excluded |
| Contribution | $38 per paying account (illustrative stack) |
| CAC | $52 on 210 new paying accounts with complete spend |
| Payback | 13.7 months under those assumptions |
| Unmatched | 4% of usage events with no billing key |
| Action | Do not publish company-wide payback; fix the 4% map |
Unit economics on this pack is useful because unmatched usage is visible. A rank that hid the orphans would have looked cleaner and been wrong.
A second month should reuse “paying account” and the same fee list. That is how the pack becomes a board habit instead of a one-off model.
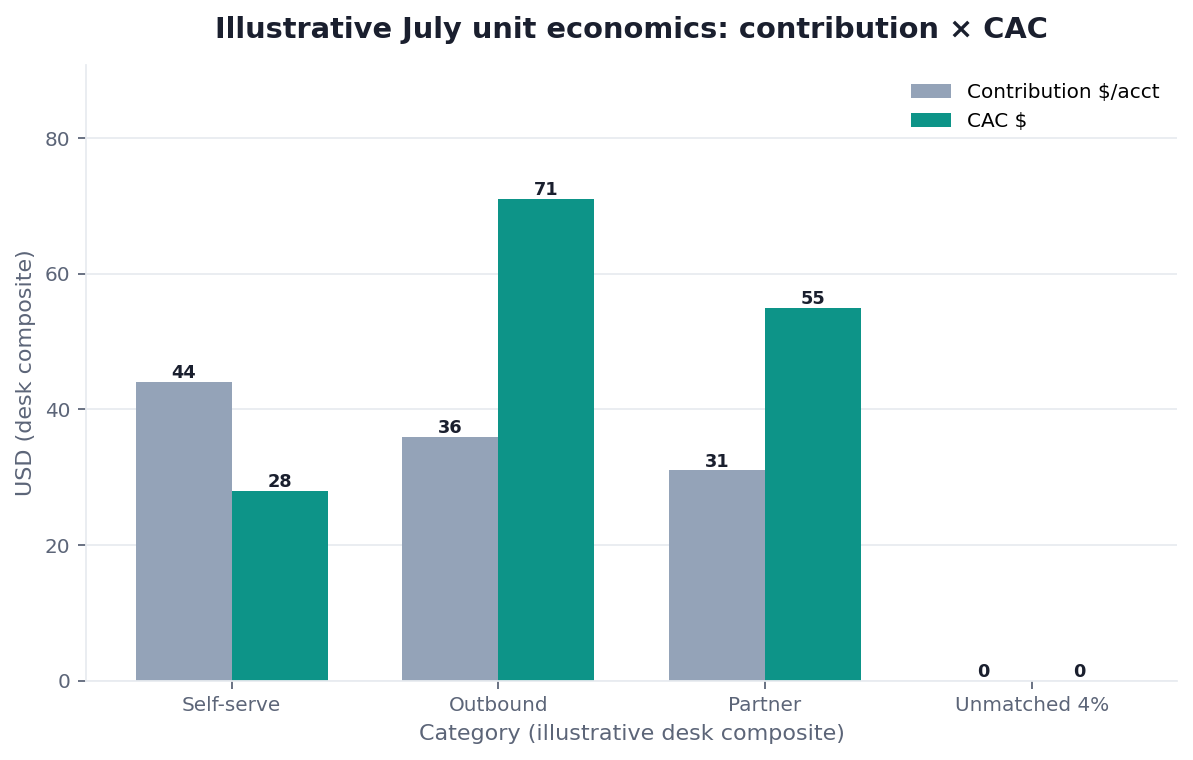
Figure. Illustrative desk composite (category × method). Not a customer experiment, SLA, or official benchmark.
| Evidence class | What you can cite | What you cannot claim |
|---|---|---|
| Desk composite on this page | Grain, collision, inspectable artifacts | Customer uplift %, vendor bake-off win |
| Published authority (linked above) | Frameworks and definitions from the cited sources | That those sources ran this desk sample |
Desk composite: $38 contribution, $52 CAC, 13.7-month payback, 4% unmatched usage. Published context: Wikipedia contribution margin / CAC, Snowflake Cortex Analyst, Supabase docs, Redis docs.
The operator held the cost stack, reproduction query, and company-wide payback. The desk log records limitations; the CSV exposes six outputs and three held items.
Evidence Boundaries and Independent Validation
Billing and usage rows, recognition basis, invoices supporting variable costs, acquisition-spend denominator, SQL, reconciliations, currency handling, finance approval, and customer outcomes are unavailable. The arithmetic is illustrative and cannot establish actual contribution or payback.
The source check limits each authority to definitions, security, procurement, or product documentation. The open protocol defines external testing. No qualifying independent report, audited customer case, or media investigation exists as of 2026-08-31.
The checker validates displayed values only; it does not prove unit definition, cost allocation, CAC completeness, accounting treatment, statistical representativeness, or product performance.
Unit economics evidence needs source rows. Unit economics evidence needs signed cost stacks. Unit economics evidence needs reconciliations. Unit economics evidence needs coverage denominators. Unit economics evidence needs independent replication. Every documented review should preserve billing and usage rows, publish the join query, reconcile revenue and refunds, identify every variable cost, disclose CAC coverage, test allocation sensitivity, record currency and period rules, obtain finance approval, and leave pricing, accounting, and investment decisions with accountable human owners.
How to Cite This Page
Zhu, W., & InfiniSynapse Data Team. (2026). Unit economics analytics: 2026 field guide. InfiniSynapse. https://infinisynapse.com/en/blog/unit-economics-analytics
Run: InfiniSynapse Data Team. (2026). Desk log UE-COVERAGE-20260823. https://infinisynapse.com/blog-media/unit-economics-analytics/downloads/desk-log-UE-COVERAGE-20260823.md
Neither is an independent audit, customer case, tax opinion, benchmark, or proof of payback.
Selection Scorecard for Contribution Packs
Score from 1 to 5. Unit economics that cannot inspect SQL should not win on a prettier SaaS chart.
| Criterion | What “5” looks like | Disqualifier |
|---|---|---|
| Unit control | Paying / trial / internal written | Mixed seats in one average |
| Join honesty | Unmatched rates printed | Silent inner joins |
| Cost stack | Variable vs allocated labeled | “All-in” with no list |
| Payback | CAC definition + covered share | One magic number |
| Audit | Pack + SQL downloadable | Chat-only MRR |
| Write path | Read-only billing | Agent can issue credits |
Unit economics scores well when a skeptical CFO can replay the join. It scores poorly when the stack implies a pre-built finance warehouse you do not operate.
Failure Modes That Break Payback Math
Name the break on the pack. Unit economics reviews go faster when the known distortions are written down.
Mixing trials into paying units
Trials and internal seats dilute the denominator and make contribution look cheap. Exclude them or report them on a second row. If a trial converts mid-window, write the rule once.
Usage without a matching invoice window
Metered cost in a month that does not match recognized revenue will swing contribution. Either spread the invoice or label the pack as cash-basis. Do not annualize a single month of usage against a prepaid year without saying so.
Cost allocations that nobody signed
Shared support or shared cloud spend dumped equally on every account will punish small plans. Mark allocated lines as allocated. If nobody will sign the allocation, leave it out of contribution and show it below.
A fourth pattern is refunds booked as revenue with a delay. Ignoring credit notes will overstate month-one payback. Join credits on the same customer key and window.
Before you open a workspace, check four things on your own sources: the unit sentence, the billing-to-usage key, the cost stack, and whether CAC coverage is complete enough to publish. If those four are not written, a tool will still produce a confident ratio.
Cluster guides under this hub: SaaS Metrics Analytics: NRR and the Billing File; Contribution Margin Analysis from Cost and Price; Billing Data Analysis from a Ledger Export; Usage plus Revenue Join; Payback Period Analysis: Put Assumptions in the Pack; Unit Economics for Startups; Annual Recurring Revenue from the Billing File; Customer Acquisition Cost Joined to Payback; What Is Unit Economics on Billing plus Usage; SaaS unit economics; Unit Economics Model You Can Rerun.
Related hops: FP&A analytics; ecommerce analytics; AI data report generator; A/B test analysis; semantic layer.
Join billing and usage, then lock the unit definition
Connect a read-only billing source or upload sanitized invoice and usage extracts, bind the paying-unit note, and ask contribution after refunds. This check uses only sources you authorize.
Commercial association: You do not need the workspace to complete the educational diagnosis on this page.
Open InfiniSynapseHow this page is sourced. William Zhu is cofounder of InfiniSynapse (GitHub @allwefantasy); no personal LinkedIn, accounting credential, customer affiliation, or independent reviewer role is claimed. Run record. Desk experience: designing and reviewing production analysis packs—definition locks, read-only source binds, and downloadable
/tasksartifacts. Reviewed by analytics engineering · data platform · LLM security · editor. Editorial standards · corrections · publishing principles · Contact zhuhl@infinisynapse.com. Company About. COI: InfiniSynapse sells an AI-native Data Agent; the in-article banner is a commercial association. Wikipedia, ISO, Gartner, Google, Snowflake, Supabase, and Redis did not validate this run. Fact-check: Wikipedia · ISO · Gartner Peer Insights · Google Cloud · Snowflake documentation. This page can affect money or identifiable people; it is a method note, not tax, employment, or legal advice.
Frequently Asked Questions
Do I need a finance warehouse before the practice is real?
Bottom line: No. Unit economics is real when a locked unit, a billing-to-usage key, and a signed cost sentence can be joined and replayed. A warehouse helps when many consumers need the same grain on a schedule. It is optional for the first board pack on dated exports or a read-only billing store.
What unit should you use?
Bottom line: Pick the unit a decision maker can act on—usually paying account or subscription—and write exclusions. Mixed grains (seats plus orders plus sessions) will not survive a close. If you need two units, publish two packs. Do not average them into one “magic number.”
How should CAC and payback be treated?
Bottom line: Print the CAC definition, the covered share of new units, and the contribution window. Do not headline payback when CAC is missing for a large share of joiners. Use an illustrative threshold you are willing to defend. Never treat a model-drafted ratio as a board fact without the query.
Can this replace the billing system or ERP?
Bottom line: No. Unit economics explains contribution on authorized reads. It does not issue invoices, write credits, or replace the close. Keep the path read-only. If a teammate wants automated dunning, that is a different control path.
Can readers reproduce the displayed payback?
Bottom line: No. Source rows, signed cost stack, CAC denominator, SQL, and reconciliation are unavailable. The CSV is aggregate evidence only.
Has an independent finance analyst reproduced this run?
Bottom line: No qualifying external report is published as of 2026-08-31. See the open protocol for requirements.
Conclusion
Unit economics is a join you can defend: billing, usage, and a cost stack on a unit someone signed. Lock paying versus trial, print unmatched rates, and refuse payback when CAC coverage is thin. The board pack is the product. The MRR tile is not. When the unit sentence and the two extracts are ready, ask contribution on an authorized source at https://app.infinisynapse.com/.