What Is Unit Economics? Audit Billing and Usage
By William Zhu & the InfiniSynapse Data Team · Published: 2026-08-22 · Last updated: 2026-08-31 · Last verified: 2026-08-31 · Next review: 2026-11-30 · Editorial standards · Corrections
Table of Contents
- TL;DR
- Evidence Boundary
- Define the Unit Before the Formula
- Separate Billing, Cash, and Revenue
- Build a Bounded Billing-and-Usage Audit
- Practical Replay and Experience Evidence
- Synthetic Aggregate Evidence
- Illustrative Per-Covered-Unit Scenario
- Independent Validation
- Failure Modes and Bounded Controls
- Sources and Limited Claims
- Frequently Asked Questions
- How to Cite
- Conclusion
TL;DR
Direct answer: What is unit economics? It is a way to compare an amount attributable to a defined unit with selected costs attributable to that same unit and period. A useful answer states the grain, evidence, coverage, timing, allocation choices, exclusions, and unresolved gaps before presenting arithmetic.
What you'll learn: how to distinguish invoices from cash and recognized revenue, reconcile a billing-to-usage join, interpret two separate synthetic evidence classes, reproduce every published number, and hold payback when customer acquisition cost (CAC) is absent.
Teams asking what is unit economics expect one ratio. Use an evidence contract. Define the unit, reporting window, billing events, service period, usage key, selected variable costs, and eligibility rules. Report supported and unsupported claims. For a subscription contract, the per-customer version is SaaS unit economics per customer.
The downloadable pack contains an assumption register, synthetic aggregate desk sample, standard-library verifier, external-source check, and independent reproduction protocol. These are publication artifacts, not company, processor, or audit records.
Evidence Boundary
Key Definition: What is unit economics in this guide? It is bounded arithmetic at a declared unit and period: a billing-derived amount after stated credits, less selected variable costs, with coverage and missing inputs shown separately. It is not automatically revenue, cash, profit, lifetime value, or payback.
This page keeps two synthetic evidence classes separate:
- Class A—aggregate coverage: 410 invoice-eligible accounts, 388 covered, and 22 unmatched; 94.6% and 5.4%. These are account counts, not dollar coverage.
- Class B—one illustrative scenario: $448 after stated credits, $190 selected variable costs, and a $258 arithmetic difference. It is not linked to the 388 accounts.
The answer to what is unit economics changes with the unit. This guide uses invoice-eligible accounts for coverage and one abstract covered unit for scenario arithmetic. No customer rows or distributions are provided.
The $258 is not cash, recognized revenue, profit, a benchmark, or a customer result. CAC is absent, so payback is held. Do not multiply $258 by 388.
Claims this evidence can support.
The artifacts support 388 + 22 = 410, rates of 94.6% and 5.4%, $12 + $138 + $40 = $190, and $448 − $190 = $258.
They support the limited claim that what is unit economics is more reviewable when coverage and scenario arithmetic stay separate. They do not establish business performance.
Claims this evidence cannot support.
They cannot support company margin, a typical result, dollar coverage, payback, lifetime value, a close, or financial-statement recognition. They do not evidence a Stripe connection, external audit, or customer review.
Define What Is Unit Economics Before the Formula
What is unit economics without a stable grain? It is arithmetic whose denominator can change between reviews. Write: “invoice-eligible account in the selected service window, excluding trials and internal accounts, linked to the required usage/cost key by an approved identifier.” Use your policy.
Account-level what is unit economics is not interchangeable with seat-level analysis. A seat denominator may be useful for pricing, while account grain may be useful for a logo-level view. Publish separate outputs when needed.
If the broader question is retention or expansion, use SaaS metrics analytics. For cost-stack design, see contribution margin analysis. The parent framework is unit economics analytics.
Treat dates as evidence
Store extract date, reporting window, service period, timezone, and currency. As an analogy for disciplined vintages—not as financial authority—CBO publishes dated baselines, while IMF Data identifies releases and datasets. A replay should use the same definitions or disclose changes.
Separate Billing, Cash, and Revenue When Answering What Is Unit Economics
An invoice records amounts billed under configured terms. A credit note can reduce an invoice or affect a customer balance. A refund moves value through a payment path. Cash reflects settlement; recognized revenue follows a recognition method and service timing. What is unit economics must not collapse these concepts.
Stripe's Invoicing overview explains invoice lifecycle concepts (retrieved 2026-09-04). Stripe's subscriptions and invoicing revenue-recognition methodology discusses recognition behavior (retrieved 2026-09-04), and its credit-note examples show why credits require state-aware treatment (retrieved 2026-09-04). These sources describe Stripe concepts; they do not validate this synthetic sample.
The IFRS 15 overview addresses revenue from contracts with customers (retrieved 2026-09-04). This guide does not apply IFRS 15 or classify the $448 scenario amount as recognized revenue.
Use precise amount labels
For what is unit economics here, “billing-derived amount after stated credits” is deliberately narrow. It does not say whether an invoice was paid, whether cash settled in the period, whether a refund occurred later, or when a performance obligation was satisfied. Real work should reconcile invoice status, credit notes, refunds, customer balances, payments, currency conversion, taxes, and service periods under the applicable accounting policy.
A semantic layer can help preserve labels, but governance still belongs to the data owner. If billing exports are the evidence, billing data analysis provides the next diagnostic.
Build a Bounded What Is Unit Economics Audit
Questions about what is unit economics become testable when each transformation has a check. A practical sequence is:
1. Register assumptions.
Write the unit, population, window, currency, amount label, cost scope, join key, rounding, exclusions, and held metrics. The downloadable register includes each of these fields and marks the sample synthetic.
2. Reconcile eligibility and coverage.
Count invoice-eligible units before joining. Left join to the required usage/cost key. Report covered and unmatched counts before calculating any per-unit scenario. An inner join alone hides the 22 unmatched accounts.
Coverage in this page means account coverage only. What is unit economics by dollar coverage would require billing amounts for every account and a stated denominator; those data are intentionally absent.
3. Normalize timing and identifiers.
Choose invoice date or service period deliberately. Do not join July usage to a full annual invoice merely because both exist in July. Resolve account merges, credit timing, and late usage under written rules.
Identifiers should be stable and access-controlled. As process analogies only, CDC NCHS demonstrates careful treatment of data definitions, HL7 implementation standards emphasize explicit structured fields, and ClinicalTrials.gov illustrates prospective protocol registration. None is a financial authority or validator of this page.
4. Select and allocate costs.
Document why each cost changes with the unit or usage. Shared capacity may need an allocation key, and variable support needs a stated driver. Do not add overhead without a disclosed rationale.
The FinOps Open Cost and Usage Specification discussion of split cost allocation handling provides useful cost-allocation vocabulary (retrieved 2026-09-04). It does not prescribe accounting treatment or endorse this scenario.
5. Calculate only supported outputs.
What is unit economics with no CAC input? It can show the bounded arithmetic difference, but it cannot show CAC payback. Mark payback “held—CAC absent.” Apply the same rule to lifetime value when retention or lifetime assumptions are missing.
Practical Replay of What Is Unit Economics Evidence
The practical experience is a transparent artifact replay. Run the verifier, inspect each assertion, and compare the output with the article, chart, and schema. No private access, billing account, or product is required.
A data agent or chat-with-data interface may assist exploration, but neither establishes correctness. Use exploratory data analysis to inspect keys and data governance to assign definition ownership.
python3 verify-WIUE-20260831.py
The standard-library verifier checks evidence classes, counts, rates, costs, absent CAC, and held payback. Passing means internal consistency, not suitability for an entity.
Replay observations
The replay reveals two limits: 94.6% account coverage says nothing about dollars, and correct subtraction says nothing about representativeness.
This practical replay answers what is unit economics as a review procedure: reproduce the stated arithmetic, verify the boundary, and stop when an input is absent. It makes no production-pack, run-hash, reviewer-credential, or finance-approval claim.
Synthetic Aggregate Evidence for What Is Unit Economics
Class A contains one aggregate row only. There are no customer rows or hidden distribution statistics.
| Coverage measure | Synthetic count | Rate | Interpretation |
|---|---|---|---|
| Invoice-eligible accounts | 410 | 100.0% | count denominator |
| Required usage/cost key present | 388 | 94.6% | covered accounts |
| Billing-only unmatched | 22 | 5.4% | requires investigation |
What is unit economics for the covered population remains unanswered by Class A because it contains no per-account billing or cost values. The 94.6% figure is account coverage, not dollar coverage. A small number of unmatched accounts could represent a large share of billed amounts, or the reverse.
Do not describe 388 as a sample size for the $258 scenario. The scenario is a separate teaching example. Do not publish a company-wide result from these counts.
Illustrative What Is Unit Economics Scenario
Class B is one invented arithmetic scenario for one abstract covered unit. It is not an observation, customer, mean, median, percentile, benchmark, or distribution.
| Scenario component | USD | Scope |
|---|---|---|
| Billing-derived amount after stated credits | $448 | not cash or recognized revenue |
| Payment fee | −$12 | selected variable cost |
| Metered hosting | −$138 | selected variable cost |
| Selected variable support | −$40 | narrow stated allocation |
| Selected variable costs | −$190 | $12 + $138 + $40 |
| Arithmetic difference | $258 | $448 − $190 |
What is unit economics in this scenario? Only the bounded difference shown above. Taxes, refunds outside the stated credit treatment, customer-balance movements, unselected costs, overhead, acquisition costs, and accounting recognition are outside scope.
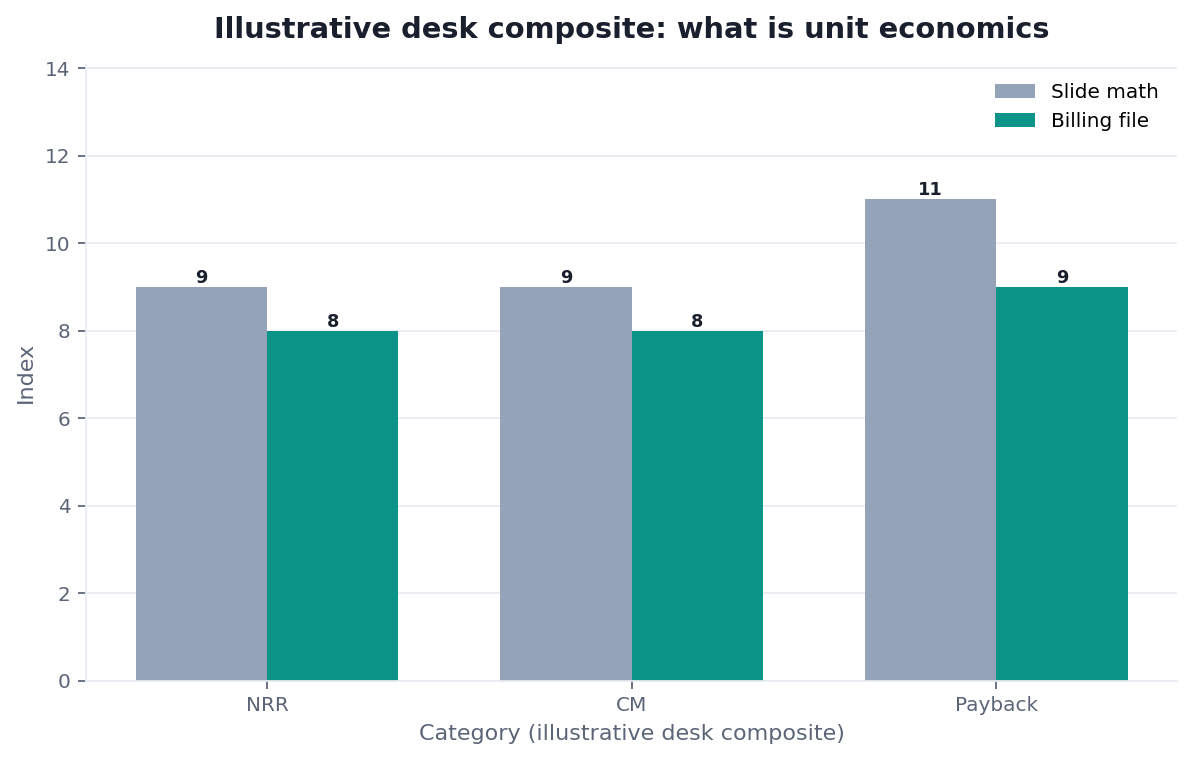
Figure. Two separate synthetic evidence classes and scales. Left: one illustrative per-covered-unit arithmetic scenario. Right: aggregate account coverage. No median, revenue, cash, customer result, or extrapolation.
The left panel must not be multiplied by the right panel. The $258 arithmetic difference is not evidence about any of the 388 covered accounts.
Independent Validation of What Is Unit Economics
An independent reproducer can download the five artifacts without contacting the author, run the verifier, calculate the values manually, and compare all labels with this page. The independent protocol specifies inputs, expected outputs, stop conditions, and disagreement reporting.
What is unit economics under independent validation means another person can reproduce the publication's limited claims from disclosed inputs. It does not mean an external accountant or auditor tested source transactions, controls, completeness, rights and obligations, or financial statements.
Internal editorial reviewers are not represented as independent auditors or accountants. The external links supply definitions and analogy context only. No source certifies this page, the synthetic data, InfiniSynapse, or the arithmetic scenario.
What Is Unit Economics Failure Modes and Bounded Controls
Silent inner joins
A silent inner join drops unmatched records. Preserve the eligible population, report left-join status, and reconcile 410 = 388 + 22. This does not prove source completeness.
Billing labels treated as accounting conclusions
Calling $448 cash or recognized revenue exceeds the evidence. Retain the billing-derived label and route recognition decisions to the entity's accounting policy.
Unsupported cost allocation
Disclose direct versus allocated costs, the allocation key, and excluded pools. Preserve sensitivity outputs when a material allocation choice changes.
Unsupported payback and extrapolation
When CAC is absent, payback invents an input. Multiplying $258 by 388 invents linkage. Hold both outputs explicitly.
What Is Unit Economics Sources and Limited Claims
Direct sources used for billing, recognition, credits, and cost-allocation context:
- Stripe Invoicing overview (retrieved 2026-09-04).
- Stripe revenue recognition: subscriptions and invoicing (retrieved 2026-09-04).
- Stripe revenue recognition: credit-note examples (retrieved 2026-09-04).
- IFRS 15—Revenue from Contracts with Customers (retrieved 2026-09-04).
- FOCUS 1.3 split cost allocation handling (retrieved 2026-09-04).
The CBO, IMF, CDC, HL7, and ClinicalTrials links above are analogies for vintages, definitions, structured fields, and protocols only. They are not financial authorities for what is unit economics and do not substantiate any amount on this page.
What is unit economics here makes limited educational claims from synthetic artifacts. It is not advice, a third-party audit, certification, endorsement, case study, benchmark, or customer result.
Route the next question to the guide that owns it: use usage plus revenue join for key coverage, payback period analysis when CAC exists, and a dashboard only after definitions and checks are stable.
Join billing and usage on one customer grain
Use authorized, sanitized evidence to inspect coverage, labels, and selected costs before publishing a unit result. This check uses only sources you authorize.
Commercial association: You do not need the workspace to complete the educational diagnosis or reproduce the synthetic evidence on this page.
Open InfiniSynapseHow this page is sourced. William Zhu is cofounder of InfiniSynapse (GitHub @allwefantasy); no personal LinkedIn is published. The page provides reproducible publication artifacts and explicit limits. Internal analytics engineering, data platform, LLM security, and editorial reviews are not independent audits or accounting opinions. Editorial standards · corrections · publishing principles. COI: InfiniSynapse sells an AI-native Data Agent; the banner is a commercial association.
Frequently Asked Questions
Do I need a finance warehouse before what is unit economics is reviewable?
Bottom line: No. What is unit economics is reviewable when its unit, inputs, join, costs, coverage, and exclusions are reproducible.
What grain should what is unit economics use?
Bottom line: Use the grain that matches the decision and evidence, then keep it stable. Never combine the two evidence classes.
Is the $448 amount recognized revenue or cash?
Bottom line: No. It is a synthetic billing-derived amount after stated credits. The page provides no payment settlement, refund chronology, performance-obligation assessment, or accounting policy sufficient to label it cash or recognized revenue.
Can I multiply $258 by the 388 covered accounts?
Bottom line: No. The $258 is from one illustrative scenario with no linkage to the aggregate count. Multiplication would fabricate a company-wide result.
Can what is unit economics calculate payback here?
Bottom line: No. CAC is absent, so payback is held. Add an authorized, consistently scoped CAC input and a defensible contribution basis before evaluating payback.
How to Cite What Is Unit Economics
Cite this page as: InfiniSynapse Data Team, “What Is Unit Economics? Audit Billing and Usage,” last verified August 31, 2026, https://infinisynapse.com/en/blog/what-is-unit-economics.
When citing a number, label it synthetic and name its evidence class. For example: “In InfiniSynapse's synthetic aggregate coverage example, 388 of 410 invoice-eligible accounts have the required usage/cost key (94.6% account coverage).” Do not cite that statement as dollar coverage or a company result.
For the scenario, say: “One illustrative per-covered-unit scenario subtracts $190 of selected variable costs from a $448 billing-derived amount after stated credits, yielding a $258 arithmetic difference.” Add that it is not cash, recognized revenue, profit, a benchmark, or a customer result.
This citation guidance does not convert the publication into third-party assurance. The page and artifacts are not a third-party audit.
Conclusion
What is unit economics is best answered as a bounded evidence question, not a universal formula. Define one unit, distinguish billing from cash and recognized revenue, align service and usage periods, disclose selected costs and allocation, print account coverage, and hold unsupported metrics.
The synthetic pack demonstrates only two results: 388 covered plus 22 unmatched equals 410 invoice-eligible accounts, and one separate illustrative scenario gives $448 − ($12 + $138 + $40) = $258. Reproduce those limited claims, preserve their labels, and do not extrapolate.
When your own authorized evidence is ready, you can apply the same checks at https://app.infinisynapse.com/. Keep the source boundary and unresolved gaps visible.