A label is conditional on the range and its error band标签取决于价值区间及其误差带
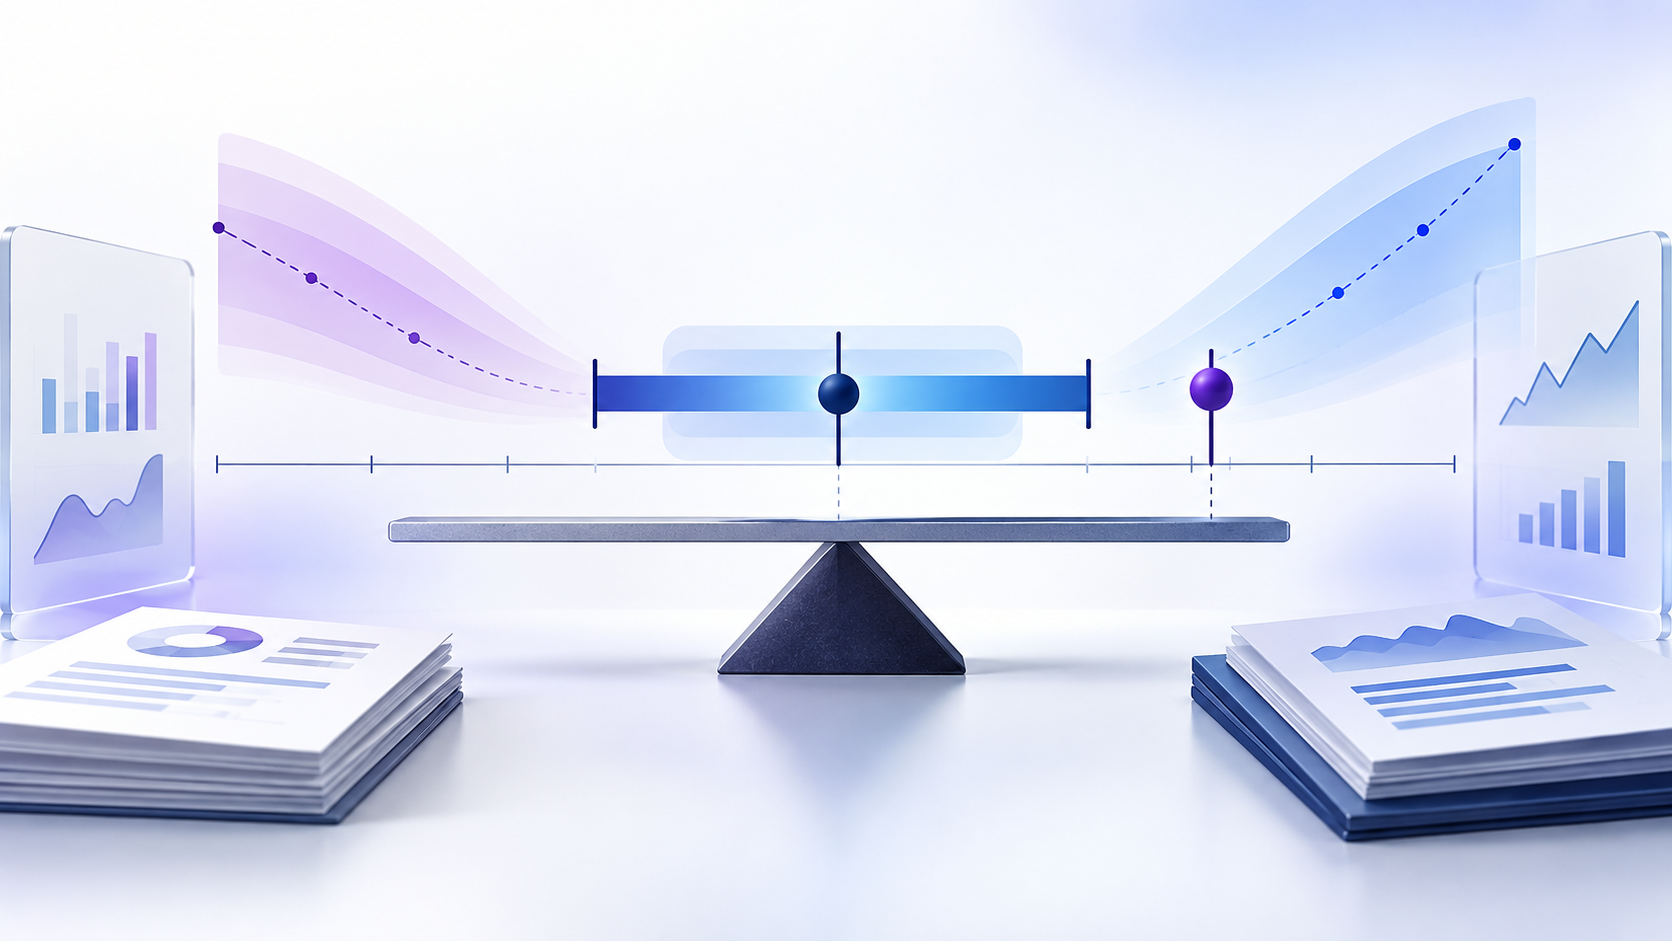
A stock is undervalued only relative to a stated valuation method and assumptions when its market price is meaningfully below the supported value range; it is overvalued when price is meaningfully above. If price overlaps the range or a reasonable error band, the honest result is inconclusive or approximately valued. Date the price, normalize the financial base, reconcile enterprise value through net debt and diluted shares, compare methods, weight scenarios cautiously, and record evidence that could overturn the label.
只有在明确估值方法与假设下,市场价格显著低于有证据支持的价值区间,才能称为相对低估;若价格显著高于区间,则是相对高估;若价格与区间或合理误差带重叠,诚实结论应是暂不能定或大致合理。必须记录价格日期、正常化财务基础,把企业价值经净债务和稀释股数调节到每股价值,比较不同方法,谨慎赋予情景概率,并记录能够推翻标签的证据。
Define the label as a relationship, not a trait把标签定义为关系,而不是公司属性
| Observed relationship on valuation date | Defensible wording | What it does not establish |
|---|---|---|
| Price below the lower supported bound and error band | Undervalued under the stated method and assumptions | When or whether price will converge |
| Price inside or overlapping the range | Approximately valued or unresolved | That every assumption is correct |
| Price above the upper supported bound and error band | Overvalued under the stated method and assumptions | That price must fall |
| Different methods place price differently | Valuation is disputed; identify the assumption causing the split | That averaging methods resolves the disagreement |
| 估值日观察关系 | 可辩护表述 | 不能证明什么 |
|---|---|---|
| 价格低于有支持区间下沿及误差带 | 在所述方法与假设下相对低估 | 价格何时或是否收敛 |
| 价格位于区间内或与区间重叠 | 大致合理或暂不能定 | 所有假设都正确 |
| 价格高于有支持区间上沿及误差带 | 在所述方法与假设下相对高估 | 价格必然下跌 |
| 不同方法把价格放在不同位置 | 估值存在争议,应找出导致分歧的假设 | 取平均能够解决分歧 |
The valuation date controls the available filings, debt, cash, shares and quoted price. A later price paired with earlier net debt is not one coherent snapshot. The value denominator also needs a claim identity: an operating cash-flow or EBITDA method commonly produces enterprise value, while price and earnings attributable to common shareholders relate to equity. Every enterprise result must cross the same bridge before comparison: equity value = enterprise value − net debt − other senior claims + non-operating assets; per-share value = equity value ÷ relevant diluted shares.
估值日决定当时可获得的披露、债务、现金、股数与报价。把更晚价格和更早净债务配在一起,并不是一致快照。价值分母还需要请求权身份:经营现金流或 EBITDA 方法通常产生企业价值,而价格与归属于普通股股东的盈利对应股权。比较前,每个企业价值结果都必须跨过同一座桥:股权价值 = 企业价值 − 净债务 − 其他优先请求权 + 非经营资产;每股价值 = 股权价值 ÷ 相关稀释后股数。
A low nominal price says nothing about total equity value without the share count. A low multiple may reflect a cyclical peak, fragile earnings, leverage, dilution or declining economics. The label requires an independently supported value range.
低价格、低倍数与低估不是同义词没有股数,较低的名义股价无法说明总股权价值;低倍数也可能反映周期高点、盈利脆弱、杠杆、稀释或经济性下滑。高估或低估标签必须建立在独立支持的价值区间上。
Expose the assumptions that create the dispute公开造成估值争议的假设
Separate reported results from analyst adjustments. Test restructuring, launch cost, grants, litigation, credit losses and cyclical margins over comparable periods. An adjustment is an assumption about recurrence, not a discovered fact.
正常化财务基础把已报告结果与分析者调整分开。在可比期间检验重组、投产成本、补助、诉讼、信用损失和周期利润率。调整是关于重复性的假设,不是新发现的事实。
Cash-flow value makes timing, reinvestment and discount rates explicit. Comparable multiples import the market’s pricing of aligned peers. Asset value tests recoverable resources and obligations. Each answers a different question and can fail differently.
三种估值方法现金流价值公开时点、再投资与折现率;可比倍数引入市场对口径一致同业的定价;资产价值检验资源可回收金额与义务。三者回答不同问题,也会以不同方式失效。
Probability weights are researcher assumptions, not measured frequencies unless a valid dataset supports them. Preserve adverse, base and favorable values before calculating a weighted result. The weighted average can hide a wide or asymmetric range.
情景概率除非有有效数据集支持,否则概率权重是研究者假设,不是测得频率。计算加权结果前保留不利、基础和有利价值。加权平均会掩盖宽阔或不对称的区间。
An error band acknowledges estimation noise around a scenario. It must not be selected after seeing price merely to obtain a preferred label. Explain whether it represents model, measurement or forecast uncertainty.
误差带误差带承认单一情景周围存在估算噪声。不能先看到价格,再选择刚好产生偏好标签的带宽。必须解释它代表模型、计量还是预测不确定性。
Keep the methods independent enough to challenge one another. If a DCF terminal value uses a peer multiple and the “independent” comparable method uses the same peers, two outputs may repeat one opinion. Likewise, an order book can support a cash-flow forecast but cannot be added again as if it were a separate asset. Triangulation means tracing disagreements, not counting models.
不同方法应保持足够独立,才能互相质疑。如果 DCF 终值采用同业倍数,而所谓独立可比法又使用同一组同业,两个输出可能只是重复同一观点。同样,订单积压可以支持现金流预测,却不能再作为独立资产加到价值上。三角验证的含义是追踪分歧,不是统计模型数量。
GateVolt Aviation: assemble an evidence boardGateVolt Aviation:建立证据看板
GateVolt Aviation is a completely fictional maker of airport ground-power equipment. All dates, figures and contracts are illustrative and describe no security. The valuation date is June 30, 20X6; the hypothetical market price is CU24.00, net debt is CU24.0m, and expected diluted shares are 10.0m. No pension, minority-interest or other bridge adjustment is assumed.
GateVolt Aviation 是一家完全虚构的机场地面电源设备制造商。全部日期、数字与合同仅用于演示,不对应任何证券。估值日为 20X6 年 6 月 30 日;假设市场价格为 CU24.00,净债务 CU24.0m,预期稀释股数 10.0m。案例假设不存在养老金、非控股权益或其他桥接调整。
| Status | Illustrative evidence |
|---|---|
| Fictional reported base | EBITDA CU32.0m; cash CU14.0m; debt CU38.0m; receivables CU60.0m; inventory CU90.0m; PP&E CU140.0m |
| Analyst normalization | Add CU6.0m launch expense judged non-recurring; subtract CU2.0m grant income: normalized EBITDA CU36.0m |
| Order evidence | Backlog CU150.0m; assumed non-cancellable portion 80%; assumed gross margin on conversion 22% |
| Missing evidence | Customer cancellation clauses, order delivery schedule, warranty history, peer definitions, inventory obsolescence and debt covenants |
| Interpretation | The inputs permit scenario testing but do not establish a single correct value |
| 状态 | 演示证据 |
|---|---|
| 虚构已报告基础 | EBITDA CU32.0m;现金 CU14.0m;债务 CU38.0m;应收 CU60.0m;存货 CU90.0m;PP&E CU140.0m |
| 分析者正常化 | 加回判断为不重复的投产费用 CU6.0m;减去补助收入 CU2.0m:正常化 EBITDA CU36.0m |
| 订单证据 | 积压订单 CU150.0m;假设不可取消部分 80%;假设转化毛利率 22% |
| 缺失证据 | 客户取消条款、订单交付安排、保修历史、同业定义、存货过时与债务契约 |
| 解释 | 这些输入允许测试情景,但不能确立唯一正确价值 |
Normalization calculation: CU32.0m + CU6.0m − CU2.0m = CU36.0m. Reported EBITDA remains CU32.0m; CU36.0m is an analyst assumption used only for the comparable method. Order support is CU150.0m × 80% = CU120.0m assumed convertible revenue and CU120.0m × 22% = CU26.4m potential gross profit. Backlog is neither recognized revenue nor equity value, and the gross-profit estimate still excludes operating costs, tax, reinvestment and timing.
正常化计算:CU32.0m + CU6.0m − CU2.0m = CU36.0m。已报告 EBITDA 仍为 CU32.0m;CU36.0m 只是用于可比法的分析者假设。订单支持量 = CU150.0m × 80% = CU120.0m 假设可转化收入,对应潜在毛利润 = CU120.0m × 22% = CU26.4m。积压订单既不是已确认收入,也不是股权价值;毛利润估算仍未扣除经营成本、税、再投资,也未处理时点。
Make the same price cross three classifications让同一价格穿过三种分类
GateVolt’s illustrative DCF uses unlevered free cash flow and therefore produces enterprise value. For each scenario, EV equals the present value of years 1–5 FCF plus terminal value; terminal value at year 5 equals FCF₅ × (1 + g) ÷ (r − g). The scenario-specific rates and cash paths are assumptions. Each EV then uses the same CU24.0m net-debt deduction and 10.0m diluted-share denominator.
GateVolt 的演示 DCF 使用无杠杆自由现金流,因而产生企业价值。每个情景的 EV = 第 1–5 年 FCF 现值 + 终值现值;第 5 年末终值 = FCF₅ ×(1 + g)÷(r − g)。各情景折现率与现金流路径均是假设。随后每个 EV 都扣除同一 CU24.0m 净债务,并除以 10.0m 稀释股数。
| DCF scenario | FCF years 1–5 (CUm) | r / g | EV | Per-share value | 10% error band | CU24 price classification |
|---|---|---|---|---|---|---|
| Adverse, 25% assumed probability | 12, 14, 16, 18, 20 | 11.0% / 1.5% | CU184.41m | CU16.04 | CU14.44–17.64 | Above band: overvalued in this scenario |
| Base, 50% | 15, 18, 20, 22, 24 | 10.0% / 2.0% | CU263.47m | CU23.95 | CU21.56–26.35 | Inside band: approximately valued |
| Favorable, 25% | 18, 21, 24, 27, 30 | 9.0% / 2.5% | CU398.81m | CU37.48 | CU33.73–41.23 | Below band: undervalued in this scenario |
| DCF 情景 | 第 1–5 年 FCF(CUm) | r / g | EV | 每股价值 | 10% 误差带 | CU24 价格分类 |
|---|---|---|---|---|---|---|
| 不利,假设概率 25% | 12、14、16、18、20 | 11.0% / 1.5% | CU184.41m | CU16.04 | CU14.44–17.64 | 高于误差带:本情景中高估 |
| 基础,50% | 15、18、20、22、24 | 10.0% / 2.0% | CU263.47m | CU23.95 | CU21.56–26.35 | 位于误差带内:大致合理 |
| 有利,25% | 18、21、24、27、30 | 9.0% / 2.5% | CU398.81m | CU37.48 | CU33.73–41.23 | 低于误差带:本情景中低估 |
The assumed probability-weighted value is 25% × CU16.04 + 50% × CU23.95 + 25% × CU37.48 = CU25.36 per share. Compared with CU24.00, that is a 5.4% discount to weighted value: (CU25.36 − CU24.00) ÷ CU25.36. It would be misleading to stop there. The unweighted range is CU16.04–CU37.48, the price sits inside the base error band, and the probabilities are judgments. The dispute map therefore says “approximately valued under the central case, with classification controlled by order conversion and mature cash economics,” not simply “undervalued.”
假设概率加权价值 = 25% × CU16.04 + 50% × CU23.95 + 25% × CU37.48 = 每股 CU25.36。相对 CU24.00,价格较加权价值低 5.4%,即(CU25.36 − CU24.00)÷ CU25.36。但若停在这里会产生误导:未加权区间为 CU16.04–CU37.48,价格位于基础情景误差带内,而且概率只是判断。因此争议地图应写成“中央情景下大致合理,分类受订单转化与成熟期现金经济性控制”,而不是简单写“低估”。
Use multiples and assets to challenge the DCF用倍数和资产边界质疑 DCF
| Cross-check | Calculation | Per-share result | Main limitation |
|---|---|---|---|
| Comparable low | CU36.0m normalized EBITDA × 6.5 = CU234.0m EV; less CU24.0m net debt | CU21.00 | Peer multiple and normalized denominator are assumptions |
| Comparable midpoint | CU36.0m × 7.5 = CU270.0m EV; less net debt | CU24.60 | A midpoint is not evidence of comparability |
| Comparable high | CU36.0m × 8.5 = CU306.0m EV; less net debt | CU28.20 | May import peer optimism or different capital intensity |
| Liquidation-style asset boundary | CU230.0m adjusted resources − CU102.0m debt, liabilities and realization cost | CU12.80 | Ignores going-concern intangibles; recoveries are uncertain |
| 交叉检查 | 计算 | 每股结果 | 主要限制 |
|---|---|---|---|
| 可比法低值 | 正常化 EBITDA CU36.0m × 6.5 = EV CU234.0m;减净债务 CU24.0m | CU21.00 | 同业倍数与正常化分母都是假设 |
| 可比法中值 | CU36.0m × 7.5 = EV CU270.0m;减净债务 | CU24.60 | 中值本身不能证明可比 |
| 可比法高值 | CU36.0m × 8.5 = EV CU306.0m;减净债务 | CU28.20 | 可能带入同业乐观或不同资本强度 |
| 清算式资产边界 | 调整后资源 CU230.0m − 债务、负债与变现成本 CU102.0m | CU12.80 | 忽略持续经营无形价值;回收率不确定 |
The asset boundary assumes cash CU14.0m, 95% recovery on CU60.0m receivables, 70% on CU90.0m inventory, 60% on CU140.0m PP&E, and CU12.0m other realizable assets: CU14.0m + CU57.0m + CU63.0m + CU84.0m + CU12.0m = CU230.0m. Subtracting CU38.0m debt, CU46.0m other liabilities and CU18.0m realization cost gives CU128.0m equity, or CU12.80 per share. This is a stressed boundary, not a forecast sale value or a floor guaranteed by accounting book values.
资产边界假设:现金 CU14.0m;应收 CU60.0m 回收 95%,即 CU57.0m;存货 CU90.0m 回收 70%,即 CU63.0m;PP&E CU140.0m 回收 60%,即 CU84.0m;其他可变现资产 CU12.0m。资源合计 = CU14.0m + CU57.0m + CU63.0m + CU84.0m + CU12.0m = CU230.0m。扣除债务 CU38.0m、其他负债 CU46.0m 与变现成本 CU18.0m,股权为 CU128.0m,即每股 CU12.80。这是压力边界,不是预测成交价,也不是账面价值保证的底价。
GateVolt’s CU26.4m potential backlog gross profit can test near-term FCF and normalized EBITDA. Adding it to the DCF, multiple value or adjusted assets would double count economics already expected in those methods.
订单证据用于核验假设,不是第四堆价值GateVolt 的潜在积压订单毛利润 CU26.4m 可以检验近期 FCF 与正常化 EBITDA。把它再加到 DCF、倍数价值或调整资产上,会重复计算这些方法已经预期的经济收益。
Separate catalysts, traps, and refuting evidence分开记录催化因素、价值陷阱与反证
| Disputed claim | Potential catalyst | Value-trap path | Refuting or updating evidence |
|---|---|---|---|
| Backlog becomes profitable cash | Scheduled deliveries and customer acceptance | Cancellation, delay, discounting or warranty cost | Order roll-forward, cancellations, gross margin and collections |
| Launch cost is temporary | Stable production and rising uptime | Recurring rework, low yield or required redesign | Scrap, uptime, warranty reserve and service reports |
| Net debt is manageable | Refinancing or cash generation | Covenant pressure, higher interest or restricted cash | Debt maturity table, covenants, interest and liquidity notes |
| Per-share value reaches owners | Cash retained or disciplined repurchase | Awards, issuance or acquisition dilution | Share roll-forward, award terms and acquisition consideration |
| 争议主张 | 潜在催化因素 | 价值陷阱路径 | 反证或更新证据 |
|---|---|---|---|
| 积压订单变成有利润现金 | 按计划交付并获客户验收 | 取消、延误、折价或保修成本 | 订单变动、取消、毛利率与回款 |
| 投产成本属于暂时 | 生产稳定、开工率提高 | 返工、低良率或重新设计持续发生 | 废品、开工率、保修准备与服务报告 |
| 净债务可管理 | 再融资或现金创造 | 契约压力、利息上升或现金受限 | 债务到期表、契约、利息与流动性附注 |
| 每股价值归于持有人 | 保留现金或审慎回购 | 股份奖励、发行或收购稀释 | 股数变动、奖励条款与收购对价 |
A catalyst is an event that may reveal or change value; it is not proof that the original estimate was correct. A value trap is not simply a cheap-looking stock that later falls. It is a case in which the low price or multiple reflects deterioration, claims or reinvestment needs omitted from the valuation story. Record the next dated filing or operating event that can distinguish those paths, and retire the old label when its assumptions change.
催化因素是可能揭示或改变价值的事件,并不能证明原估算正确。价值陷阱也不只是“看起来便宜但后来下跌”的股票,而是低价格或低倍数反映了估值叙述遗漏的恶化、优先请求权或再投资需要。应记录下一份能够区分路径的注明日期披露或经营事件;一旦假设变化,就撤销旧标签。
- State the valuation date, market price and source set before stating any label.
- Present the full method ranges, not only the weighted average or preferred endpoint.
- Name the assumption that makes the price cross from overvalued to approximately valued to undervalued.
- List the strongest contrary evidence and the next observable test.
- Do not turn a conditional classification into a personalized transaction instruction.
- 在给出任何标签前,写明估值日、市场价格与来源集合。
- 呈现完整方法区间,而不是只给加权平均或偏好端点。
- 指出使价格从高估跨到大致合理、再跨到低估的关键假设。
- 列出最强反证与下一项可观察检验。
- 不要把条件性分类转换成个性化交易指令。
Build a source-linked valuation dispute pack建立带来源定位的估值争议包
InfiniSynapse is this website’s analysis tool. Upload the complete annual and interim reports, order disclosures or contract extracts, debt and liquidity notes, share-compensation records, and a dated assumption sheet. Ask it to separate reported figures, analyst normalizations and scenario inputs, then map every DCF, multiple and asset adjustment to its source. It should not be treated as a source of an unverified live price, peer multiple, probability or forecast.
Request one reconciliation from enterprise value to equity and diluted per-share value across all methods. Check every material output against the uploaded documents, especially backlog definitions, cancellation rights, cash restrictions, debt-like claims, share dilution, units and periods. Preserve contrary evidence beside the selected range so a polished summary cannot hide why another classification remains plausible.
InfiniSynapse 是本网站提供的分析工具。上传完整年度与中期报告、订单披露或合同摘录、债务与流动性附注、股份支付记录,以及注明日期的假设表。要求工具分离已报告数字、分析者正常化与情景输入,并把每项 DCF、倍数和资产调整映射到来源。不要把它当作未经核验的实时价格、同业倍数、概率或预测来源。
要求所有方法使用同一份企业价值到股权价值及稀释后每股价值调节。对照上传文件核验每个重大输出,尤其是积压订单定义、取消权、现金限制、类债务请求权、股本稀释、单位与期间。把反证与所选区间并列保存,避免流畅摘要掩盖其他分类为何仍可能成立。
Provide filings, debt and share notes, order evidence and a dated assumption sheet; require citations for each normalization and bridge adjustment.
提供披露、债务与股本附注、订单证据和注明日期的假设表,并要求每项正常化和桥接调整都有引用。
Open Stock Explained打开“一眼看懂这只股票”Questions readers ask next读者接下来常问的问题
It can receive both labels under different defensible scenarios or methods, as GateVolt does at CU24. That means the classification is assumption-dependent, not that logic has failed. Show the range and identify which evidence selects between scenarios.
同一价格下,一只股票能否既高估又低估?可以在不同但可辩护的情景或方法下分别得到两个标签,正如 GateVolt 在 CU24 的案例。这表示分类依赖假设,并非逻辑失效。应展示区间,并指出哪些证据能在情景间作选择。
No. The weights are often judgments, the distribution may be wide, and the price may overlap a central error band. Preserve each scenario and test the assumptions rather than allowing one average to erase disagreement.
价格低于概率加权价值,是否就证明低估?不能。权重通常是判断,分布可能很宽,价格还可能与中央误差带重叠。应保留每个情景并检验假设,不能让一个平均值抹去分歧。
Not automatically. Inventory, receivables and specialized equipment may recover less than book value, while liabilities and realization costs may be incomplete. Conversely, book value may omit going-concern intangibles. State recovery assumptions instead of calling accounting equity a floor.
账面价值是否是低估股票的可靠底价?不自动是。存货、应收和专用设备的回收额可能低于账面价值,负债与变现成本也可能不完整;另一方面,账面价值可能遗漏持续经营无形价值。应公开回收假设,而不是把会计权益称为底价。
No. Backlog may support forecast revenue or margins, but those economics are already reflected in a DCF or normalized multiple denominator. Adding backlog value again usually double counts it. Check cancellation, timing, costs and customer acceptance first.
积压订单是否应直接加到企业价值?不应。积压订单可以支持预测收入或利润率,而这些经济收益已经反映在 DCF 或正常化倍数分母中;再次相加通常会重复计算。首先要检查取消、时点、成本与客户验收。
There is no universal percentage. Tie the band to uncertainty in business drivers, measurement and model structure, choose it before comparing with price, and show sensitivity. A highly uncertain case may need scenarios rather than one symmetric band.
估值误差带应有多宽?不存在统一百分比。误差带应连接到业务驱动、计量和模型结构的不确定性,在与价格比较前确定,并展示敏感性。高度不确定的案例可能需要多个情景,而不是一个对称带宽。
Not necessarily. It may reveal information, change cash flows, or already be reflected in price. Define the event, expected economic effect, timing and refuting outcome. A catalyst is not a convergence guarantee.
催化因素一定会缩小估值差距吗?不一定。它可能揭示信息、改变现金流,也可能已经反映在价格中。应定义事件、预期经济影响、时点与反证结果。催化因素不保证价格收敛。
Sources and limits资料来源与边界
SEC EDGAR provides issuer filings; SEC C&DIs address non-GAAP measures; IAS 33 covers basic and diluted EPS; CFA Institute readings discuss free-cash-flow and multiple valuation. None validates GateVolt, its inputs, scenario probabilities, error band, peer set or price.
GateVolt and every figure, contract, date and classification are fictional. Real valuation needs current complete disclosures, comparable definitions and jurisdiction-specific accounting, legal and tax analysis. This dispute map is educational; it is not an appraisal, forecast, assurance conclusion, price target or individualized investment recommendation.
SEC EDGAR 提供发行人披露;SEC C&DIs 讨论非 GAAP 指标;IAS 33 涵盖基本与稀释 EPS;CFA Institute 资料讨论自由现金流与倍数估值。任何来源都不会验证 GateVolt、案例输入、情景概率、误差带、同业集合或价格。
GateVolt 以及全部数字、合同、日期与分类均为虚构。现实估值需要当前完整披露、可比定义,以及针对司法辖区的会计、法律与税务分析。本争议地图仅用于教育,不是评估报告、预测、鉴证结论、目标价或个性化投资建议。