On this page本页目录
What are the hidden costs of ecommerce returns?电商退货有哪些隐性成本?
Hidden return costs are merchant-borne resources or value losses not visible in the refund amount: support time, failed pickup, receiving, inspection, repackaging, storage, markdown, aging, fraud review, disposal, payment effects, and delayed resale. Count a component only when its boundary, evidence, and allocation rule are documented.
隐性退货成本是退款金额看不到、但由商家承担的资源或价值损失,包括客服时间、取件失败、收货、质检、重新包装、仓储、降价、库龄、欺诈审核、报废、支付影响与延迟再售。只有边界、证据和分摊规则明确时才应计入。
“Hidden” does not mean imaginary. It means the amount sits in another system, is absorbed in shared labor, occurs after the refund, or is represented by lost value rather than an invoice. This guide separates observable cost from an estimate and avoids claiming one average hidden-cost percentage for every retailer.
“隐性”并不代表虚构,而是费用存在于另一个系统、被共享人工吸收、在退款后发生,或以价值损失而不是发票呈现。本文区分可观察成本与估计值,也不声称所有零售商都适用同一个隐性成本比例。
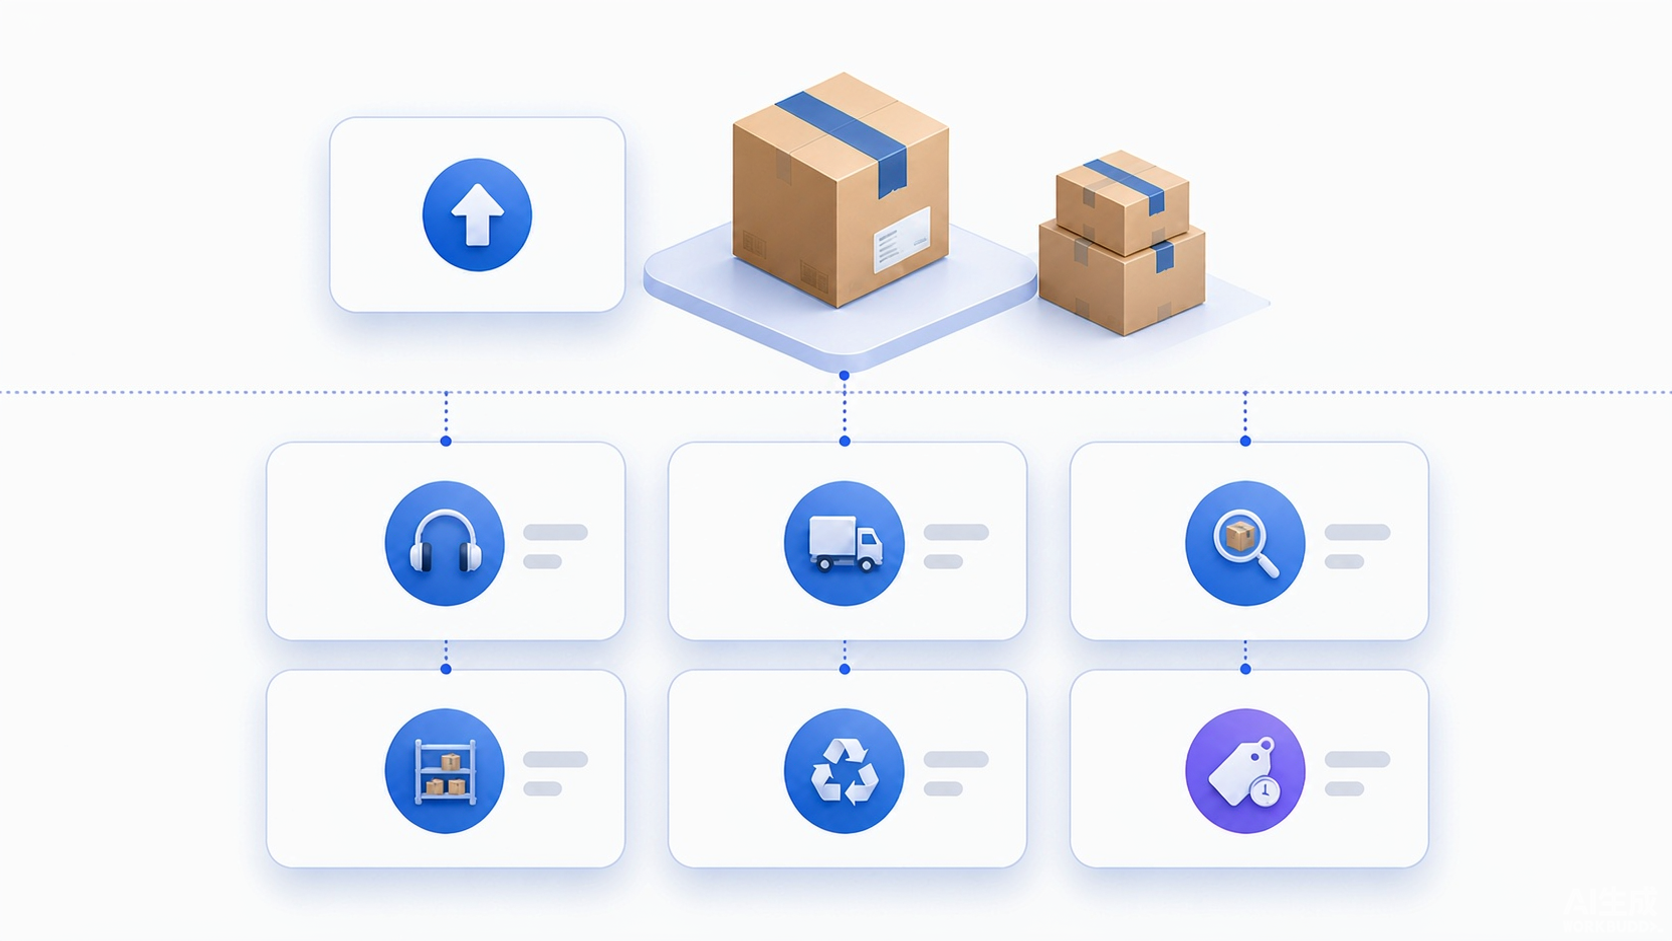
Map hidden costs across the full return lifecycle沿完整退货生命周期绘制隐性成本
Start at the customer contact and end only when the item is restocked, resold, returned to a vendor, donated, liquidated, or disposed. A short measurement window makes late warehouse and recovery effects disappear. Preserve event timestamps so costs can be attributed to both the original sale cohort and the period in which they occur.
从客户联系开始,直到商品重新上架、再售、退回供应商、捐赠、清算或报废才结束。观察窗口过短会让后续仓库与回收影响消失。应保留事件时间,让成本既能归回原始销售群组,也能进入实际发生期间。
Use handle time multiplied by loaded labor rate, plus any case-specific platform or communication charge.使用处理时长乘以含附加成本的人工费率,并加入工单相关平台或通信费用。
Include labels, carrier charges, consolidator fees, failed pickup, duties, and cross-border handling actually borne by the merchant.计入商家实际承担的面单、承运商、集运、取件失败、关税与跨境处理费用。
Measure receiving, opening, inspection, testing, cleaning, repacking, relabeling, and movement time.衡量收货、开箱、质检、测试、清洁、重新包装、贴标与搬运时间。
Record write-down, refurbishment, liquidation, donation, disposal, storage, and recovered value as separate fields.把跌价、翻新、清算、捐赠、报废、仓储与回收价值分别记录。
Verify processor, return-fee, tax, marketplace, and promotional treatment from current contracts and transaction records.根据当前合同和交易记录核验支付、退货费、税费、平台与促销处理。
The refund is visible but is not the checklist. Use it as a separate sales-reversal field. The hidden-cost inventory should explain what happened around and after that reversal.
退款是可见信息,但不是完整检查清单。应把它单列为销售冲回字段;隐性成本清单负责解释冲回前后发生的其他价值变化。
Measure hidden cost without claiming false precision衡量隐性成本时避免虚假精确
Keep opportunity cost, expected recovery, and other modeled values in a separate estimated layer. Report coverage by component: a $0 actual carrier charge is different from a missing invoice, and no measured fraud loss is different from no fraud review data.
机会成本、预期回收和其他模型值应放在独立估计层。按组成项报告覆盖率:实际承运商费用为 0 与发票缺失不同,没有实测欺诈损失也不等于拥有完整欺诈审核数据。
| Input输入项 | Definition定义 | Evidence证据 |
|---|---|---|
| Contact effort联系工作量 | Chats, emails, calls, escalations, and exception handling tied to a return case.与退货案例关联的聊天、邮件、电话、升级与异常处理。 | Help desk events and handle time客服事件与处理时长 |
| Physical touches实体触点 | Pickup, transportation, receiving, inspection, cleaning, repackaging, relabeling, and movement.取件、运输、收货、质检、清洁、重新包装、贴标与搬运。 | Carrier invoice, WMS scan, labor standard承运商发票、WMS 扫描、人工标准 |
| Inventory loss库存损失 | Write-down, damage, obsolescence, markdown, storage, disposal, and unrealized recovery.跌价、损坏、过时、降价、仓储、报废与未实现回收。 | ERP ledger and disposition recordERP 台账与处置记录 |
| Risk handling风险处理 | Fraud review, chargeback research, serial verification, and policy-abuse controls.欺诈审核、拒付调查、序列号核验与政策滥用控制。 | Risk case and outcome code风险案例与结果代码 |
| Delay effect延迟影响 | Days unavailable for sale and the observed difference between expected and realized recovery.不可销售天数,以及预期与已实现回收之间的观察差异。 | Event timeline and resale transaction事件时间线与再售交易 |
Find hidden return costs in seven passes用七轮检查找出隐性退货成本
- Draw the lifecycle绘制生命周期
List customer, carrier, warehouse, finance, inventory, risk, and resale events from request to closure.列出从申请到关闭的客户、承运商、仓库、财务、库存、风险与再售事件。 - Assign an owner分配负责人
Name the system and team that can evidence each event or cost.为每个事件或成本指定能够提供证据的系统与团队。 - Separate actuals and allocations区分实测与分摊
Load traceable charges first; add shared-resource allocation only with a documented driver.先加载可追溯费用;共享资源只有在记录分摊驱动后才加入。 - Extend the window延长观察窗口
Follow the item until final disposition or a declared cutoff, then report still-open cases.跟踪商品直到最终处置或声明的截止点,并报告仍未关闭的案例。 - Measure coverage衡量覆盖率
For every component, show eligible cases, populated cases, missing cases, and estimated cases.对每个组成项展示合格、已填充、缺失与估计案例数。 - Rank recurring loss排序重复损失
Aggregate by product, reason, supplier, channel, carrier, policy, and disposition—not only by total dollars.按商品、原因、供应商、渠道、承运商、政策与处置汇总,而不只看总金额。 - Validate the mechanism验证机制
Inspect samples and operations before labeling a component avoidable or assigning a cause.在把组成项标为可避免或归因前,检查样本与实际操作。
Use the CSV to record lifecycle stage, source system, evidence class, coverage, amount, and follow-up owner. Example rows are synthetic.
使用 CSV 记录生命周期阶段、源系统、证据类别、覆盖率、金额与跟进负责人;示例行均为模拟。
Download CSV template下载 CSV 模板 ↓Worked example: a visible refund leaves five open questions示例:一笔可见退款留下五个待回答问题
A synthetic dashboard shows a $95 refund and appears complete. A lifecycle audit finds an actual $9 carrier charge, 18 minutes of support time, 11 minutes of receiving time, a damaged package, and an item still awaiting disposition after 21 days. Only the carrier fee is immediately monetized; the labor and inventory effects require governed rates or later events.
一个模拟仪表板显示 95 美元退款,看似完整。生命周期审计又发现 9 美元实际承运商费用、18 分钟客服、11 分钟收货、包装损坏,以及一件 21 天后仍待处置的商品。只有承运商费用可以立即金额化;人工与库存影响需要受治理费率或后续事件。
| Finding发现 | Visible in refund report?退款报告可见? | Evidence status证据状态 | Treatment处理方式 |
|---|---|---|---|
| $95 merchandise refund95 美元商品退款 | Yes / 是 | Actual实测 | Sales reversal销售冲回 |
| $9 return label9 美元退货面单 | No / 否 | Actual invoice实际发票 | Hidden operating cost隐性运营成本 |
| 18 support minutes18 分钟客服 | No / 否 | Measured time实测时间 | Allocate with approved rate按批准费率分摊 |
| 11 receiving minutes11 分钟收货 | No / 否 | Measured time实测时间 | Allocate with approved rate按批准费率分摊 |
| Item awaiting disposition商品等待处置 | No / 否 | Open outcome未关闭结果 | Do not assume zero loss or recovery不可假设零损失或零回收 |
The audit can state that at least $9 of actual operating cost is missing from the refund view and that two measured labor inputs and one inventory outcome remain unpriced. It cannot yet publish a complete hidden-cost total. That coverage statement is more accurate than filling every gap with a generic industry average.
审计可以确认退款视图至少漏掉 9 美元实际运营成本,同时有两项实测人工输入与一个库存结果尚未计价;此时还不能发布完整隐性成本总额。这样的覆盖声明比用通用行业平均值填补所有空白更准确。
All store figures in this worked example are synthetic and exist only to demonstrate the method. They are not InfiniSynapse customer results or industry benchmarks.本计算示例中的商店数据全部为模拟值,仅用于说明方法,不代表 InfiniSynapse 客户结果或行业基准。
Prioritize hidden costs by materiality and controllability按重要性与可控性排序隐性成本
A complete inventory is not a mandate to optimize every line. Rank components by total value, frequency, trend, confidence, customer impact, and whether the operating team can change the mechanism. Preserve unavoidable service costs when they protect conversion or loyalty, and test policy changes rather than inferring their effect from one aggregate.
完整清单并不代表每一项都必须优化。应按总价值、频率、趋势、置信度、客户影响与可控性排序。当必要服务成本保护转化或忠诚时应保留,并通过测试政策变更,而不是从一个汇总数字推断效果。
Large repeated cost with sufficient data coverage.金额大、重复发生且数据覆盖充分。
A verified process, policy, product, or routing mechanism can change.已核验的流程、政策、商品或路由机制可以改变。
The proposed action has explicit conversion and experience guardrails.拟议行动具有明确转化与体验护栏。
A before/after or cohort test can observe cost and side effects.前后对比或群组测试能够观察成本与副作用。
NRF’s dated U.S. return estimates show why the topic matters at market level, but they do not reveal an individual retailer’s hidden-cost mix. Build the internal evidence before applying external context.
NRF 带年份的美国退货估计说明该主题的市场重要性,但不能揭示单个零售商的隐性成本结构。应用外部背景前,应先建立内部证据。
Apply six controls before publishing the metric发布指标前应用六项控制
- One case key: connect the return request, parcel, warehouse receipt, disposition, refund, and original order line.统一案例键:连接退货申请、包裹、仓库收货、处置、退款与原始订单行。
- One event policy: declare whether a case begins at request, first carrier scan, receipt, inspection, or refund.统一事件政策:明确案例从申请、首次承运商扫描、收货、质检还是退款开始。
- One currency rule: retain transaction currency, reporting currency, exchange date, and exchange-rate source.统一币种规则:保留交易币种、报告币种、换算日期与汇率来源。
- No silent zeroes: distinguish a measured zero from a missing cost, unknown fee, or unavailable product cost.不把缺失当零:区分实测零值、缺失成本、未知费用和不可用商品成本。
- No double counting: assign every amount to one component and reconcile the component sum to the case total.避免重复计算:每笔金额只能归入一个组成项,并把组成项合计与案例总额对账。
- Evidence labels: mark values as actual, allocated, estimated, benchmark, or synthetic.证据标签:把数值标为实测、分摊、估计、基准或模拟。
Avoid seven hidden-cost audit mistakes避免七个隐性成本审计错误
- Publishing a universal “true cost” multiplier without a matching source, sample, year, or boundary.发布通用“真实成本”倍数,却没有匹配的来源、样本、年份或边界。
- Stopping the lifecycle at refund and omitting warehouse, disposition, and recovery events.在退款时结束生命周期,遗漏仓库、处置与回收事件。
- Turning all shared overhead into return cost without a causal driver.没有因果驱动却把全部共享间接费用变成退货成本。
- Counting expected resale at list price as realized recovery.把按标价计算的预期再售当作已实现回收。
- Treating missing cost fields as zero and calling coverage complete.把成本缺失字段当作零,并声称覆盖完整。
- Calling correlation between a return reason and cost a proven cause.把退货原因与成本的相关性称作已证明原因。
- Optimizing one line while ignoring conversion, repeat purchase, fraud, or customer-contact effects.优化一个成本行时忽视转化、复购、欺诈或客户咨询影响。
Maintain a component dictionary with owner, formula, source, refresh cadence, and coverage threshold. When definitions change, version the metric and restate historical comparisons or visibly break the series.
维护组成项字典,记录负责人、公式、来源、刷新频率与覆盖阈值。定义变化时,应对指标进行版本化,并重述历史比较或明确断开序列。
Convert one hidden component into a testable action把一个隐性组成项转化为可测试行动
Select a recurring component with strong evidence, inspect the cases, identify an operational mechanism, and define a limited test. Use control or matched cohorts when possible. Keep a customer, revenue, risk, and recovery guardrail beside the cost metric.
选择证据充分、重复发生的组成项,检查案例,识别运营机制并定义有限测试。条件允许时使用对照或匹配群组,同时为成本指标设置客户、收入、风险与回收护栏。
| Signal信号 | Check next下一步检查 | Possible action可能行动 |
|---|---|---|
| Support minutes cluster by reason客服分钟集中于某原因 | Reason wording, self-service path, repeat contacts原因措辞、自助路径、重复联系 | Clarify guidance and test assisted workflow澄清指引并测试辅助流程 |
| Disposition delay creates markdown处置延迟带来降价 | Queue age, inspection rules, sellable grade, seasonality队列年龄、质检规则、可售等级、季节性 | Fast-route eligible units and monitor errors快速路由合格商品并监控错误 |
| Packaging damage drives write-down包装损坏推动跌价 | SKU, packaging type, carrier, damage photosSKU、包装类型、承运商、损坏照片 | Test packaging or handling change on matched SKUs在匹配 SKU 上测试包装或操作变更 |
Build a complete return-cost coverage map建立完整退货成本覆盖图
Export case IDs, lifecycle events, handle time, actual charges, inventory outcomes, recovery transactions, source owners, and evidence classes. Return Compass can help segment a governed file; it cannot convert missing evidence into measured cost.
导出案例 ID、生命周期事件、处理时长、实际费用、库存结果、回收交易、来源负责人和证据类别。逆向罗盘可帮助细分受治理文件,但不能把缺失证据变成实测成本。
Open Return Compass打开逆向罗盘 →Hidden Costs of Returns FAQ退货的隐性成本常见问题
Common components include support time, transport exceptions, receiving, inspection, repackaging, storage, markdown, write-down, fraud review, disposal, delayed resale, and payment effects.常见组成项包括客服时间、运输异常、收货、质检、重新包装、仓储、降价、跌价、欺诈审核、报废、延迟再售与支付影响。
No. The refund is normally a visible sales or payment reversal. Keep it separate, then map the less-visible operating and value effects around it.通常不属于。退款是可见的销售或支付冲回,应单独保留,再绘制其周边不易看见的运营与价值影响。
Tie timestamps or measured standard minutes to each case, multiply by an approved loaded labor rate, and label the result as actual or allocated.把时间戳或实测标准分钟关联到案例,乘以获批的含附加成本人工费率,并标注为实测或分摊。
Show it in a separate estimated layer with the model and uncertainty disclosed. Do not mix it silently with invoiced charges or realized inventory loss.可以放入独立估计层,但必须披露模型与不确定性,不得与发票费用或已实现库存损失静默混合。
Review coverage and operational components on a cadence that matches the decision cycle, and revalidate definitions whenever policy, carrier, warehouse, accounting, or system logic changes.按决策周期审核覆盖与运营组成项,并在政策、承运商、仓库、会计或系统逻辑变化时重新核验定义。
Sources, evidence labels, and limitations来源、证据标签与限制
- National Retail Federation: 2025 Retail Returns Landscape — Primary U.S. market context. Its annual estimates and survey findings are dated, sampled context—not universal operating assumptions.美国零售联合会:2025 零售退货报告——美国市场的一手背景来源;其年度估计和调查结论具有年份与样本限制,不能作为所有企业的通用经营假设。
- Shopify Help Center: Sales reports — Official definitions for gross sales, net sales, sales reversals, returned quantity, return fees, and returned quantity rate.Shopify 帮助中心:销售报告——毛销售额、净销售额、销售冲回、退回件数、退货费和退回件数率的官方定义来源。
- Shopify Help Center: Sales discrepancies — Official explanation of why returns in sales reports and refunds in payments finance reports can differ by event, timing, and scope.Shopify 帮助中心:销售差异——官方说明销售报告中的退货与支付财务报告中的退款为何会因事件、时间与范围而不同。
- UPS Supply Chain Solutions: Reverse logistics — Operational source used only to structure collection, receipt, inspection, grading, disposition, recommerce, and disposal stages.UPS 供应链解决方案:逆向物流——仅用于构建收件、到仓、质检、分级、处置、再销售与报废等运营阶段。
Evidence statement: Official sources define platform metrics and operational stages; the example is synthetic. No universal hidden-cost multiplier is used. No customer result, causal claim, universal threshold, or guaranteed improvement is asserted. Source review was frozen on September 15, 2026, and a named reviewer is required before publication.证据声明:官方来源用于定义平台指标与运营阶段,示例为模拟数据。本文不使用通用隐性成本倍数。本文不声称客户结果、因果结论、通用阈值或保证改善。来源核验冻结于 2026 年 9 月 15 日,发布前仍需具名审核人。
Make hidden return costs visible before optimizing them先让隐性退货成本可见,再进行优化
Follow each return from request to final disposition, separate actual charges from allocations and estimates, and report component coverage. The useful output is not a dramatic universal multiplier; it is a governed map of repeated, material, controllable loss with enough evidence to support a limited test.
从申请到最终处置跟踪每笔退货,区分实际费用、分摊与估计,并报告组成项覆盖率。有价值的输出不是夸张的通用倍数,而是一张受治理的损失地图,显示哪些损失重复、重要且可控,并提供足以支持有限测试的证据。