Dilution changes the slice, not necessarily the whole pie稀释改变的是切片,不一定缩小整块蛋糕
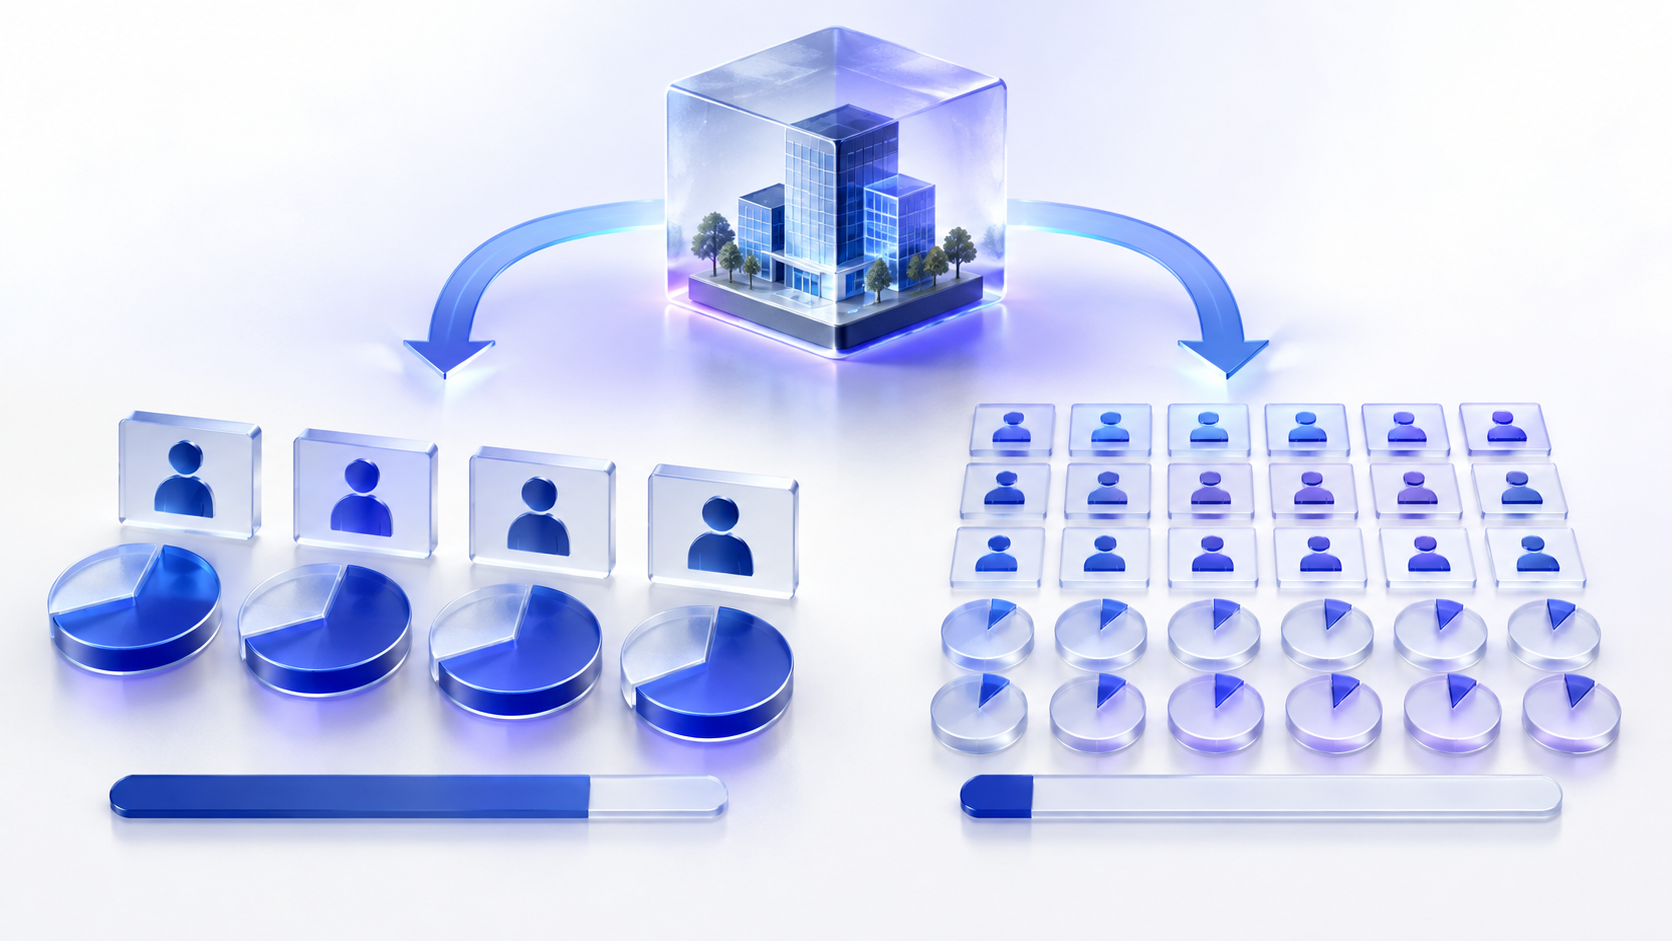
Stock dilution is the reduction in an existing common shareholder’s ownership percentage or per-share economic claim when outstanding shares increase, or the exposure to such a reduction from potential shares. Measure actual ownership dilution with period-end outstanding shares; measure period earnings per share with weighted-average basic or diluted shares; and keep a separate scenario inventory for awards, options, convertibles, acquisition consideration, at-the-market programs, rights offerings, and other possible issuances. Authorized capacity is not issued stock, a grant is not automatically an outstanding share, and a potential share excluded as anti-dilutive from accounting diluted EPS can still dilute ownership if later issued. Repurchases can offset issuance, but compare gross issuance, buybacks, cash paid, and the closing share count. Dilution can be value-creating if new capital or an acquired business adds more value than the ownership surrendered; the arithmetic identifies the smaller slice, while evidence about proceeds and returns determines whether the trade was worthwhile.
股票稀释是指发行在外普通股增加后,现有普通股股东的持股比例或每股经济请求权下降;尚未发行但可能转为普通股的工具,则形成潜在稀释。实际所有权变化应使用期末发行在外股数,期间每股收益使用基本或稀释加权平均股数,另外还要建立一份情景清单,记录股份奖励、期权、可转债、并购对价、ATM 增发计划、配股和其他潜在发行。授权额度不等于已发行股份,授予奖励不自动等于发行在外股份,被会计稀释 EPS 因反稀释而排除的工具未来实际发行时仍可能稀释所有权。回购可以抵销增发,但必须同时看新增股份、回购数量、支付现金与期末净股数。若新资本或被收购业务创造的价值超过让出的所有权,稀释也可能创造价值;算术只能说明切片变小,资金用途与回报证据才决定交换是否划算。
Measure the existing holder’s shrinking slice测量原股东变小的所有权切片
Share-count growth = (new outstanding shares − old outstanding shares) ÷ old outstanding shares. Existing-holder ownership loss = 1 − (old shares ÷ new shares), when the holder buys or sells nothing. These percentages are not equal because their denominators differ.
两个容易混淆的百分比股数增长率 =(新发行在外股数 − 原发行在外股数)÷ 原发行在外股数。原股东所有权损失率 = 1 −(原发行在外股数 ÷ 新发行在外股数),前提是该股东不买不卖。两者分母不同,百分比不会相等。
Suppose an investor owns 1.0 million shares while the company has 100 million outstanding: the stake is 1.00%. If company issuance takes outstanding shares to 118 million and the investor does not participate, the stake becomes 1 ÷ 118 = 0.847%. The decline is 0.153 percentage points, or 1 − 0.847% ÷ 1.00% = 15.25% relative ownership dilution. Meanwhile, company share count grew 18%. State which percentage is being reported.
假设投资者持有 100 万股,公司原有 1 亿股发行在外,持股比例为 1.00%。若公司增发后达到 1.18 亿股且该投资者没有参与,其持股变为 1 ÷ 118 = 0.847%。下降幅度是 0.153 个百分点;相对所有权稀释为 1 − 0.847% ÷ 1.00% = 15.25%。与此同时,公司股数增长率为 18%。结论必须说明报告的是哪一个百分比。
HelixBench: rebuild the annual share waterfallHelixBench:重建年度股份瀑布
HelixBench Instruments is a fictional maker of gene-testing instruments. All figures are invented. The reporting year ends 31 December 20X5; share counts are in millions and money is USD millions.
虚构案例事实HelixBench Instruments 是虚构的基因检测仪器制造商。所有数字均为教学假设;报告年度截至 20X5 年 12 月 31 日,股数单位为百万股,金额单位为百万美元。
| Actual outstanding-share event | Date | Change | Closing effect | 20X5 weighted effect |
|---|---|---|---|---|
| Opening outstanding shares | 1 Jan | 100 | 100 | 100.000 |
| ATM shares sold for cash | 1 Apr | +12 | +12 | +9.000 (9/12 year) |
| Shares issued as acquisition consideration | 1 Jul | +8 | +8 | +4.000 (6/12 year) |
| Employee RSUs vest and shares issue | 1 Oct | +3 | +3 | +0.750 (3/12 year) |
| Shares repurchased into treasury | 1 Nov | −5 | −5 | −0.833 (2/12 year) |
| Closing / basic weighted average | 31 Dec / year | Net +18 | 118 | 112.917 |
| 实际发行在外股份事件 | 日期 | 变动 | 期末影响 | 20X5 加权影响 |
|---|---|---|---|---|
| 期初发行在外股份 | 1 月 1 日 | 100 | 100 | 100.000 |
| ATM 计划实际售股融资 | 4 月 1 日 | +12 | +12 | +9.000(存续 9/12 年) |
| 作为收购对价发行股份 | 7 月 1 日 | +8 | +8 | +4.000(存续 6/12 年) |
| 员工 RSU 归属并发行股份 | 10 月 1 日 | +3 | +3 | +0.750(存续 3/12 年) |
| 回购并转入库存股 | 11 月 1 日 | −5 | −5 | −0.833(减少 2/12 年) |
| 期末 / 基本加权平均 | 12 月 31 日 / 全年 | 净增 18 | 118 | 112.917 |
The closing bridge is 100 + 12 + 8 + 3 − 5 = 118. The period denominator is 100 + 12 × 9/12 + 8 × 6/12 + 3 × 3/12 − 5 × 2/12 = 112.917. Assume opening issued shares were 110 and treasury shares were 10. New issues add 23 to issued shares; the buyback adds 5 to treasury. Closing issued shares are 133, treasury shares 15, and outstanding shares 118. The ATM authorization itself and unvested awards do not enter this actual-share waterfall until shares are issued under the stated assumptions.
期末股份桥为 100 + 12 + 8 + 3 − 5 = 118。期间基本分母为 100 + 12 × 9/12 + 8 × 6/12 + 3 × 3/12 − 5 × 2/12 = 112.917。再假设期初已发行 110、库存股 10;三项新发行合计增加已发行股 23,回购使库存股增加 5,因此期末已发行 133、库存股 15、发行在外 118。按本案例假设,ATM 授权额度本身和尚未归属的奖励,在股份实际发行前都不进入这张实际股份瀑布。
Route each instrument through its true entry point让每种工具从真实入口进入股本
SBC expense is an accounting amount, not a share count. Grants create contingent claims; vesting and settlement determine actual issuance. Options require exercise terms, average price, forfeitures, and settlement method before estimating incremental shares.
股份薪酬、RSU 与期权股份薪酬费用是会计金额,不是股数。授予形成附条件请求权,归属与结算方式决定实际发行;期权还需结合行权价、期间平均价格、没收和结算方式估计增量股数。
Conversion can add common shares and remove interest or preferred distributions. Accounting diluted EPS adjusts both numerator and denominator when inclusion is dilutive; a capital-structure scenario must also track debt reduction and conversion conditions.
可转换工具转换会增加普通股,同时可能消除利息或优先分派。会计稀释 EPS 在具有稀释作用时同时调整分子和分母;资本结构情景还要追踪债务减少及转换条件。
Program capacity is not outstanding stock. Record shares actually sold, dates, net proceeds, remaining capacity, and use of funds. A pro-rata rights issue may let a participating holder preserve ownership; a nonparticipant can be diluted when shares issue.
ATM、后续增发与配股计划容量不是发行在外股份。应记录实际售出股数、日期、净所得、剩余额度和资金用途。按比例配股可能让参与股东维持持股比例;未参与者会在股份发行后被稀释。
Shares delivered at closing are actual issuance. Earn-out shares remain conditional until the contract’s milestones and accounting treatment are assessed. Compare ownership surrendered with acquired earnings, cash, assets, liabilities, and integration costs.
并购发股与或有对价交割时交付的股份属于实际发行;业绩对赌股份在合同里程碑与会计处理核实前仍有条件。应把让出的所有权与收购所得利润、现金、资产、负债和整合成本比较。
A repurchase can reduce outstanding shares, but it is not free: record cash spent, timing, treasury or cancellation treatment, and later reissuance. Gross SBC issuance can continue even when net shares decline.
股份回购回购可以减少发行在外股份,但并非免费:要记录支付现金、时间、库存或注销处理及后续再发行。即便净股数下降,股份薪酬导致的总发行仍可能持续。
Pass potential shares through the accounting gate让潜在股份通过会计稀释闸门
| HelixBench potential claim | Simplified 20X5 treatment | Why |
|---|---|---|
| 10 options, exercise price 8; average market price 20 | +6.0 incremental shares | Simplified treasury-stock logic: 10 × (20 − 8) ÷ 20 |
| Unvested awards | +2.0 incremental shares | Illustrative amount after applying the relevant award terms and EPS method |
| Convertible debt: 6 shares on conversion; 3 after-tax interest add-back | Excluded as anti-dilutive | Incremental earnings per share is 3 ÷ 6 = 0.50, above basic EPS of about 0.40 |
| Performance awards up to 5 shares | Excluded from this year’s denominator | Case conditions are not met; retain in potential-dilution inventory |
| Unsold ATM capacity of 13 shares | Not in accounting diluted EPS | No shares sold; model only as a financing scenario |
| HelixBench 潜在请求权 | 简化 20X5 处理 | 原因 |
|---|---|---|
| 期权 10、行权价 8、期间平均市价 20 | 增量股数 +6.0 | 简化库存股法逻辑:10 ×(20 − 8)÷ 20 |
| 未归属奖励 | 增量股数 +2.0 | 依奖励条款与适用 EPS 方法处理后的案例金额 |
| 可转债:转换新增 6 股,税后利息加回 3 | 因反稀释而排除 | 增量每股收益 3 ÷ 6 = 0.50,高于约 0.40 的基本 EPS |
| 最多 5 股的业绩奖励 | 不进入本年度分母 | 案例条件尚未满足,但保留在潜在稀释清单 |
| ATM 尚未售出的 13 股容量 | 不进入会计稀释 EPS | 尚未售股,只作为融资情景建模 |
With net income attributable to common shareholders of 45, basic EPS is 45 ÷ 112.917 = 0.3985, reported as 0.40 at two decimals. The simplified diluted denominator is 112.917 + 6 + 2 = 120.917, so diluted EPS is 45 ÷ 120.917 = 0.3722, or 0.37. The convertible is excluded because including 3 of earnings and 6 shares would increase, not reduce, EPS. Anti-dilutive means excluded from that period’s accounting diluted EPS—not incapable of future ownership dilution. Conversion could still occur if contractual or market conditions are met.
归属于普通股股东的净利润为 45,则基本 EPS = 45 ÷ 112.917 = 0.3985,保留两位小数列示为 0.40。简化稀释分母为 112.917 + 6 + 2 = 120.917,稀释 EPS = 45 ÷ 120.917 = 0.3722,即 0.37。可转债被排除,是因为同时加入利润 3 和股份 6 会提高而非降低 EPS。“反稀释”只表示不进入当期会计稀释 EPS,并不表示未来不可能稀释所有权;若合同或市场条件满足,转换仍可能发生。
Close with a claim ledger, not one diluted number用请求权账本收尾,而不是只留一个稀释数字
- Reported facts: capture authorized, issued, treasury, outstanding, weighted-average basic and diluted shares; each class; actual issuance dates; proceeds; repurchase cash; and award or conversion terms.
- Calculations: reconcile the closing waterfall, time weights, ownership percentage, option increment, basic and diluted EPS, and chosen per-share cash measure without mixing dates.
- Assumptions: label average price, exercise proceeds, tax effects, vesting, performance attainment, settlement choice, conversion timing, future ATM sales, and whether repurchased shares remain in treasury.
- Judgment: decide whether ownership surrendered bought sufficient durable value; do not infer that a smaller slice is automatically a worse investment outcome.
- Unresolved claims: preserve anti-dilutive instruments, unvested awards, earn-outs, remaining plan capacity, unsold offering capacity, and post-period issuance outside the accounting diluted denominator.
- 已报事实:记录授权、已发行、库存、发行在外、基本及稀释加权平均股数,各股份类别,实际发行日、所得、回购现金,以及奖励或转换条款。
- 计算:在不混淆日期的前提下,勾稽期末瀑布、时间权重、持股比例、期权增量、基本和稀释 EPS 以及所选每股现金指标。
- 假设:标记期间平均价格、行权所得、税务影响、归属、业绩条件、结算选择、转换时间、未来 ATM 售股及回购股是否保留为库存股。
- 判断:评估让出的所有权是否换得足够持久价值;不能因为切片变小就自动判定投资结果更差。
- 未解决请求权:在会计稀释分母之外保留反稀释工具、未归属奖励、或有并购股份、计划剩余额度、未售增发容量和期后发行。
Reconcile three share ledgers from uploaded disclosures从上传披露勾稽三本股份账
Upload the current and prior equity statements, EPS notes, common-stock and treasury-stock roll-forwards, SBC and equity-plan notes, option and RSU tables, convertible terms, acquisition consideration, offering prospectuses, ATM sales, rights materials, repurchase disclosures, and post-period events. Ask InfiniSynapse Stock Explained to build separate closing-outstanding, basic weighted-average, and potential-claim ledgers with dates and source pages.
Treat the extracted waterfall and dilution scenarios as drafts. Return to the uploaded original filings, prospectuses, plan documents, award tables, and conversion agreements to verify share classes, units, dates, price assumptions, forfeitures, tax effects, settlement choices, anti-dilutive exclusions, proceeds, and citations. AI may confuse granted with vested awards, authorized with issued shares, gross options with incremental shares, or an unsold facility with completed issuance.
上传当期与上期权益变动表、EPS 附注、普通股和库存股变动、股份薪酬及激励计划附注、期权与 RSU 表、可转债条款、并购对价、发行说明书、ATM 实际售股、配股材料、回购披露和期后事项。可要求 InfiniSynapse“一眼看懂这只股票”分别建立期末发行在外、基本加权平均和潜在请求权三本账,并保留日期和来源页。
提取出的股份瀑布与稀释情景只能作为草稿。必须回到上传的原始申报、说明书、计划文件、奖励表和转换协议,核验股份类别、单位、日期、价格假设、没收、税务影响、结算选择、反稀释排除、所得及引用。AI 可能混淆授予与归属、授权与已发行、期权总数与增量股数,或把尚未售股的额度误认作已完成发行。
Include equity and EPS notes, plan and award schedules, option terms, convertible agreements, acquisition share consideration, offering sales, rights participation, treasury-stock activity, and post-year-end issuances.
请包含权益与 EPS 附注、计划和奖励明细、期权条款、可转债协议、并购股份对价、增发销售、配股参与、库存股活动及期后发行。
Open Stock Explained打开“一眼看懂这只股票”Questions after the share waterfall is reconciled股份瀑布勾稽后的具体问题
No. Authorization creates capacity, not outstanding shares. Dilution occurs when shares are actually issued or when a potential claim is evaluated in a relevant diluted-EPS or scenario denominator. Approvals and rights depend on jurisdiction and governing documents.
授权股数增加会立即稀释股东吗?不会。授权只产生发行容量,并不等于发行在外股份。股份实际发行,或潜在请求权进入相关稀释 EPS 或情景分母时,才体现稀释;批准程序和权利取决于司法辖区及治理文件。
The 18 new net shares were not outstanding for the full year. Time weighting recognizes the April, July, October, and November dates, producing 112.917 versus the 100 opening base, a 12.9% average increase.
为什么期末股数增加 18%,加权平均股数只增加 12.9%?净增 18 股并非全年都在外流通。对 4 月、7 月、10 月和 11 月事件按时间加权后,平均分母为 112.917,相对期初 100 增加约 12.9%。
Yes. Anti-dilutive describes its exclusion from a particular period’s diluted-EPS calculation. If conversion conditions are later met and common shares issue, ownership can still decline. Keep it in the potential-claim inventory.
被判定反稀释的可转债以后仍会稀释我吗?会。“反稀释”只描述该工具被排除在某一期间稀释 EPS 之外。以后若满足转换条件并实际发行普通股,持股比例仍可能下降,因此要保留在潜在请求权清单。
They can offset the net share count, but the company spends cash and may later reissue treasury shares. Compare gross award issuance, exercises, withholding, repurchases, cash cost, and the multi-year closing count.
回购能完全抵销员工股份稀释吗?回购可以抵销净股数,却会消耗公司现金,而且库存股以后可能重新发行。应比较奖励总发行、行权、代扣、回购、现金成本及多年期末股数。
A holder who receives and fully exercises proportionate rights may preserve percentage ownership, subject to the terms. A holder who does not participate can be diluted when new shares issue. The cash commitment and value of rights also matter.
配股是否不会造成稀释?在条款允许的情况下,获得并足额行使按比例权利的股东可能维持持股比例;不参与者会在新股发行后被稀释。所需追加现金和权利本身的价值也要考虑。
When the after-cost value of cash, assets, capabilities, or earnings acquired per surrendered ownership claim exceeds the counterfactual without issuance. Test realized returns and cash contribution over time rather than relying on management’s stated purpose.
稀释在什么情况下可能创造价值?若让出所有权换得的现金、资产、能力或利润在扣除成本后的价值,高于不发行股份的反事实,稀释可能创造价值。应持续核验实际回报和现金贡献,而不只依赖管理层所述用途。
Primary sources for EPS, share plans, and equity disclosureEPS、股份计划与权益披露的一手来源
HelixBench Instruments, its capital structure, awards, convertible, acquisition, offering, repurchase, prices, profits, cash flow, and every share count are fictional teaching inputs. They describe no issuer or security.
Share rights, authorization, issuance, treasury treatment, award settlement, EPS methods, offering rules, and conversion consequences depend on jurisdiction, reporting framework, contracts, and share class. A scenario denominator is not a forecast, valuation, or accounting measure. Use complete current filings and appropriate professional advice; this page is educational, not individualized investment advice.
HelixBench Instruments、其股本结构、奖励、可转债、收购、增发、回购、价格、利润、现金流和全部股数均为虚构教学输入,不描述任何发行人或证券。
股份权利、授权、发行、库存股处理、奖励结算、EPS 方法、发行规则和转换后果取决于司法辖区、报告框架、合同及股份类别。情景分母不是预测、估值或会计指标。请使用完整当前申报并在适当时寻求专业意见;本文仅用于学习,不构成个性化投资建议。