The direct answer直接答案
Customer concentration risk is dependence on one customer, group, channel, or end market that makes revenue, margin, collection, or asset recovery unusually sensitive. Measure each exposure for a stated period or date: revenue and gross profit are flows; receivables, contract assets, orders, and dedicated assets are point-in-time balances. Then inspect common control, channel pass-through, cancellation rights, price leverage, collections, and asset redeployment. A high share signals dependence, not certain loss; contracts, replacement capacity, and liquidity shape the outcome.
客户集中度风险,是指企业依赖某个客户、客户集团、渠道或终端市场,使收入、毛利、收款或资产回收对这一关系异常敏感。应按明确期间或日期分别衡量:收入与毛利是期间流量,应收、合同资产、订单和专用资产是时点暴露。随后检查共同控制、渠道穿透、合同期限、取消权、议价能力、回款和资产转用能力。较高占比说明存在依赖,并不代表损失必然发生;合同质量、替代客户能力与流动性才决定依赖如何传导到业绩。
Choose the exposure before calculating a percentage计算百分比前,先选择要衡量的暴露
| Denominator | Date basis | Question answered | Common blind spot |
|---|---|---|---|
| Revenue | Full fiscal period | How much reported sales depend on the customer? | Says little about margin or cash already at risk |
| Gross profit | Same fiscal period | How much economic contribution may disappear? | Customer-level costs may require estimation |
| Receivables | Reporting date | How much unconditional billed credit is exposed? | A year-end balance can be seasonal |
| Contract assets | Reporting date | How much performed work remains conditional before billing? | Recoverability depends on terms and progress evidence |
| Orders or backlog | Stated measurement date | How much future activity is associated with the customer? | Cancellation and nonbinding portions can weaken the number |
| Dedicated assets | Reporting date | What capital may be hard to redeploy? | Book value is not recoverable value |
| 分母 | 日期口径 | 回答的问题 | 常见盲点 |
|---|---|---|---|
| 收入 | 完整财政期间 | 已报告销售中有多少依赖该客户? | 很少说明毛利或已暴露现金 |
| 毛利 | 相同财政期间 | 可能消失的经济贡献有多大? | 客户层面成本可能需要估算 |
| 应收账款 | 报告日 | 无条件已开票信用暴露有多大? | 年末余额可能受季节性影响 |
| 合同资产 | 报告日 | 已履约但开票权仍有条件的金额是多少? | 可收回性取决于条款和进度证据 |
| 订单或在手订单 | 明确计量日 | 未来活动中有多少与该客户相关? | 取消权和非约束部分会削弱数字意义 |
| 专用资产 | 报告日 | 有多少资本难以转作他用? | 账面价值不等于可收回价值 |
Write each measure as numerator ÷ matching denominator. Top-1 revenue concentration is the largest customer's revenue divided by same-period external revenue; top-5 uses the five largest. Do not mix quarterly and annual flows or closing and average balances. When only customers above a disclosure threshold appear, the filing provides a partial map, not a complete ranking.
每个指标都应写成“分子÷匹配分母”。第一大客户收入集中度,等于同一期间最大客户收入除以外部总收入;前五大客户集中度,等于前五名收入之和除以该总额。不能用单季分子除以全年收入,也不能把期末应收与平均余额混用而不说明。若披露只覆盖超过门槛的客户,文件提供的只是局部地图,并非完整排名。
IFRS 8 paragraph 34 uses 10% of revenue as a major-customer disclosure trigger and treats entities known to be under common control as one customer. It does not declare 9.9% safe, nor does it require the customer's identity. Apply the issuer's actual reporting framework and read the note wording.
披露门槛不是安全门槛IFRS 8 第 34 段以收入的 10% 作为主要客户披露触发点,并把报告主体已知受共同控制的实体视为一个客户;它并未认定 9.9% 就安全,也不要求披露客户身份。实际分析必须依据发行人的报告框架并阅读附注原文。
Find the economic customer behind the invoice穿透发票抬头,找到经济客户
The entity named on the invoice and receivable. This view matters for collection, setoff, guarantees, jurisdiction, and credit loss. Aggregate parents and subsidiaries when the applicable framework or economic analysis requires it.
法律交易对手发票和应收上列示的主体。这个视角决定收款、抵销、担保、司法管辖和信用损失。适用准则或经济分析要求时,应合并母公司与子公司。
A distributor may owe the cash while an aircraft maker creates the demand. Losing the end program can hurt volume even when the named distributor remains solvent. Do not count the same sale twice when regrouping exposure.
渠道交易对手分销商可能承担付款义务,而飞机制造商才创造需求。即使开票分销商仍有偿付能力,失去终端机型项目也会打击销量。重新归组时不能把同一笔销售计算两次。
Different plants, airlines, or agencies may share procurement, budgets, platform approval, or common control. Conversely, divisions of one group can have independent demand. State why accounts are grouped instead of assuming names equal diversification.
经济决策单元不同工厂、航空公司或机构可能共用采购、预算、平台认证或共同控制;同一集团的不同部门也可能拥有独立需求。应说明归组原因,不能把名称不同自动当作多元化。
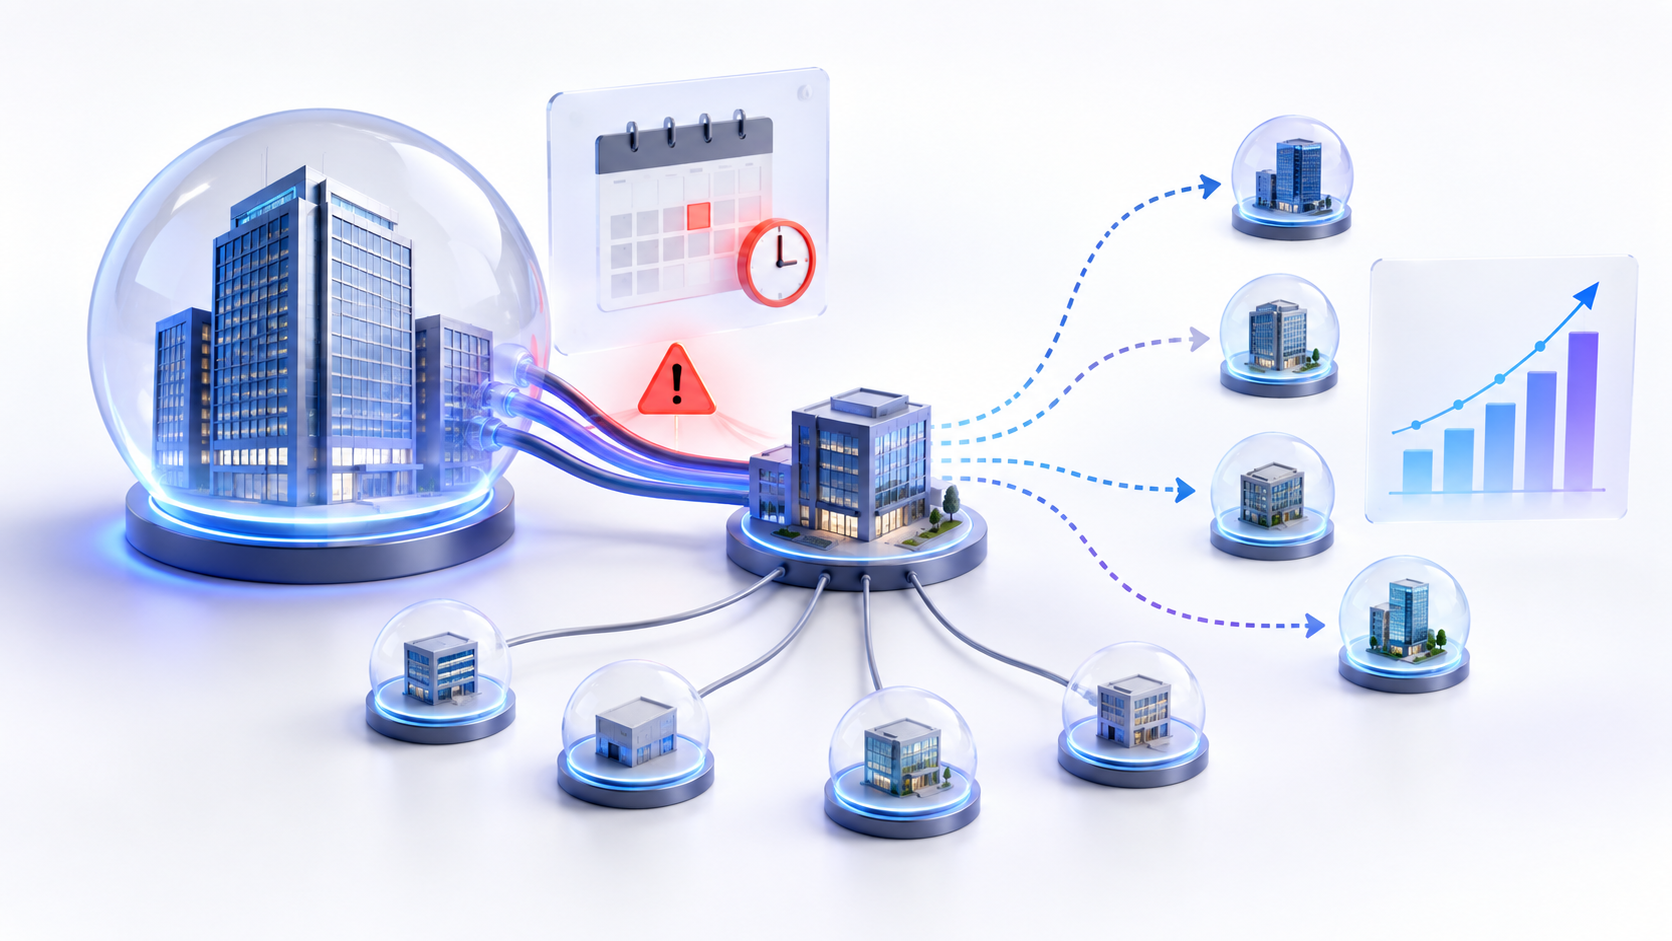
Draw two maps. The billing map links invoices, receivables, payment terms, and credit protection to legal counterparties. The demand map links products, aircraft platforms, distributors, and ultimate purchasing decisions. A credit insurer may reduce a default loss on the first map without replacing sales on the second. A parent guarantee can improve collection while leaving price pressure, cancellation, and dedicated-capacity risk unchanged.
应画两张图。开票图把发票、应收、付款条款和信用保护连接到法律交易对手;需求图把产品、飞机平台、分销商和最终采购决策连接起来。信用保险可能降低第一张图上的违约损失,却不能替代第二张图上的销量;母公司担保可以改善回款保障,但不会消除压价、取消和专用产能风险。
Worked map: AeroLume's concentration changes by lens案例地图:AeroLume 的集中度因视角而变
AeroLume Coatings is a fictional aviation-coating supplier; all facts and CU amounts are invented. Its 20X5 ledger has CU100m revenue and CU32m gross profit. Altair buys CU34m directly at 40% margin. A distributor buys CU16m, including CU9m for Altair platforms at 30% margin. Three other large customers contribute CU11m, CU8m, and CU6m; twenty customers contribute CU1.25m each.
AeroLume Coatings 是一家虚构的航空涂层供应商,所有日期、客户关系、合同与 CU 金额均为编制示例。虚构的 20X5 客户台账显示收入 CU100、毛利 CU32。Altair Airframe Group 直接采购 CU34,毛利率 40%;一家分销商采购 CU16,其中 CU9 的产品最终用于 Altair 飞机平台,毛利率 30%。其余三名大客户分别贡献 CU11、CU8 和 CU6,另外二十名小客户各贡献 CU1.25。
| Exposure lens | Invented fact or calculation | Concentration | What it reveals |
|---|---|---|---|
| Direct revenue, top-1 | 34 ÷ 100 | 34.0% | Named customer sales dependence |
| Direct revenue, top-5 | (34 + 16 + 11 + 8 + 6) ÷ 100 | 75.0% | Breadth of the reported customer ledger |
| Altair economic-demand revenue | (34 direct + 9 through channel) ÷ 100 | 43.0% | End-program exposure after avoiding double count |
| Altair economic-demand gross profit | (13.6 + 2.7) ÷ 32 | 50.9% | Margin loss can exceed revenue share |
| Altair legal receivable | 11 ÷ total receivables 25 | 44.0% | Direct counterparty collection exposure |
| Altair contract assets | 5 ÷ total contract assets 8 | 62.5% | Conditional, performed work exposure |
| Altair-linked backlog | 38 ÷ total backlog 80 | 47.5% | Future activity before testing cancellation |
| Altair-dedicated equipment | 18 ÷ total PP&E 60 | 30.0% | Capital redeployment exposure |
| 暴露视角 | 虚构事实或计算 | 集中度 | 揭示的问题 |
|---|---|---|---|
| 直接收入第一大客户 | 34÷100 | 34.0% | 按客户名称衡量的销售依赖 |
| 直接收入前五大客户 | (34+16+11+8+6)÷100 | 75.0% | 已报告客户台账的广度 |
| Altair 经济需求收入 | (直接 34+渠道 9)÷100 | 43.0% | 避免重复计算后的终端项目暴露 |
| Altair 经济需求毛利 | (13.6+2.7)÷32 | 50.9% | 毛利损失可能大于收入占比 |
| Altair 法律主体应收 | 11÷应收总额 25 | 44.0% | 直接交易对手收款暴露 |
| Altair 合同资产 | 5÷合同资产总额 8 | 62.5% | 已履约但仍附条件的暴露 |
| Altair 相关在手订单 | 38÷在手订单总额 80 | 47.5% | 检验取消权之前的未来活动 |
| Altair 专用设备 | 18÷固定资产总额 60 | 30.0% | 资本转用暴露 |
For decimal customer shares sᵢ, analytical HHI = Σsᵢ². The billing ledger gives 0.34² + 0.16² + 0.11² + 0.08² + 0.06² + 20 × 0.0125² = 0.1664, or 1,664 on a 0–10,000 scale. Regrouping CU9m of distributor demand to Altair creates shares of 43%, 11%, 8%, 7%, 6%, and twenty at 1.25%: HHI becomes 0.2150, or 2,150. This describes distribution; it is not an accounting measure, antitrust conclusion, or universal cutoff.
可选 HHI,必须明确标注若客户份额 sᵢ 用小数表示,分析用 HHI=Σsᵢ²。开票台账计算为 0.34²+0.16²+0.11²+0.08²+0.06²+20×0.0125²=0.1664,换成 0–10,000 刻度为 1,664。把分销商中 CU9 的终端需求归到 Altair 后,份额为 43%、11%、8%、7%、6% 和二十个 1.25%,HHI 为 0.2150,即 2,150。它只是描述性研究工具,不是会计指标、反垄断结论或通用风险界线。
Trace how dependence can become a loss追踪依赖如何传导为损失
| Contract or operating feature | Potential protection | Remaining exposure |
|---|---|---|
| Three-year master agreement | Relationship has a stated term | No protection if volumes are not committed |
| Termination for convenience | Notice can create planning time | Customer may exit without buying the forecast |
| Minimum purchase or take-or-pay | Can support volume or compensation | Enforceability, caps, exceptions, and credit still matter |
| Sole-source qualification | Switching may be slow for the customer | Supplier can also be locked into one platform and specification |
| Customer-funded tooling | Reduces supplier capital at risk | Ownership, return obligations, and unusable adjacent assets remain |
| Deposits, guarantees, or insurance | May reduce collection loss | Does not replace future sales or gross profit |
| 合同或经营特征 | 可能的保护 | 仍然存在的暴露 |
|---|---|---|
| 三年主协议 | 关系具有明确期限 | 若没有承诺采购量,期限本身并不保护收入 |
| 便利终止权 | 通知期提供准备时间 | 客户可以在不采购预测数量的情况下退出 |
| 最低采购或照付不议 | 可能支持销量或补偿 | 可执行性、上限、例外和信用仍然重要 |
| 独家供应认证 | 客户更换供应商可能较慢 | 供应商也可能被锁定在单一平台和规格上 |
| 客户出资工装 | 降低供应商资本风险 | 所有权、返还义务和相邻不可用资产仍存在 |
| 定金、担保或保险 | 可能降低收款损失 | 不能替代未来销售和毛利 |
The invented Altair contract has a three-year master term, but annual orders set volume, prices reset yearly, and either party can terminate future orders on 90 days' notice. These fictional facts make “three years remaining” a weak volume guarantee. Missing evidence includes cancellation compensation, alternate-customer qualification time, equipment conversion cost, order enforceability, and the distributor's ability to redirect product.
在虚构合同中,Altair 的主协议期限为三年,但采购量由年度订单确定、价格每年重设,任一方可提前 90 天终止未来订单。这些属于虚构已披露事实,因此“还剩三年”并不是有力的销量保证。缺失证据包括取消补偿、替代客户认证时间、设备改造成本、订单可执行性,以及分销商能否把产品转向其他平台。
Model the exit in revenue, margin, and cash分别用收入、毛利与现金建立退出情景
Baseline invented facts are CU100m revenue, CU32m gross profit, CU22m fixed operating costs, and CU10m EBIT. The scenario assumptions are not reported facts: Altair-linked demand of CU43m exits at the next year start; AeroLume wins CU12m of replacement sales at 30% gross margin; CU4m of fixed cost is avoidable within the year; and dedicated equipment with CU18m carrying value can recover CU4.5m. No probability is assigned.
虚构基准事实为收入 CU100、毛利 CU32、固定经营费用 CU22、息税前利润 CU10。下列情景假设并非披露事实:Altair 相关的 CU43 需求在下一年初退出;AeroLume 获得 CU12 替代销售,毛利率 30%;一年内可避免固定成本 CU4;账面价值 CU18 的专用设备可收回 CU4.5。本文不为情景分配发生概率。
| Bridge | Calculation | Scenario result |
|---|---|---|
| Revenue | 100 − 43 lost + 12 replacement | CU69m |
| Gross profit | 32 − 16.3 lost + (12 × 30%) | CU19.3m |
| Recurring fixed cost | 22 − 4 avoidable | CU18m |
| Recurring EBIT | 19.3 − 18 | CU1.3m |
| Equipment impairment assumption | 18 carrying value − 4.5 recoverable amount | CU13.5m noncash loss |
| Illustrative reported EBIT after impairment | 1.3 − 13.5 | −CU12.2m |
| 调节桥 | 计算 | 情景结果 |
|---|---|---|
| 收入 | 100−损失 43+替代 12 | CU69 |
| 毛利 | 32−损失 16.3+(12×30%) | CU19.3 |
| 经常性固定成本 | 22−可避免 4 | CU18 |
| 经常性息税前利润 | 19.3−18 | CU1.3 |
| 设备减值假设 | 账面价值 18−可收回金额 4.5 | 非现金损失 CU13.5 |
| 假设减值后的示例列报息税前利润 | 1.3−13.5 | −CU12.2 |
Assumptions: collect 85% of Altair's CU11m receivable and 60% of its CU5m contract asset; receive CU4.5m for equipment; pay CU3m exit costs, CU2m retooling, and CU4m replacement working capital. Selected net cash is (11 × 85%) + (5 × 60%) + 4.5 − 3 − 2 − 4 = CU7.85m. This is not total cash flow or a forecast because it excludes ordinary operations, timing, and financing. Insolvency requires different collection assumptions from voluntary exit.
单独建立现金回收桥假设层:Altair 的 CU11 应收中有 85% 在观察期内收回;CU5 合同资产中有 60% 以现金结算;设备出售收入 CU4.5;退出现金成本 CU3、改造 CU2、替代业务营运投入 CU4。所选项目净现金为(11×85%)+(5×60%)+4.5−3−2−4=CU7.85。它不是经营现金流总额或预测,因为没有包括日常收款、供应商付款、税务、具体时点和融资。客户自愿退出与客户破产需要使用不同的回款假设。
Test whether mitigation changes the exposed mechanism检验缓释措施是否真正改变暴露机制
- Revenue diversification works only if new customers do not depend on the same aircraft platform, distributor, procurement budget, or regulatory approval.
- Contract protection matters only to the extent minimum volumes, cancellation payments, price formulas, and remedies are enforceable and collectible.
- Capacity flexibility improves recovery when equipment, certifications, labor, and inventory can move to another qualified product without prohibitive cost or delay.
- Liquidity buys replacement time, but debt capacity does not restore lost margin and can add fixed claims.
- Relationship depth can lower near-term exit likelihood while increasing bargaining power over price, quality spending, inventory buffers, and payment terms.
- 只有当新客户不依赖同一飞机平台、分销商、采购预算或监管认证时,收入多元化才真正有效。
- 只有最低采购量、取消补偿、定价公式和救济措施可执行且可收回时,合同保护才有意义。
- 若设备、认证、人员和库存能够以可接受的成本与时间转向其他合格产品,产能灵活性才能改善回收。
- 流动性可以买到寻找替代客户的时间,但债务能力不能恢复损失毛利,还会增加固定偿付义务。
- 深厚关系可能降低近期退出概率,却也可能增强客户对价格、质量投入、安全库存和付款条款的议价能力。
Finish with the mechanism, not a color score. AeroLume's direct top-1 revenue share is 34%; regrouped Altair demand is 43%, gross-profit exposure 50.9%, and contract-asset exposure 62.5%. Invented volume protection is weak, while CU18m of dedicated equipment raises recovery risk. The outcome is not predetermined: renewal, replacement qualification, collection, and asset-conversion evidence can change it.
结论应针对风险机制,而不是给一个颜色评分。对 AeroLume 而言:已披露直接第一大客户收入集中度为 34%,穿透渠道后的 Altair 经济需求暴露为 43%,毛利暴露为 50.9%,合同资产暴露为 62.5%;虚构条款对采购量的保护较弱,CU18 专用设备又提高回收风险。但结果并非预先确定,续约、替代客户认证、实际收款和资产改造证据都可能显著改变判断。
Assemble a customer-exposure file map组装客户暴露文件地图
InfiniSynapse operates Stock Explained and publishes this page. Upload the complete annual and interim filings, segment and major-customer notes, revenue and contract-balance notes, credit-risk disclosures, receivable aging, backlog definitions, material customer contracts or exhibit summaries, fixed-asset notes, and management discussion. Ask the tool to locate customer references, preserve periods, units, entity names, and page citations, and place each amount under its correct denominator.
Use the result as an index. Verify every grouping, number, contract quotation, calculation, and page in the originals. Mark identities, margins, end-customer links, cancellation terms, and recoverability as missing when unsupported. The workflow cannot inspect undisclosed contracts or identify the ultimate economic customer from a distributor name alone.
InfiniSynapse 运营“一眼看懂这只股票”并发布本页。上传完整年报与中报、分部及主要客户附注、收入与合同余额附注、信用风险披露、应收账龄、在手订单定义、重大客户合同或附件摘要、固定资产附注和管理层讨论。要求工具定位所有客户引用,保留期间、单位、主体名称和页码,并把每个金额放到正确分母下。
输出只作为文件索引,不能直接充当集中度结论。每个客户归组、数字、合同引文、计算和来源页都要回到上传原件核验;文件不支持客户身份、毛利、终端客户联系、取消条款或资产可收回性时,必须标记为缺失。工作流不能查看未披露合同,也不能仅凭分销商名称确定最终经济客户。
Upload customer, contract, credit-risk, order, and asset disclosures; align the denominators and verify every grouping against the original pages.
上传客户、合同、信用风险、订单和资产披露,统一分母,并把每项客户归组回查到原始页面。
Open Stock Explained打开“一眼看懂这只股票”Questions after mapping customer concentration完成客户集中度地图后的具体问题
No. Under IFRS 8, 10% is a major-customer disclosure trigger, not a universal loss threshold. Risk also depends on margin, contracts, collections, replacement time, capacity flexibility, liquidity, and whether several named customers share one economic driver.
客户占比超过 10% 就一定过度集中吗?不一定。在 IFRS 8 下,10% 是主要客户披露触发点,不是通用损失界线。风险还取决于毛利、合同、回款、替代时间、产能灵活性、流动性,以及多个名义客户是否共享同一经济驱动。
Often, but document the basis. Common control, centralized procurement, shared budgets, guarantees, or one platform can support grouping. Separate decision-making and independent demand may support additional views. Keep legal credit exposure distinct from economic demand exposure.
同一客户集团的子公司应合并计算吗?通常需要,但应记录依据。共同控制、集中采购、共享预算、担保或同一平台可以支持归组;独立决策与独立需求也可能支持额外视角。法律信用暴露与经济需求暴露必须分开。
No. Revenue covers recognized activity in a period; backlog is a point-in-time operating measure whose definition and enforceability can differ. Read cancellation, funding, scope-change, and delivery terms before treating backlog as future revenue.
在手订单集中度等同于收入集中度吗?不等同。收入衡量一个期间已确认的活动;在手订单是时点经营指标,其定义与可执行性可能不同。把它当作未来收入前,应阅读取消、资金、范围变更和交付条款。
A large customer may buy higher-margin products, use a low-service channel, or absorb fixed production capacity efficiently. It may also receive discounts that lower margin. Reconcile customer revenue with directly attributable and allocated costs, and label estimates when customer margin is not disclosed.
为什么毛利集中度可能高于收入集中度?大客户可能采购高毛利产品、使用低服务成本渠道,或高效吸收固定产能;也可能因折扣而毛利更低。应把客户收入与直接归属和分摊成本勾稽,未披露客户毛利时必须把结果标记为估算。
No. A stated term may coexist with no minimum volume, annual repricing, termination rights, performance conditions, or weak remedies. Read purchase commitments, cancellation compensation, enforceability, customer credit, and what happens to dedicated assets.
长期合同能消除客户集中度风险吗?不能。明确期限仍可能与无最低采购量、年度重定价、终止权、履约条件或有限救济并存。应阅读采购承诺、取消补偿、可执行性、客户信用及专用资产的后续处理。
No. The customer-share HHI summarizes distribution under a chosen grouping; it does not estimate exit probability or loss severity. Its result changes with channel look-through and incomplete disclosure. Use it to compare clearly defined views, then test contracts and economics directly.
客户 HHI 较高能证明客户将会退出吗?不能。客户份额 HHI 只是在选定归组下概括分布,并不估计退出概率或损失严重程度;渠道穿透和披露不完整都会改变结果。它适合比较定义清楚的视角,最终仍要直接检验合同与经济性。
Primary sources and scope boundary第一手来源与适用边界
IFRS 8 informs major-customer grouping; IFRS 7 covers financial-instrument risk; IFRS 15 distinguishes receivables and contract balances. Form 10-K and Regulation S-K guide U.S. business and material-risk evidence. Requirements vary by framework, issuer, materiality, and period, so use the complete filing.
AeroLume, Altair, their contracts, and every amount are fictional. The HHI and exit bridges are analytical illustrations, not accounting measures, probability estimates, impairment tests, audits, or individualized investment recommendations. Missing customer identity or contract detail must remain unknown rather than be inferred as fact.
IFRS 8 为主要客户与共同控制归组提供背景;IFRS 7 涉及金融工具及信用风险暴露;IFRS 15 说明应收与合同余额的区别。Form 10-K 与 Regulation S-K 指引美国公司业务和重大风险证据的披露位置。要求会随报告框架、发行人身份、重要性和期间变化,因此必须使用公司的完整适用文件。
AeroLume、Altair、双方合同及全部金额均为虚构。HHI 与退出调节桥只是分析示例,不是会计指标、概率估计、减值测试、审计或个性化投资建议。客户身份或合同细节缺失时,应保持未知,不能把推测写成事实。
- IFRS Foundation — IFRS 8 Operating Segments, paragraph 34
- IFRS Foundation — IFRS 7 Financial Instruments: Disclosures
- IFRS Foundation — IFRS 15 Revenue from Contracts with Customers
- U.S. Securities and Exchange Commission — Form 10-K
- U.S. Securities and Exchange Commission — Regulation S-K Items 101 and 105 Compliance Guide