Name the margin before explaining the decline解释下降之前,先说清是哪一种利润率
Calculate three margins for the same period: gross profit ÷ revenue, operating income ÷ revenue, and net income attributable to the relevant shareholders ÷ revenue. Recalculate from filed statements and check for recasts. A gross-margin decline points toward price, mix, materials, labor, freight, yield, and utilization. Stable gross margin with lower operating margin points toward selling, administrative, research, launch, restructuring, or share-based compensation expense. A larger net-margin decline directs attention to interest, taxes, disposals, impairments, and other non-operating items. Bridge profit dollars while separately reconciling revenue. Label reported facts, calculations, assumptions, and judgments. Then test whether the drivers fit temporary investment, cyclical pressure, or structural deterioration. Evidence and subsequent results determine the label, not an adjective or adjusted metric.
先对同一可比期间重算三条公式:毛利率=毛利÷收入;营业利润率=营业利润÷收入;净利率=归属于相关股东的净利润÷收入,并核对公司是否重述了比较期。毛利率下降首先指向价格、产品或客户组合、材料、人工、运费、良率与产能利用率;毛利率稳定而营业利润率下降,则更多指向销售、管理、研发、启动、重组或股份支付费用;净利率下降幅度更大时,要继续检查利息、税、处置、减值与其他非经营项目。随后既要桥接利润金额,也要单独调节收入分母,不能只比较百分比。公司报告事实、算术、分析假设与判断必须分栏。最后再检验驱动属于暂时投入、周期压力还是结构性恶化;分类要由证据与后续经营结果决定,而不是由管理层形容词或单一调整指标决定。
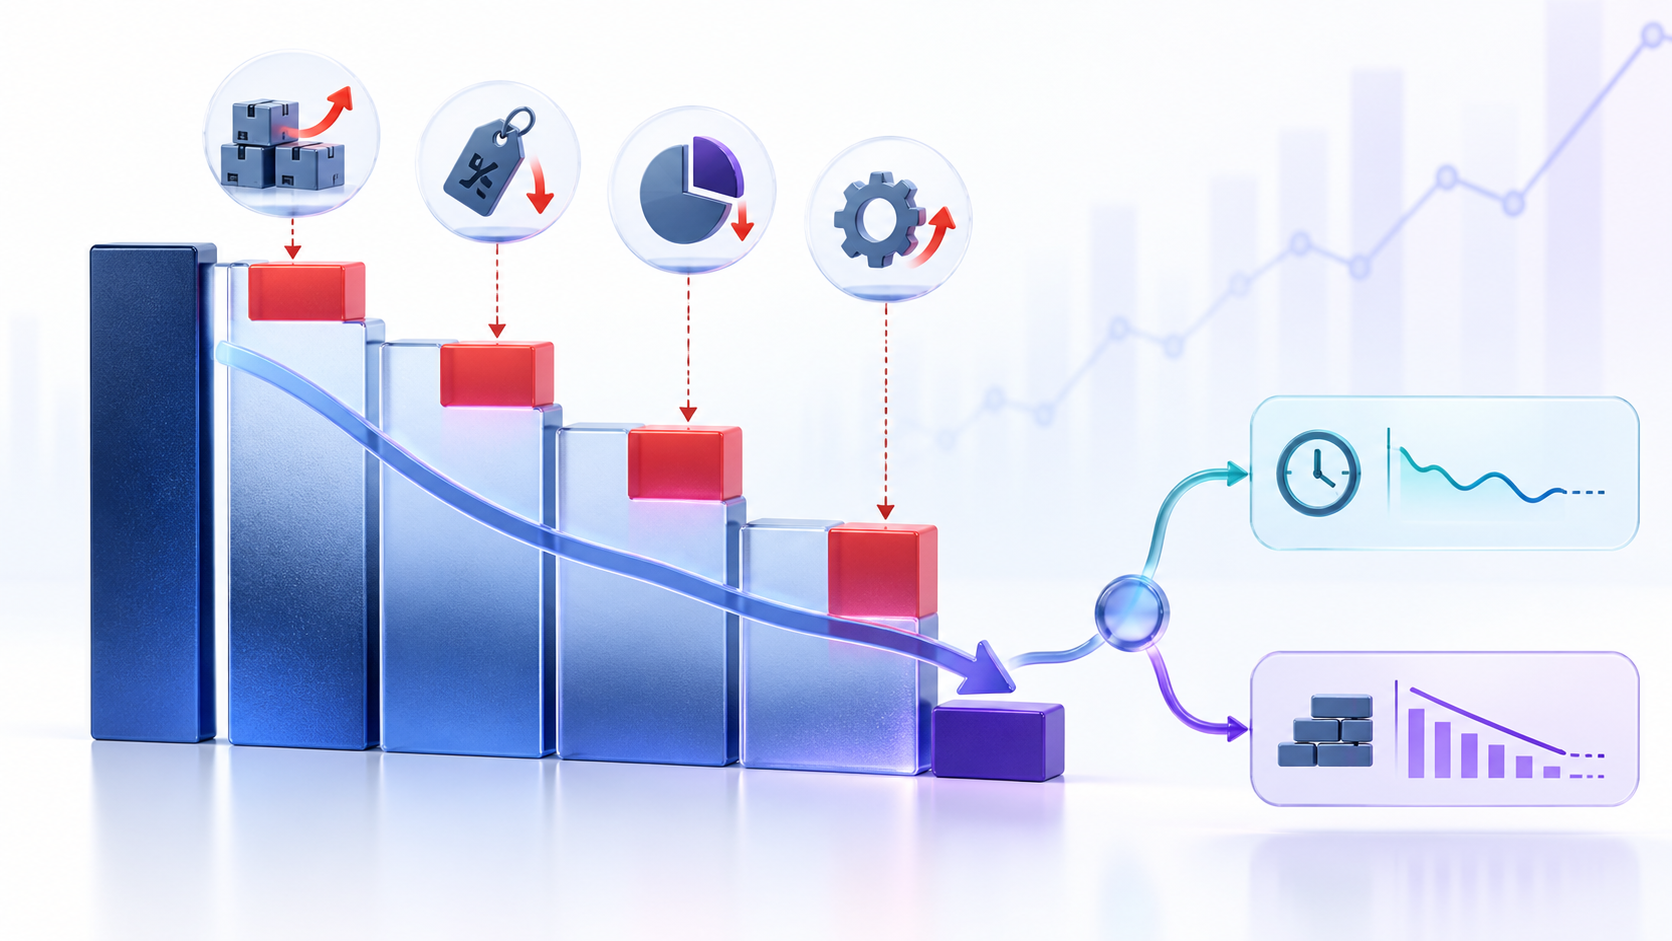
Locate the leak in the three-margin waterfall在三层利润率瀑布中定位漏点
| Observed pattern | First questions | What it does not prove |
|---|---|---|
| Gross margin falls | Did realized price, mix, input cost, yield, freight, or utilization change? | Pricing power disappeared or the product is permanently worse |
| Gross margin holds; operating margin falls | Did growth investment, overhead, restructuring, or share-based pay rise? | All spending is wasteful or all spending will earn a return |
| Operating margin holds; net margin falls | Did interest burden, tax rate, minority attribution, or non-operating loss change? | The core operation deteriorated |
| All three fall | Is one operating driver flowing through every subtotal, with financing or tax adding pressure? | One cause explains the entire movement |
| 观察模式 | 首先追问 | 不能据此证明 |
|---|---|---|
| 毛利率下降 | 实现价格、组合、投入成本、良率、运费或利用率是否变化? | 定价权已经消失,或产品永久变差 |
| 毛利率稳定、营业利润率下降 | 增长投入、管理费用、重组或股份支付是否上升? | 所有支出都浪费,或所有投入都必有回报 |
| 营业利润率稳定、净利率下降 | 利息负担、税率、少数股东归属或非经营损失是否变化? | 核心经营已经恶化 |
| 三者均下降 | 一个经营驱动是否贯穿各小计,融资或税项又是否加压? | 单一原因足以解释全部变化 |
Use presented subtotals where available and read accounting policies before constructing missing ones. Gross profit may not appear, and expenses may be classified by function or nature. Confirm whether revenue is net of rebates and returns, where depreciation sits, and whether restructuring or impairment is within operating income. Separate continuing from discontinued operations and identify noncontrolling-interest attribution before calculating common-shareholder net margin.
优先使用公司实际列报的小计,缺少某个小计时,先读会计政策再自行构造。并非所有行业都会列示“毛利”,费用也可能按职能或性质分类。要确认收入是否已扣返利和退货,折旧位于销售成本还是经营费用,重组或减值是否计入营业利润。持续经营与终止经营必须分开;以普通股东口径计算净利率前,还要识别归属于非控股权益的利润。
A move from 30% to 25% is a 5-percentage-point decline. Relative to the starting margin, it is 16.7%: (25% ÷ 30%) − 1. Label the measure used.
百分点不等于百分比变化利润率从 30% 降至 25%,下降 5 个百分点;相对于起始利润率,降幅为 16.7%,即 25%÷30%−1。两种表达都可能有用,但回答不同问题,必须清楚标注。
Rebuild both periods before assigning a cause归因之前,先重建两个期间的利润瀑布
PineFold Packaging is an invented paper-packaging producer. Figures are fictional US-dollar teaching data for 20X4 and 20X5, in millions except tonnes and percentages. Assume no discontinued operation, noncontrolling interest, or preferred dividend. Tax expense equals 25% of pretax income in both periods.
虚构公司与简化假设PineFold Packaging 是虚构纸质包装生产商。下列数字均为 20X4 与 20X5 的美元教学数据,除吨数与百分比外,单位均为百万美元。简化假设:没有终止经营、非控股权益或优先股股利,净利润全部归属于普通股东;两期所得税费用均为税前利润的 25%,仅为让桥接易于复算。
| Income-statement line | 20X4 reported | 20X5 reported | Calculation or reading |
|---|---|---|---|
| Revenue / sales volume | $500 / 250,000 tonnes | $540 / 265,000 tonnes | Revenue +8.0%; volume +6.0% |
| Cost of sales | $350 | $405 | Includes fiber, energy, labor, conversion, freight, and plant depreciation |
| Gross profit / margin | $150 / 30.0% | $135 / 25.0% | $135 ÷ $540; down 5.0 percentage points |
| Operating expenses | $75 | $86 | 15.0% versus 15.9% of revenue |
| Operating income / margin | $75 / 15.0% | $49 / 9.1% | $49 ÷ $540; down 5.9 percentage points |
| Interest expense | $12 | $20 | 2.4% versus 3.7% of revenue |
| Non-operating disposal loss | $0 | $9 | 20X5-only reported item |
| Pretax income / tax expense | $63 / $15.75 | $20 / $5 | Reported tax rate assumed at 25% |
| Net income / margin | $47.25 / 9.45% | $15 / 2.78% | Down 6.67 percentage points |
| 利润表项目 | 20X4 报告数 | 20X5 报告数 | 计算或解读 |
|---|---|---|---|
| 收入 / 销量 | 5.00 亿 / 25 万吨 | 5.40 亿 / 26.5 万吨 | 收入 +8.0%;销量 +6.0% |
| 销售成本 | 3.50 亿 | 4.05 亿 | 包含纤维、能源、人工、加工、运输与工厂折旧 |
| 毛利 / 毛利率 | 1.50 亿 / 30.0% | 1.35 亿 / 25.0% | 1.35 亿÷5.40 亿;下降 5.0 个百分点 |
| 经营费用 | 7,500 万 | 8,600 万 | 占收入 15.0% 与 15.9% |
| 营业利润 / 营业利润率 | 7,500 万 / 15.0% | 4,900 万 / 9.1% | 4,900 万÷5.40 亿;下降 5.9 个百分点 |
| 利息费用 | 1,200 万 | 2,000 万 | 占收入 2.4% 与 3.7% |
| 非经营性处置损失 | 0 | 900 万 | 仅在 20X5 报告 |
| 税前利润 / 所得税费用 | 6,300 万 / 1,575 万 | 2,000 万 / 500 万 | 简化报告税率均为 25% |
| 净利润 / 净利率 | 4,725 万 / 9.45% | 1,500 万 / 2.78% | 下降 6.67 个百分点 |
Revenue grew, yet gross profit fell $15m because cost of sales rose faster. Operating expense added $11m, producing a $26m operating-income decline. Interest rose $8m and the disposal loss added $9m below operations, so pretax income fell $43m. Tax expense fell $10.75m with lower pretax income; that mechanical cushion is not improvement. Net income fell $32.25m. The waterfall exposes three separate leak points.
顺序很重要。收入增长,但销售成本增速更快,毛利反而减少 1,500 万;经营费用又增加 1,100 万,使营业利润减少 2,600 万。营业利润以下,利息增加 800 万,处置损失增加 900 万,因此税前利润共减少 4,300 万。所得税费用因税前利润下降而减少 1,075 万,这种机械缓冲并非经营改善。最终净利润减少 3,225 万。用瀑布逐层核对,才能避免“利润率承压”一句话掩盖三个不同漏点。
Bridge profit dollars while controlling the revenue denominator控制收入分母,同时桥接利润金额
| 20X4 gross profit to 20X5 | Effect on gross profit | Evidence status |
|---|---|---|
| Starting gross profit | $150m | Reported fact |
| Higher volume at prior contribution pattern | +$8m | Analyst calculation |
| Contract price increases | +$18m | Illustrative management disaggregation |
| Shift toward lower-margin export cartons | −$10m | Illustrative management disaggregation |
| Higher energy cost | −$13m | Illustrative management disaggregation |
| Higher recycled-fiber cost | −$7m | Illustrative management disaggregation |
| Expansion shutdown, scrap, and low utilization | −$11m | Illustrative management disaggregation |
| Ending gross profit | $135m | Reported fact; bridge closes |
| 20X4 毛利到 20X5 | 对毛利影响 | 证据状态 |
|---|---|---|
| 起始毛利 | 1.50 亿 | 报告事实 |
| 按此前贡献模式计算的销量增加 | +800 万 | 分析者计算 |
| 合同提价 | +1,800 万 | 虚构管理层拆分 |
| 组合转向低毛利出口纸箱 | −1,000 万 | 虚构管理层拆分 |
| 能源成本上升 | −1,300 万 | 虚构管理层拆分 |
| 再生纤维成本上升 | −700 万 | 虚构管理层拆分 |
| 扩产停机、废料与低利用率 | −1,100 万 | 虚构管理层拆分 |
| 期末毛利 | 1.35 亿 | 报告事实;桥接闭合 |
The bridge closes: $150m + $8m + $18m − $10m − $13m − $7m − $11m = $135m. It does not explain revenue. The separate illustrative revenue bridge is $500m + $30m volume + $20m pricing − $10m mix = $540m. Here mix is a revenue effect; the −$10m gross-profit mix is a profit effect. Do not interchange them. When disclosure is only qualitative, label dollar allocations as assumptions or retain an unexplained residual.
桥接必须回到报告总额:1.50 亿+800 万+1,800 万−1,000 万−1,300 万−700 万−1,100 万=1.35 亿。但这条桥本身并没有解释收入分母。PineFold 另有一条虚构收入桥:5.00 亿+销量贡献 3,000 万+合同提价 2,000 万−组合影响 1,000 万=5.40 亿。收入桥的“组合”是收入影响,毛利桥的 −1,000 万则是利润影响;标签相同不代表可以互换。若公司只定性描述原因,金额分配必须标为分析假设,或保留无法解释的残差。
Separate list price, escalators, rebates, surcharges, and shipment timing. Volume can dilute margin when incremental orders contribute less or require overtime.
价格与销量拆开标价变化、合同调价、返利、附加费与出货时点。若增量订单贡献较低或需要加班,销量增加反而可能稀释利润率。
Separate product, geography, and customer mix from fiber, energy, labor, and freight. A favorable average price can coexist with adverse mix.
组合与投入成本把产品、地区与客户组合和纤维、能源、人工、运输分别衡量。平均实现价格改善也可能与不利利润组合同时存在。
Track downtime, saleable yield, utilization, maintenance, commissioning, and overhead absorption. Separate cost-of-sales items from operating expenses.
产能与费用跟踪停机、合格品率、利用率、维护、投产调试与固定费用吸收,再区分计入销售成本和经营费用的项目。
Use adjustments as a transparent second lens, not a replacement把调整当作透明的第二视角,而不是替代报告数
Suppose PineFold identifies $11m of shutdown and ramp cost in cost of sales and $4m of restructuring in operating expense. Reported 20X5 operating income remains $49m. Adding both back in an analyst scenario produces $64m and an 11.85% margin: ($49m + $11m + $4m) ÷ $540m. That remains below 20X4’s reported 15.0%. The scenario isolates a question; it neither rewrites GAAP nor proves the expenses vanish.
假设 PineFold 披露销售成本中包含 1,100 万停机与爬坡成本,经营费用中包含 400 万重组费用。20X5 报告营业利润仍是 4,900 万。分析者若在情景中把两项加回,可得到 6,400 万及 11.85% 营业利润率,即(4,900 万+1,100 万+400 万)÷5.40 亿。它仍低于 20X4 报告的 15.0%。这个情景只是在隔离问题,不能改写 GAAP,不能证明费用必然消失,也不能确立经常性利润率。
| Adjustment test | Pass condition | Warning |
|---|---|---|
| Directly traceable | Amount and statement location reconcile to the source | A rounded management comment is not a complete bridge |
| Unusual in fact | Nature, timing, and recurrence history support separate analysis | “One-time” restructuring that repeats is economically recurring |
| Symmetric | Comparable gains and losses receive consistent treatment | Removing losses but retaining related benefits biases the result |
| Tax-consistent | Net-income adjustments show the related tax effect separately | Pretax and after-tax amounts cannot be mixed |
| Definition-stable | Current and prior periods use the same definition or are recast | A changed non-GAAP definition can manufacture improvement |
| 调整检验 | 通过条件 | 警示 |
|---|---|---|
| 可直接追溯 | 金额与报表位置能和原始来源调节 | 管理层四舍五入的评论不是完整桥接 |
| 事实上异常 | 性质、时点与复发历史支持单独分析 | 反复出现的“一次性”重组在经济上具有经常性 |
| 处理对称 | 可比收益与损失得到一致处理 | 剔除损失却保留相关收益会造成偏差 |
| 税务一致 | 净利润调整单列相关税务影响 | 税前金额与税后金额不能混合 |
| 定义稳定 | 本期和前期使用同一定义或已重列 | 改变非 GAAP 定义可能制造改善 |
Keep three columns: reported operating income, company-adjusted measure with reconciliation, and analyst scenario with explicit choices. Share-based compensation is an expense even when noncash; an exclusion also requires a dilution check. A disposal loss may explain why net margin fell further, yet proceeds, tax effects, and recurring asset churn still matter. Never combine unrelated adjustments into vague normalized margin.
保留三列:报告营业利润、带调节表的公司调整指标,以及明确选择的分析情景。股份支付即使非现金仍是费用;分析者可以展示剔除版本,但必须同时检查稀释。处置损失可能解释净利率为何比营业利润率下降更多,但处置所得、税务影响与是否反复处置资产仍然重要。不能把互不相关的调整揉成含糊的“正常化利润率”。
Classify the pressure only after defining a reversal test先定义反转检验,再给压力分类
| Possible classification | PineFold hypothesis | Evidence for recovery | Evidence against |
|---|---|---|---|
| Temporary execution | Expansion outage and scrap fade after commissioning | Uptime and saleable yield rise; conversion cost per tonne falls without deferred maintenance | Downtime, claims, scrap, or overtime persists |
| Cyclical input pressure | Energy and fiber rose faster than contractual price pass-through | Input benchmark and realized price spread stabilizes as contractual lags expire | Spread stays compressed after inputs ease or escalators take effect |
| Deliberate investment | Training and commercial expense build usable capacity and orders | Qualified order volume, utilization, and incremental operating profit follow | Expense continues without throughput, retention, or contribution improvement |
| Structural deterioration | Low-margin mix and weak bargaining power become durable | Renewals recover economics without losing core customers | Discounting, adverse mix, churn, or competitor share gains persist |
| Financing overlay | Expansion debt raises interest faster than operating profit | Debt peaks, interest coverage recovers, and funding matches asset life | Borrowing funds recurring shortfalls or refinancing raises the burden |
| 可能分类 | PineFold 假说 | 恢复证据 | 反证 |
|---|---|---|---|
| 暂时执行问题 | 扩产停机与废料在投产后消退 | 开机率和合格品率上升,单位加工成本下降且未延后维护 | 停机、索赔、废料或加班持续 |
| 周期性投入压力 | 能源和纤维涨幅快于合同价格传导 | 合同滞后结束后,投入基准与实现价格之间的价差稳定 | 投入成本回落或调价生效后,价差仍受压 |
| 主动投入 | 培训和商业费用建立可用产能与订单 | 合格订单、利用率与增量营业利润随后出现 | 费用持续,但吞吐、留存或贡献没有改善 |
| 结构性恶化 | 低毛利组合与弱议价能力变得持久 | 续约恢复经济性且未丢失核心客户 | 折价、不利组合、流失或竞争对手份额提升持续 |
| 融资叠加 | 扩产债务使利息增速高于营业利润 | 债务见顶、利息保障恢复且融资期限匹配资产寿命 | 借款用于填补经常性缺口,或再融资继续加重负担 |
Categories can overlap. A cyclical energy shock may expose structural inability to pass price; a temporary shutdown may create lasting mix loss. Set periods before judging: plant metrics can improve monthly, contracts reset quarterly, and debt may fall only after the working-capital season. For PineFold, the reported decline is certain; its timing, cyclical, and structural proportions remain hypotheses until plant, contract, segment, and cash evidence converge.
这些类别可以重叠。周期性能源冲击可能暴露结构性的价格传导无力;暂时停机也可能造成长期客户组合损失。判断前先设定时间尺度:工厂指标可能按月改善,合同价格可能按季重设,债务可能要等营运资金旺季结束才下降。缺失证据应写进结论。对 PineFold 而言,报告利润率下降是确定事实;多少属于时点、周期或结构,仍是待工厂、合同、分部与现金证据共同验证的假说。
Demand a recovery chain, not one better quarter要求一条恢复证据链,而不是只看一个好季度
Saleable yield, downtime, energy per tonne, scrap, claims, and utilization improve together. Gains caused by skipped maintenance are not clean recovery.
经营证明合格品率、停机小时、每吨能源、废料、客户索赔与产能利用率共同改善。靠跳过维护获得的利用率提升不是干净恢复。
Realized price and product or segment contribution confirm pass-through without severe volume or retention damage.
商业证明每吨实现价格以及分产品或分部贡献,确认合同传导有效,同时没有严重损害销量或客户留存。
Gross profit, reported operating margin, cash, debt, and interest burden align with the claimed recovery.
财务证明毛利金额、报告营业利润率、现金生成、债务与利息负担和声称的经营恢复方向一致。
Definitions stay stable, residual headwinds are quantified, adjustments reconcile, and setbacks receive specific discussion.
披露证明公司保持定义稳定,量化剩余逆风,调节调整项目,并像讨论有利变化一样具体地讨论挫折。
Write a dated recovery test: “The temporary-ramp interpretation gains support if, over two comparable quarters, saleable yield exceeds its pre-outage range, gross margin improves without new exclusions, inventory does not accumulate, and reported operating cash flow supports debt reduction.” This is an analyst test, not guidance. If price rises while tonnes and retention fall, or adjusted margin recovers while reported costs and debt stay elevated, remain unresolved. One subtotal cannot validate the chain.
写出带日期的恢复检验。例如:“若未来两个可比季度的合格品率超过停机前区间,毛利率在不增加新剔除项目的情况下改善,库存不堆积,且报告经营现金流支持降债,则暂时爬坡解释得到更多支持。”这是分析者检验,不是 PineFold 指引。若价格上升但销量与客户留存下降,或调整后利润率恢复而报告成本与债务仍高企,结论仍应保持未决。单个有利小计不能验证整条链。
PineFold’s 20X5 data establish broad margin compression. They suggest that plant disruption, inputs, mix, operating expense, interest, and a disposal loss all contributed. They do not yet establish which operating pressures are temporary or what margin will recover to.
与证据相称的结论PineFold 的 20X5 数据确认了广泛的利润率收缩,并表明工厂扰动、投入成本、组合、经营费用、利息与处置损失均有贡献;但它们尚不能确定哪些经营压力只是暂时的,也不能确定利润率将恢复到什么水平。
Build the bridge from the filed lines and notes从报告行项目与附注建立桥接
Upload complete reports for both periods, not income-statement screenshots. Include revenue and cost policies; segment tables; expense, restructuring, impairment, share-based compensation, debt, interest, and tax notes; capacity disclosures; MD&A; releases; and non-GAAP reconciliations. State periods, currency, units, continuing-operation scope, and whether quarterly numbers are standalone or year-to-date. Request each number with document, page, table, row, period, and sign.
Request three reported margins, a revenue bridge, gross-profit and operating-expense bridges, and a below-operating-income waterfall. Separate reported fact, calculation, company explanation, analyst assumption, judgment, and residual. Place company-adjusted and analyst-adjusted margins beside reported margins. Open every cited page in the uploaded originals, re-add each bridge, recompute percentage-point changes, inspect definition changes, and trace tax effects. Reject unlocated driver amounts unless labeled as assumptions. The source documents remain authoritative.
上传两个期间的完整年报与季报,而不是孤立的利润表截图。材料应包含收入确认与成本政策、分部表、费用、重组、减值、股份支付、债务、利息与所得税附注,物业和产能披露、MD&A、业绩稿以及全部公司非 GAAP 调节表。说明财政期间、币种、单位、持续经营范围,以及季度数字是单季还是年初至今。要求 Stock Explained 为每个数字记录准确文件、页码、表格、行、期间与正负号。
要求输出三种报告利润率、收入分母桥、毛利桥、经营费用桥,以及营业利润以下的独立瀑布;报告事实、计算、公司解释、分析假设、判断与无法解释残差必须分列。公司调整利润率和分析者调整利润率只能放在报告利润率旁边,不能替代后者。随后逐页打开上传原件中的引用,重新加总每条桥,复算百分点变化,检查定义变更并追踪税务影响。无法定位或无法标为假设的驱动金额必须拒绝。工具可以组织证据,原始文件才是权威。
Upload both periods, the relevant notes, and reconciliations; calculate each margin layer and verify every driver against the original files.
上传两个期间、相关附注与调节表,计算每一层利润率,并用原始文件核验每个驱动。
Open Stock Explained打开“一眼看懂这只股票”Questions after the first margin bridge完成第一条利润率桥后的问题
Yes. PineFold’s revenue rises 8% while gross margin falls from 30% to 25%. Price or volume can lift revenue while adverse mix, inputs, utilization, or expense grows faster. Bridge profit dollars and revenue separately.
收入增长和利润率下降可以同时发生吗?可以。PineFold 收入增长 8%,毛利率却从 30% 降至 25%。价格、销量或收购可以抬高收入,而不利组合、投入、利用率或费用增速可能更快。利润金额与收入分母要分别桥接。
There is no universal ranking. Gross-margin pressure can reveal weak unit economics, operating pressure may reflect waste or investment, and net-margin pressure may be financing or tax driven. Materiality, duration, cause, and reversibility matter more than the subtotal name.
哪一种利润率下降最值得担心?没有统一排序。毛利率压力可能暴露单位经济问题,营业利润率压力可能来自浪费或主动投入,净利率压力也可能由融资或税务驱动。重要性、持续时间、原因与可逆性比小计名称更关键。
Show an exclusion only as a labeled second lens. Reconcile its amount and location, test recurrence, and retain reported margin. PineFold’s analyst-adjusted 11.85% remains a scenario, not a replacement for reported 9.1%.
扩产停机成本应该剔除吗?只能把剔除版本作为标明口径的第二视角。调节金额与位置,检查类似成本是否复发,并保留报告利润率。PineFold 的分析调整营业利润率 11.85% 仍是情景,不能替代报告的 9.1%。
Items below operating income can add pressure. In the example, interest expense rises and a disposal loss appears. Attribution, taxes, impairments, foreign exchange, or debt-extinguishment effects can also matter, depending on presentation and facts.
为什么净利率可能比营业利润率下降更多?营业利润以下项目可能继续加压。案例中利息费用上升,并出现处置损失。根据列报和事实,利润归属、税、减值、汇兑或债务清偿影响也可能重要。
No fixed count proves recovery. Match the horizon to contract resets, seasonality, and the operating change. Require the driver, reported margin, cash, and balance-sheet effects to align across comparable periods.
多少个季度才能证明利润率已经恢复?没有固定季度数能自动证明恢复。时间范围应匹配合同重设、季节性与经营变化,并要求驱动、报告利润率、现金后果与资产负债表影响在可比期间方向一致,而不是接受一个有利季度。
Primary references for the margin investigation利润率调查的一手参考资料
These sources support statement structure, MD&A, expense disaggregation, filing context, and non-GAAP controls. Presentation, tax treatment, segment measures, and effective requirements depend on issuer, jurisdiction, period, and facts. They do not validate fictional PineFold data.
This page is educational, not accounting, legal, tax, forecasting, market-data, or individualized investment advice. A margin test alone does not establish business value, future results, or a trading action.
以上来源支持利润表结构、MD&A 分析、费用拆分、申报背景与非 GAAP 控制。准确列报、税务处理、分部指标与生效会计要求取决于发行人、司法辖区、期间和事实;它们不验证虚构 PineFold 数据或分析者分配。
本页仅供学习,不构成会计、法律、税务、预测、市场数据或个性化投资建议。利润率下降或恢复检验本身不能确立企业价值、未来结果或交易行动。