Start with the closing equation, not a cash score先看闭合等式,不要先给现金打分
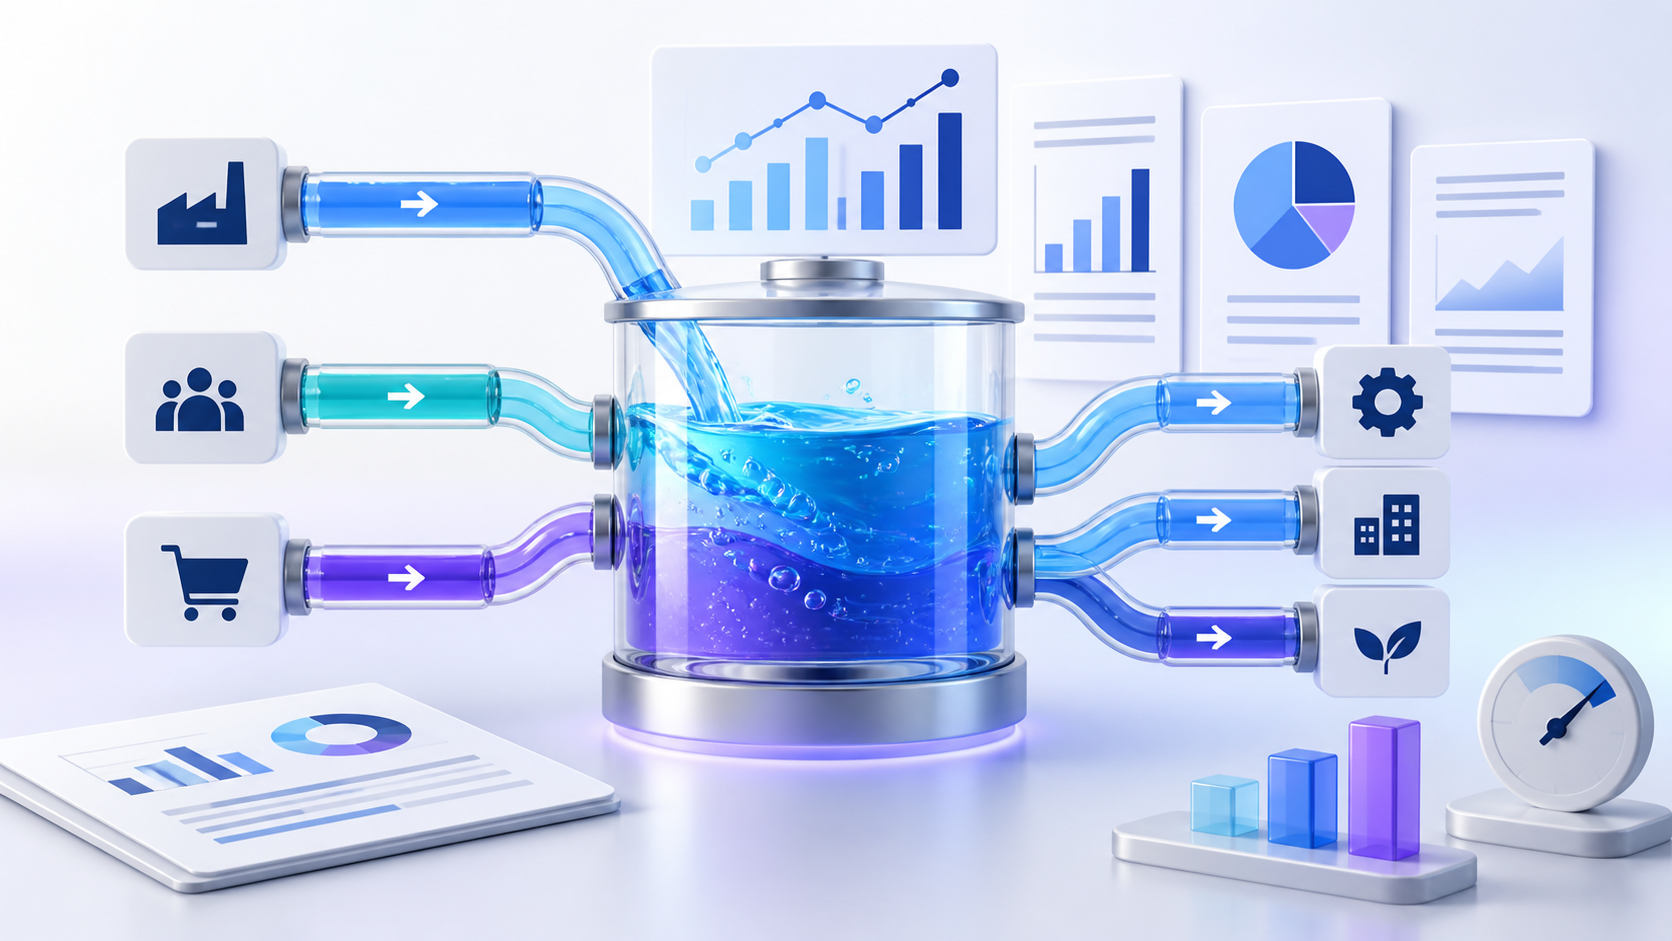
The statement of cash flows explains the change in cash and cash equivalents during a stated period. Operating activities show cash connected to the principal revenue-producing business and other activities not classified as investing or financing. Investing covers cash used for or received from long-term assets and investments; financing covers changes in borrowings and contributed equity. Under the indirect method, profit is adjusted for noncash items, operating accruals, and items whose cash effects belong elsewhere. Noncash investing or financing transactions are excluded from cash-flow rows and disclosed separately. The ending total must reconcile to the applicable cash, cash-equivalent, and restricted-cash presentation.
现金流量表解释明确期间内现金及现金等价物如何变化。经营活动展示与主要创收业务有关、且未被分类为投资或融资的现金;投资活动展示长期资产与投资带来的现金支出和收入;融资活动展示借款与投入权益规模和构成的现金变化。间接法从利润出发,调节非现金项目、经营性应计差异,以及现金影响被归入其他类别的项目。完全不涉及现金的投资或融资交易不会进入现金流项目,而是在其他位置单独披露。期末总额必须与适用的现金、现金等价物和受限现金列报相调节。
Draw the cash perimeter before routing movement归类流动之前先画现金边界
The controlling equation is: Beginning cash within statement scope + operating cash flow + investing cash flow + financing cash flow + exchange-rate effect, if any = ending cash within statement scope. “Within scope” matters. Cash generally includes cash on hand and demand deposits; cash equivalents are short-term, highly liquid instruments readily convertible to known cash amounts with insignificant value-change risk under the applicable policy. A marketable security is not automatically a cash equivalent.
控制整张表的等式是:报表范围内期初现金 + 经营现金流 + 投资现金流 + 融资现金流 + 汇率影响(如有)= 报表范围内期末现金。“报表范围内”非常重要。现金通常包括库存现金与活期存款;现金等价物则是在适用政策下期限短、流动性高、可随时转换为已知现金金额且价值变动风险很小的工具。可交易证券不会自动成为现金等价物。
Read the policy, components, overdraft treatment, and reconciliation to the balance sheet. The label alone does not settle the boundary.
现金及现金等价物阅读政策、构成、透支处理和与资产负债表的调节;仅凭项目名称无法确定边界。
Restrictions can affect balance-sheet location and availability. Under the U.S. GAAP assumption used here, beginning and ending cash-flow totals include amounts generally described as restricted cash, with a reconciliation when lines differ.
受限现金限制会影响资产负债表位置与可用性。本案例采用美国 GAAP 假设,现金流量表期初与期末总额包含通常称为受限现金的金额;若资产负债表项目不同,需要调节。
Moving money between accounts already inside the defined cash total changes composition, not total cash flow. A transfer into restricted cash may reduce availability without creating an external receipt or payment.
内部转移在已纳入定义现金总额的账户之间转移资金,只改变构成,不改变总现金流。转入受限现金可能降低可用性,却不形成对外收付。
The balance sheet shows cash at a date; the cash flow statement explains movement over a period. Comparing an ending cash balance with a full-year cash-flow subtotal without aligning dates, scope, and currency mixes a stock with a flow.
余额不是流量资产负债表展示某一日期的现金余额,现金流量表解释一段期间内的现金运动。若日期、范围和币种尚未对齐,就把期末余额与全年现金流小计比较,等于混合时点量与期间量。
When a group holds foreign-currency cash, an exchange-rate effect may be shown outside the three activity subtotals so translated beginning cash can reconcile to translated ending cash. That line is not a customer receipt, asset purchase, or borrowing; it reflects how currency translation changes the reporting-currency amount of cash already held. RiverCask assumes no such effect, so its three activity subtotals equal the full $7m change. For a real issuer, preserve the printed exchange-effect line and translation policy. Do not force it into operating cash or describe the translated change as cash generated by the business.
集团持有外币现金时,三类活动小计之外可能出现汇率影响,用于把报告币种下的期初现金调节到期末现金。该项目不是客户收款、资产购买或借款,而是已持有现金在折算后报告币种金额的变化。RiverCask 假设没有汇率影响,因此三类活动小计正好等于全部 700 万美元现金变化。分析真实发行人时,应保留印刷的汇率影响项目与折算政策,不能强行把它塞入经营现金,也不能把折算变化描述成企业产生的现金。
Send each cash movement through one of three routes让每笔现金运动进入三条路线之一
| Route | Plain-language question | Typical movement in this illustration | What the subtotal cannot prove |
|---|---|---|---|
| Operating | What cash moved through the revenue-producing activity and other non-investing/non-financing operations? | Customer collections; suppliers, employees, interest, and income tax paid under the stated U.S. GAAP case assumption | Profit quality, recurrence, or cash available after investment |
| Investing | What cash changed long-lived productive assets and investments outside cash equivalents? | Equipment purchases and proceeds from equipment sold | Whether spending is maintenance or expansion |
| Financing | What cash changed borrowings or owners’ contributed capital? | Loan proceeds, principal repayment, and dividends paid | Whether leverage is safe or distributions are sustainable |
| Noncash side door | Did assets, liabilities, or equity change without cash entering or leaving? | Equipment obtained by issuing a financing obligation | A cash flow in the current period; the transaction belongs in separate disclosure |
| 路线 | 通俗问题 | 本案例中的典型流动 | 小计不能证明 |
|---|---|---|---|
| 经营 | 主要创收活动及非投资、非融资经营事项有多少现金流动? | 客户回款;按本案例美国 GAAP 假设支付供应商、员工、利息和所得税 | 盈利质量、重复性或投资后可用现金 |
| 投资 | 长期生产资产与现金等价物以外投资怎样改变现金? | 购买设备及出售设备所得现金 | 支出属于维护还是扩张 |
| 融资 | 借款或所有者投入资本怎样改变现金? | 取得借款、偿还本金和支付股利 | 杠杆是否安全或分配能否持续 |
| 非现金侧门 | 资产、负债或权益是否在没有现金进出的情况下变化? | 通过签发融资债务取得设备 | 本期现金流;该交易应在其他位置单独披露 |
Classification is governed by the applicable reporting framework and the facts, not by whether a payment feels “good” or “bad.” Interest, dividends, supplier-finance arrangements, acquisitions, and leases can require especially careful policy review and can differ across frameworks. The case below states its assumptions instead of turning them into universal rules. Major investing and financing receipts and payments are generally shown separately unless an applicable net-presentation exception is met.
现金分类由适用报告框架与具体事实决定,不取决于某项支付听起来“好”还是“坏”。利息、股利、供应商融资、收购和租赁尤其需要检查政策,在不同框架下也可能不同。下方案例明确声明自身假设,不把它们写成普遍规则。重大投资和融资现金收入与支付通常应分别列示,除非符合适用的净额列报例外。
The noncash side door prevents a common misunderstanding. If equipment is acquired by issuing debt directly to the vendor, both equipment and debt can rise although cash did not move. Putting an invented purchase inflow and financing outflow into the statement would exaggerate gross cash movement. Instead, disclose the noncash transaction and use asset and financing-liability roll-forwards to connect it to ending balances.
非现金侧门用于避免一种常见误解:若企业直接向供应商签发债务取得设备,设备与债务可以同时增加,但现金没有流动。若在现金流量表里虚构一笔购买流出和融资流入,会夸大现金总收付。正确做法是单独披露非现金交易,并通过资产与融资负债滚动表把它连接到期末余额。
Reconstruct RiverCask from actual cash receipts and payments从实际收付重建 RiverCask 的现金运动
RiverCask Beverage Works is a fictional craft-beverage producer. All amounts are invented U.S. dollar millions for the year ended December 31, 20X5. The case assumes no foreign-currency effect, acquisitions, equity issuance, or other cash flows. It uses a simplified U.S. GAAP presentation: cash interest and income taxes are operating, equipment transactions are investing, and borrowings, principal repayment, and dividends are financing. It describes no real company or security.
虚构酒厂、年度与分类政策RiverCask Beverage Works 是虚构精酿饮料生产商。所有金额均为教学假设,单位为百万美元,期间为截至 20X5 年 12 月 31 日的年度。案例假设不存在汇率影响、收购、发行权益或其他现金流,并采用简化美国 GAAP 列报:现金利息与所得税归入经营活动,设备交易归入投资活动,借款、偿还本金与股利归入融资活动。本案例不描述任何真实公司或证券。
| Direct cash movement in 20X5 | Amount | Route |
|---|---|---|
| Cash collected from beverage customers | +$120m | Operating receipt |
| Cash paid for ingredients, packaging, payroll, and operating overhead | −$94m | Operating payment |
| Cash interest paid | −$4m | Operating payment under the case policy |
| Cash income taxes paid | −$3m | Operating payment under the case policy |
| Net cash from operating activities | +$19m | Calculation: $120m − $94m − $4m − $3m |
| Cash purchases of brewing and canning equipment | −$14m | Investing payment |
| Cash proceeds from equipment sold | +$2m | Investing receipt |
| Net cash used in investing activities | −$12m | Calculation: −$14m + $2m |
| Cash proceeds from bank borrowing | +$15m | Financing receipt |
| Debt principal repaid | −$7m | Financing payment |
| Dividends paid | −$8m | Financing payment |
| Net cash from financing activities | $0m | Calculation: $15m − $7m − $8m |
| 20X5 年直接现金运动 | 金额 | 路线 |
|---|---|---|
| 向饮料客户收取现金 | +1.2 亿美元 | 经营现金收入 |
| 支付原料、包装、工资与经营间接费用 | −9,400 万美元 | 经营现金支付 |
| 支付现金利息 | −400 万美元 | 按案例政策归入经营支付 |
| 支付现金所得税 | −300 万美元 | 按案例政策归入经营支付 |
| 经营活动现金净额 | +1,900 万美元 | 计算:1.2 亿 − 9,400 万 − 400 万 − 300 万 |
| 以现金购买酿造与罐装设备 | −1,400 万美元 | 投资现金支付 |
| 出售设备所得现金 | +200 万美元 | 投资现金收入 |
| 投资活动所用现金净额 | −1,200 万美元 | 计算:−1,400 万 + 200 万 |
| 取得银行借款现金 | +1,500 万美元 | 融资现金收入 |
| 偿还债务本金 | −700 万美元 | 融资现金支付 |
| 支付股利 | −800 万美元 | 融资现金支付 |
| 融资活动现金净额 | 0 | 计算:1,500 万 − 700 万 − 800 万 |
This direct-method view names major classes of gross operating receipts and payments. It makes the $19m operating subtotal intuitive: customers supplied $120m, while operating counterparties, lenders through interest, and tax authorities received $101m. It does not replace the income statement. Customer cash receipts are not necessarily revenue, cash paid to suppliers is not necessarily cost of sales, and cash tax is not necessarily tax expense because accrual timing differs.
直接法视图列出主要经营现金收入与支付类别,让 1,900 万美元经营小计更直观:客户流入 1.2 亿美元,经营对手方、通过利息收款的贷款人及税务机关合计收到 1.01 亿美元。但它不能取代利润表。由于权责时点不同,客户收款不一定等于收入,向供应商支付的现金不一定等于销售成本,现金税也不一定等于所得税费用。
Reach the same operating cash through the indirect mirror通过间接法镜像到达同一经营现金
The indirect method does not create a different amount of operating cash. It explains why the accrual earnings starting point differs from operating cash. RiverCask reports fictional net income of $15m. Depreciation reduced profit without a current cash payment, so it is added back. Increases in operating assets generally represent cash not yet collected or cash absorbed; decreases release cash. For operating liabilities, increases generally preserve cash and decreases use it, subject to the exact account and transaction.
间接法不会创造另一项经营现金金额,而是解释权责盈利起点为何不同于经营现金。RiverCask 的虚构净利润为 1,500 万美元。折旧减少利润但本期不支付现金,因此被加回。经营资产增加通常表示尚未收现或吸收现金,经营资产减少则释放现金;经营负债增加通常保留现金,减少则使用现金,但最终仍要结合具体账户与交易判断。
| Indirect operating reconciliation | Amount | Cash logic |
|---|---|---|
| Net income | $15m | Accrual earnings starting point |
| Depreciation | +$6m | Noncash expense added back; original equipment cash flow is not reversed here |
| Increase in accounts receivable | −$3m | Recognized sales not yet collected absorb cash relative to profit |
| Decrease in inventory | +$2m | Inventory release adds cash relative to the expense pattern |
| Decrease in accounts payable | −$1m | Paying down operating obligations uses cash |
| Net cash from operating activities | $19m | Calculation: $15m + $6m − $3m + $2m − $1m |
| 间接法经营调节 | 金额 | 现金逻辑 |
|---|---|---|
| 净利润 | 1,500 万美元 | 权责盈利起点 |
| 折旧 | +600 万美元 | 加回非现金费用;原设备现金支出不会在这里逆转 |
| 应收账款增加 | −300 万美元 | 已确认但尚未收款的销售相对利润吸收现金 |
| 库存减少 | +200 万美元 | 库存释放相对费用确认模式增加现金 |
| 应付账款减少 | −100 万美元 | 偿付经营义务使用现金 |
| 经营活动现金净额 | 1,900 万美元 | 计算:1,500 万 + 600 万 − 300 万 + 200 万 − 100 万 |
RiverCask’s direct receipts and payments yield $19m; its net-income reconciliation also yields $19m. The first shows where operating cash was received and paid. The second shows why net income did not equal that cash. Investing and financing sections—and the period’s total cash change—do not become different merely because the operating section uses another presentation method.
直接法与间接法是同一小计的两种表达RiverCask 的直接收付得到 1,900 万美元,从净利润出发的调节也得到 1,900 万美元。前者说明经营现金从哪里收到、向哪里支付;后者解释净利润为何不等于这笔现金。经营部分改变表达方法,不会让投资、融资部分或本期现金总变动产生另一套结果。
Working-capital signs are not a memorization contest. First determine whether the balance is an operating asset or liability and whether its change arose from the operations being reconciled. Acquisitions, disposals, foreign exchange, noncash transfers, reclassifications, and supplier finance can make the raw balance-sheet change differ from the cash-flow adjustment. Use the relevant note rather than calculating every adjustment as ending balance minus beginning balance.
营运资金符号不是背口诀比赛。先判断余额属于经营资产还是经营负债,再判断变化是否来自正在调节的经营活动。收购、处置、汇率、非现金转移、重分类和供应商融资都会让资产负债表原始变动不同于现金流调节。不能把所有调节都机械计算为期末减期初,而要回到相关附注。
Close the statement, then disclose what never touched cash先闭合现金,再披露从未触及现金的交易
| RiverCask closing bridge | Amount | Check |
|---|---|---|
| Beginning cash and cash equivalents | $12m | Balance-sheet component |
| Beginning restricted cash | $3m | Separate component included in statement scope under the case assumption |
| Beginning total within cash-flow scope | $15m | $12m + $3m |
| Operating cash flow | +$19m | Direct and indirect methods agree |
| Investing cash flow | −$12m | Cash equipment purchases net of sale proceeds |
| Financing cash flow | $0m | Borrowing offset by principal and dividends |
| Net increase in total cash | +$7m | $19m − $12m + $0m |
| Ending total within cash-flow scope | $22m | $15m + $7m |
| Ending cash and cash equivalents | $18m | Balance-sheet component |
| Ending restricted cash | $4m | Separate component; $18m + $4m = $22m |
| RiverCask 期末闭合桥 | 金额 | 核对 |
|---|---|---|
| 期初现金及现金等价物 | 1,200 万美元 | 资产负债表构成 |
| 期初受限现金 | 300 万美元 | 按案例假设纳入报表范围的独立构成 |
| 现金流范围内期初总额 | 1,500 万美元 | 1,200 万 + 300 万 |
| 经营现金流 | +1,900 万美元 | 直接法与间接法一致 |
| 投资现金流 | −1,200 万美元 | 设备现金购买扣除出售所得 |
| 融资现金流 | 0 | 借款流入被偿还本金与股利抵销 |
| 总现金净增加 | +700 万美元 | 1,900 万 − 1,200 万 + 0 |
| 现金流范围内期末总额 | 2,200 万美元 | 1,500 万 + 700 万 |
| 期末现金及现金等价物 | 1,800 万美元 | 资产负债表构成 |
| 期末受限现金 | 400 万美元 | 独立构成;1,800 万 + 400 万 = 2,200 万 |
RiverCask also acquires $5m of canning equipment by issuing a $5m financing obligation directly to the vendor. No cash changes hands in 20X5, so neither a $5m investing outflow nor a $5m financing inflow belongs in the statement. The transaction is disclosed separately. A simplified debt roll-forward confirms the link: $40m beginning debt + $15m cash borrowing + $5m noncash equipment obligation − $7m cash principal repayment = $53m ending debt.
RiverCask 还通过直接向供应商签发 500 万美元融资债务,取得 500 万美元罐装设备。20X5 年没有现金经过公司,因此现金流量表既不应出现 500 万美元投资流出,也不应出现 500 万美元融资流入;该交易应单独披露。简化债务滚动表可确认连接:期初债务 4,000 万 + 现金借款 1,500 万 + 非现金设备债务 500 万 − 现金偿还本金 700 万 = 期末债务 5,300 万美元。
The restricted-cash composition also matters. Total cash in statement scope rises $7m, while restricted cash rises from $3m to $4m and unrestricted cash and equivalents rise from $12m to $18m. A transfer between the two components is not separately added to total cash flow. Availability and restriction terms still matter for liquidity, so read the note even when the closing arithmetic works.
受限现金构成同样重要。报表范围内总现金增加 700 万美元;其中受限现金从 300 万增至 400 万,非受限现金及现金等价物从 1,200 万增至 1,800 万。在两种构成之间转移,不会再次增加总现金流。但限制条款与可用性仍会影响流动性,因此即使闭合算术正确,也必须阅读附注。
Label what the movement map establishes and what it does not标记现金运动图能证明与不能证明的内容
The case supplies $15m net income, cash receipts and payments, balance changes, $14m cash equipment purchases, financing flows, and opening and closing cash components. No amount is a real filing fact.
虚构事实案例给出 1,500 万美元净利润、现金收付、余额变动、1,400 万美元设备现金购买、融资流动以及期初期末现金构成。没有任何金额来自真实披露。
Both operating presentations produce $19m; three sections net to a $7m increase; $15m opening total becomes $22m ending total; debt rolls to $53m.
计算两种经营表达均得到 1,900 万美元;三类活动合计使现金增加 700 万;期初 1,500 万闭合到期末 2,200 万;债务滚动到 5,300 万美元。
U.S. GAAP-style classifications, no exchange effect or omitted cash flows, the restricted-cash scope, and the debt-financed equipment transaction are stated modeling inputs.
假设美国 GAAP 式分类、不存在汇率影响或遗漏现金流、受限现金范围和债务融资设备交易,均为明确模型输入。
The statement alone cannot establish whether inventory release is sustainable, capex is maintenance, restrictions are severe, borrowing is prudent, or dividends are affordable.
判断与未知项仅凭现金流量表无法判断库存释放能否持续、资本开支是否为维护性支出、限制是否严重、借款是否审慎或股利是否可负担。
- A positive operating subtotal is not automatically recurring; customer prepayments, delayed supplier payments, tax timing, or inventory liquidation can affect one period.
- A negative investing subtotal is not automatically favorable growth investment; asset replacement, acquisitions, or financial investments require separate evidence.
- A financing inflow is a source of cash, not operating success. Borrowing creates a liability; equity issuance changes ownership claims.
- A higher ending balance is not the same as freely available liquidity when restricted cash, minimum balances, covenants, or committed payments exist.
- 经营现金小计为正不代表可以重复;客户预付款、延后支付供应商、税务时点或出售库存都可能影响单一期间。
- 投资现金小计为负不自动代表有利增长投资;资产替换、收购或金融投资需要独立证据。
- 融资流入只是现金来源,不是经营成功。借款会产生负债,发行权益会改变所有权要求。
- 存在受限现金、最低余额、契约或已承诺付款时,期末余额更高不等于可自由使用的流动性更强。
This explanation stops at the statement’s architecture and arithmetic. It does not rank cash-flow quality, prescribe an order for reading a filing, calculate free cash flow, or forecast liquidity. Those tasks begin only after the perimeter, classification policy, direct or indirect operating presentation, noncash disclosures, and closing reconciliation are understood.
本页停留在现金流量表的结构与算术,不给现金质量排序,不规定阅读整份披露的步骤,不计算自由现金流,也不预测流动性。只有理解现金边界、分类政策、直接或间接经营表达、非现金披露与期末调节后,才适合进入这些独立任务。
Upload the complete statement and the notes that close it上传完整现金流量表及使它闭合的附注
Upload the complete annual or quarterly filing, not a cropped cash-flow table. Include the statement of cash flows, comparative balance sheets, income statement, cash and cash-equivalent policy, restricted-cash reconciliation, property and equipment note, debt and financing-liability roll-forward, lease note, working-capital notes, acquisition or disposal disclosures, and supplemental noncash investing and financing information. State entity, exact period, currency, units, framework, audit status, and restatements.
Ask Stock Explained to extract every cash-flow line in printed order with sign, section, subtotal, period column, page locator, and reported/calculated label. Request separate bridges for operating cash, total opening-to-closing cash, debt changes, and material noncash transactions. Then open every locator in the uploaded originals. Verify units, signs, gross versus net presentation, classification policy, cash scope, restricted amounts, working-capital components, capex, borrowing versus principal, dividends, and noncash equipment. Recalculate all subtotals and leave unsupported classifications unresolved.
上传完整年度或季度披露,而不是裁切后的现金流表。材料应包括现金流量表、比较资产负债表、利润表、现金及现金等价物政策、受限现金调节、固定资产附注、债务与融资负债滚动表、租赁附注、营运资金附注、收购或处置披露,以及补充非现金投资和融资资料。声明主体、准确期间、币种、单位、会计框架、审计状态与重述。
要求 Stock Explained 按印刷顺序提取每个现金流项目,返回符号、类别、小计、期间栏、页码与已报告/已计算标签;分别生成经营现金桥、期初到期末总现金桥、债务变化桥和重大非现金交易表。随后打开上传原件中的每个位置,核对单位、符号、总额或净额列报、分类政策、现金范围、受限金额、营运资金构成、资本开支、借款与本金、股利和非现金设备。重算全部小计;证据不足的分类保持未解决。
Upload the full statement and defining notes, trace every movement and noncash transaction to its original location, and verify the closing cash reconciliation.
上传完整现金流量表与定义性附注,把每笔流动和非现金交易追踪到原始位置,并核验期末现金调节。
Open Stock Explained打开“一眼看懂这只股票”Questions raised by the completed cash map完成现金运动图后常见的问题
The indirect reconciliation adds $6m noncash depreciation, subtracts a $3m receivable increase, adds a $2m inventory decrease, and subtracts a $1m payable decrease. The result is $15m + $6m − $3m + $2m − $1m = $19m. The difference reflects timing and noncash accounting, not an automatic quality verdict.
RiverCask 净利润 1,500 万,为何经营现金是 1,900 万?间接法加回 600 万非现金折旧,扣除应收增加 300 万,加上库存减少 200 万,再扣除应付减少 100 万:1,500 + 600 − 300 + 200 − 100 = 1,900 万美元。差额反映时点与非现金会计,不自动构成质量结论。
No when applied consistently to the same entity, period, and framework. RiverCask’s direct customer receipts and cash payments net to $19m; its indirect reconciliation also reaches $19m. The methods provide different information about the same operating-cash subtotal.
直接法与间接法会产生不同经营现金流吗?对同一主体、期间和框架一致应用时不会。RiverCask 的客户收款与现金支付净额为 1,900 万美元,间接调节也到达 1,900 万美元。两种方法只是用不同信息解释同一个经营现金小计。
The $5m equipment and $5m obligation arise without cash changing hands in 20X5. Recording both an investing outflow and financing inflow would invent cash movement. The transaction belongs in supplemental noncash disclosure and should appear in the equipment and debt roll-forwards.
债务融资取得的设备为何不在现金流量表中?500 万美元设备与 500 万美元债务在 20X5 年形成时没有现金收付。若同时记录投资流出与融资流入,就会虚构现金运动。该交易应进入补充非现金披露,并出现在设备和债务滚动表中。
The cash-flow total may include multiple balance-sheet components. In this U.S. GAAP illustration, $18m cash and equivalents plus $4m restricted cash reconciles to the $22m ending total. Read the cash policy and reconciliation; never force one printed line to equal a broader total.
现金流量表期末现金为何可能不同于资产负债表的一行现金?现金流总额可能包含多个资产负债表构成。本美国 GAAP 案例中,1,800 万美元现金及现金等价物加 400 万受限现金,调节至 2,200 万美元期末总额。应阅读现金政策与调节,不能强迫一行项目等于更广范围总额。
Not without supporting detail. The cash-flow statement establishes a cash purchase of property or equipment under the case classification. It does not determine whether the spending replaces worn assets, adds capacity, satisfies regulation, or combines purposes. Use project, asset, commitment, and management disclosures before splitting maintenance from growth.
1,400 万美元设备购买等于维护性资本开支吗?没有支持细节时不能等同。现金流量表只能按案例分类确认固定资产或设备现金购买,不能判断支出用于替换旧资产、增加产能、满足监管还是多种目的。拆分维护与增长前,应查看项目、资产、承诺及管理层披露。
Primary sources for cash movement and presentation支持现金运动与列报的一手来源
The sources support cash-flow purposes, operating methods, activity classifications, noncash disclosure, financing-liability changes, and restricted-cash presentation. Exact classification and cash-equivalent boundaries depend on the reporting framework, jurisdiction, facts, policy, and effective date. They do not validate fictional RiverCask.
This movement map is educational, not accounting, audit, legal, tax, or individualized investment advice. A cash flow statement cannot by itself establish recurrence, liquidity access, solvency, capital-spending purpose, value, or future returns. Use complete current filings and qualified help when classifications or restrictions are material.
以上来源支持现金流量表目的、经营现金表达方法、活动分类、非现金披露、融资负债变化和受限现金列报。准确分类与现金等价物边界取决于报告框架、司法辖区、具体事实、政策和生效日期;这些来源不验证虚构 RiverCask。
本现金运动图仅供学习,不构成会计、审计、法律、税务或个性化投资建议。现金流量表不能单独证明重复性、流动性获取、偿债能力、资本开支目的、价值或未来回报。若分类或限制影响重大,应使用完整当前披露并寻求合格专业帮助。
- SEC — Beginners’ Guide to Financial Statements
- IFRS Foundation — IAS 7 Statement of Cash Flows
- FASB — Statement No. 95, Statement of Cash Flows
- FASB — ASU 2016-18 Restricted Cash
- IFRS Interpretations Committee — Supply Chain Financing Arrangements
- IFRS Foundation — Disclosure Initiative, Amendments to IAS 7