Issue the calculation ticket before pulling numbers取数前先签发计算工单
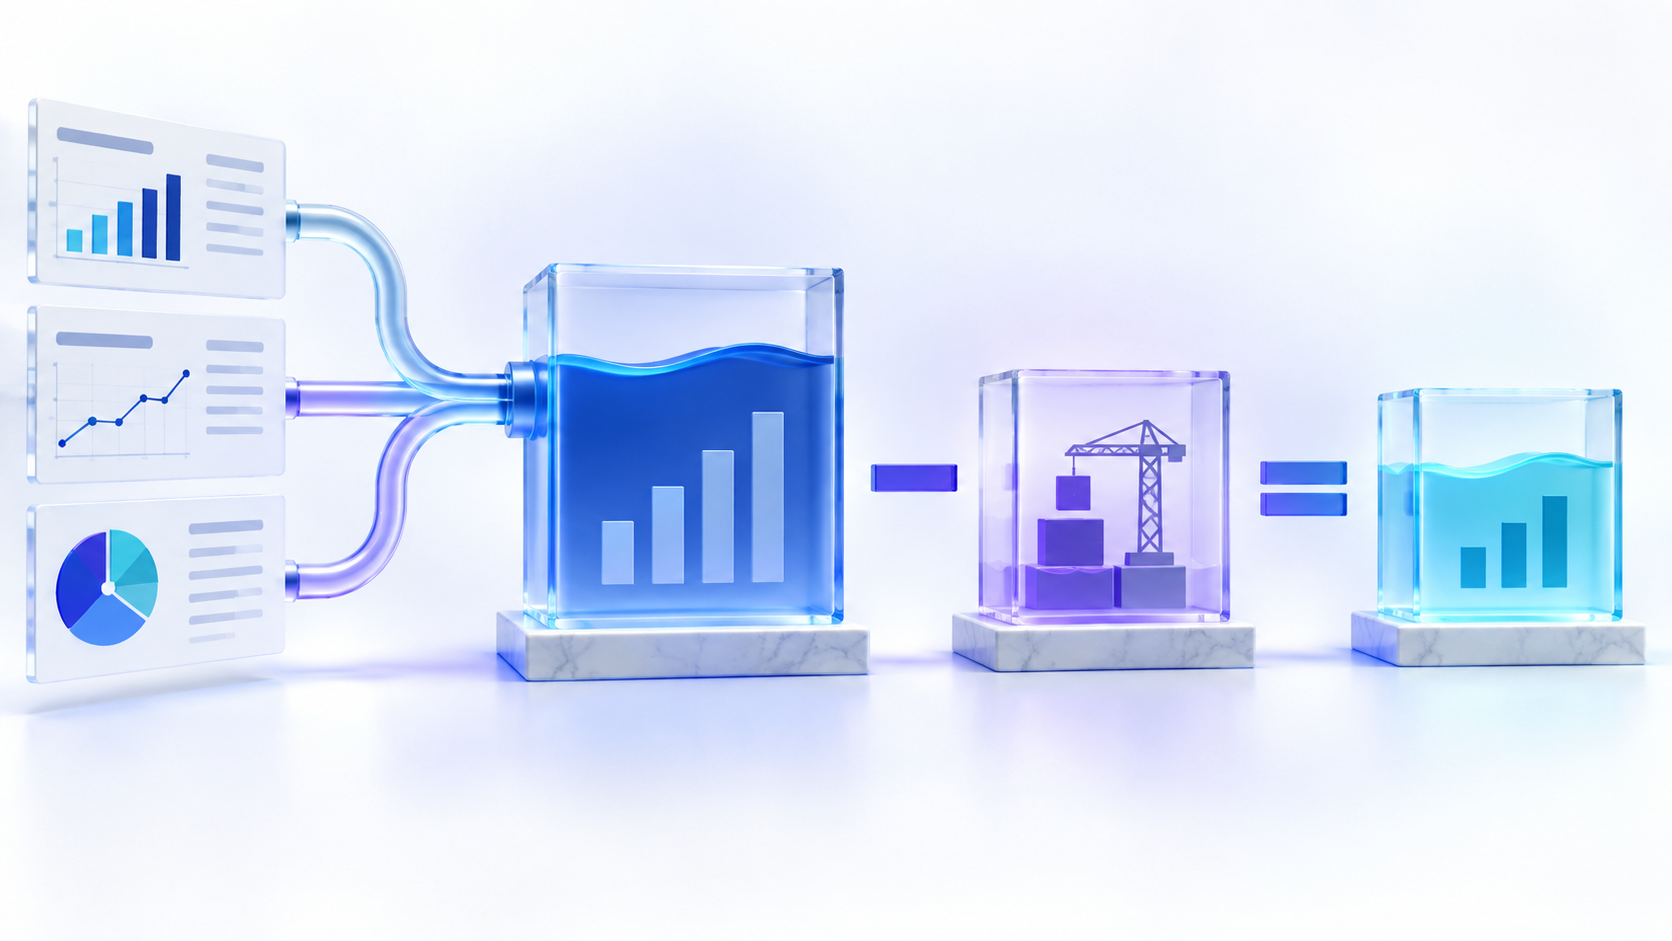
Use this stated investor convention: free cash flow = net cash provided by operating activities − cash purchases of property, plant, and equipment. When the filing prints PP&E purchases as a negative cash-flow line, either add the signed line to operating cash flow or subtract its positive magnitude—never subtract the negative twice. Match entity, currency, units, and period; build standalone quarters before summing trailing twelve months; and label decisions about discontinued operations, asset sales, acquisitions, capitalized software, and lease payments. Then reconcile, rather than replace, any company-defined free cash flow.
本页采用明确的投资者常见口径:自由现金流 = 经营活动提供的现金净额 − 购买物业、厂房及设备的现金支出。若财报把固定资产购买列为负数现金流,可以把该带符号项目加到经营现金流,也可以减去其正的绝对值;绝不能对负号重复相减。主体、币种、单位和期间必须一致;先还原单季度,再汇总过去十二个月;终止经营、资产出售、收购、资本化软件和租赁付款的处理都要明确标记。公司自定义自由现金流应与本口径调节,而不是覆盖它。
Lock the formula, sign, scope, and period fields锁定公式、符号、范围与期间字段
| Ticket field | Required entry | Control question |
|---|---|---|
| Formula ID | Investor FCF = reported CFO − gross cash purchases of PP&E | Is this the same definition in every compared column? |
| Sign convention | CFO is positive inflow; PP&E purchases stored as positive magnitude for subtraction | Was a parenthesized outflow converted only once? |
| Entity and scope | Consolidated group; total operations unless separately labeled | Are discontinued operations or acquired businesses included? |
| Period | Standalone quarter, fiscal year, or TTM ending on an exact date | Are cumulative year-to-date columns being mistaken for quarters? |
| Currency and units | U.S. dollars in millions in the fictional example | Do both inputs use the same currency and scale? |
| Output labels | Calculated investor FCF, calculated FCF margin, management-defined adjusted FCF | Can a reviewer distinguish reported, calculated, and company-defined amounts? |
| 工单字段 | 必填内容 | 控制问题 |
|---|---|---|
| 公式编号 | 投资者 FCF = 已报告 CFO − 固定资产现金购买总额 | 所有比较栏是否采用同一定义? |
| 符号约定 | CFO 为正流入;固定资产购买存为正的支出绝对值 | 括号表示的流出是否只转换一次? |
| 主体与范围 | 合并集团;除非另标,否则包含全部经营范围 | 是否包含终止经营或被收购业务? |
| 期间 | 单季度、财政年度或截至准确日期的 TTM | 是否把累计年初至今栏目误当单季度? |
| 币种与单位 | 虚构案例使用百万美元 | 两个输入是否使用相同币种与数量级? |
| 输出标签 | 已计算投资者 FCF、已计算 FCF 利润率、管理层定义调整后 FCF | 复核者能否区分已报告、已计算和公司定义金额? |
Write both equivalent formulas beside the source lines. Magnitude convention: FCF = CFO − PP&E purchase magnitude. Signed-line convention: FCF = CFO + signed PP&E purchase line. If CFO is $28m and the statement prints purchases as ($18m), the result is $28m − $18m = $10m, equivalently $28m + (−$18m) = $10m. The erroneous $28m − (−$18m) = $46m reverses the outflow twice.
在来源项目旁同时写下两种等价公式。绝对值口径:FCF = CFO − 固定资产购买支出绝对值。带符号口径:FCF = CFO + 带符号的固定资产购买项目。若 CFO 为 2,800 万美元,财报把购买列为(1,800 万美元),正确结果为 2,800 − 1,800 = 1,000 万美元,也等于 2,800 +(−1,800)= 1,000 万美元。错误写法 2,800 −(−1,800)= 4,600 万美元把流出符号反转了两次。
Free cash flow is not uniformly defined. The chosen formula does not prove that the result is available for discretionary spending: debt service, lease obligations, acquisitions, restricted cash, and other required uses may remain. Preserve the reported operating-cash subtotal and disclose the exact deduction.
这是分析口径,不是必列小计自由现金流并没有统一定义。所选公式也不能证明结果可任意支配:债务服务、租赁义务、收购、受限现金和其他必需用途可能仍未扣除。必须保留已报告经营现金小计,并披露准确扣减项。
Pick up two source lines without changing their meaning提取两个来源项目,但不要改变含义
- Locate “net cash provided by operating activities” in the complete statement of cash flows. Record the exact column, period end, period length, units, entity, and whether the figure covers continuing and discontinued operations.
- Locate gross cash purchases of property, plant, and equipment in investing activities or the supporting note. Preserve the printed label—capital expenditures, purchases of PP&E, equipment additions paid in cash, or another issuer-specific term may not have identical scope.
- Open the property and equipment note. Compare cash purchases with additions, disposals, noncash acquisitions, capitalized interest, and roll-forward changes; additions are not automatically cash capex.
- Record capitalized software, acquisitions, asset-sale proceeds, and lease-related cash on separate lines. Do not decide their FCF treatment until the ticket definition is applied.
- Recalculate the cash-flow subtotals and opening-to-closing cash movement before trusting the extracted lines.
- 在完整现金流量表中定位“经营活动提供的现金净额”。记录准确栏目、期末日、期间长度、单位、主体,以及数字是否包含持续经营与终止经营。
- 在投资活动或支持附注中定位购买物业、厂房及设备的现金支出总额。保留原始名称;“资本开支”“购买 PP&E”“以现金取得设备”等发行人术语的范围不一定相同。
- 打开固定资产附注,把现金购买与新增、处置、非现金取得、资本化利息及滚动表变化比较。资产新增不自动等于现金资本开支。
- 把资本化软件、收购、资产出售所得和租赁相关现金放在独立项目;应用工单定义前不要决定是否纳入 FCF。
- 在信任提取项目之前,重算现金流各小计及期初到期末现金运动。
Quarterly arithmetic requires a period map. A six-month filing normally presents cumulative cash flows, so its column is not Q2 alone. Derive standalone Q2 as six months minus Q1; derive Q3 as nine months minus six months; derive Q4 as full year minus nine months. Use issuer-labeled standalone data when available and document every subtraction. TTM is the sum of the latest four standalone fiscal quarters, not the sum of overlapping year-to-date columns.
季度计算必须配备期间地图。六个月披露通常展示累计现金流,因此该栏并不是第二季度单季。单独 Q2 应由六个月累计减 Q1;Q3 由九个月累计减六个月;Q4 由全年减九个月。若发行人提供已标记的单季度数据,应优先使用并记录每次相减。TTM 是最近四个独立财政季度之和,绝不是重叠累计栏目的合计。
- A 52- or 53-week fiscal year can make calendar comparisons uneven; record the actual weeks and dates.
- A business acquisition can enter midway through TTM, so consolidated scope may differ even when the formula is unchanged.
- Restated discontinued-operation columns can change historical CFO; use the latest comparable presentation and retain the original reference.
- Translation differences require consistent reporting currency. Do not mix a local-currency capex note with consolidated-dollar CFO.
- 52 周或 53 周财政年度会让日历比较不均衡,应记录实际周数与日期。
- 企业收购可能在 TTM 中途纳入合并范围,因此公式不变也不代表范围相同。
- 终止经营重述可能改变历史 CFO,应使用最新可比列报并保留原始参考。
- 折算差异要求报告币种一致,不能把本币资本开支附注与合并美元 CFO 混用。
A roll-forward shortcut can check, but should not obscure, the quarter map. For a March 31 TTM following a December fiscal year-end, TTM CFO can be checked as prior FY CFO + current Q1 CFO − prior-year Q1 CFO; perform the same equation for PP&E purchases. The two calculations must use comparable standalone Q1 figures. If a later filing recasts discontinued operations, changes the fiscal calendar, or corrects a prior column, rebuild all four quarters from the latest comparable disclosures instead of forcing the shortcut to tie. Store the filing version and publication date beside every derived quarter.
滚动捷径可以用于检查,但不能遮蔽季度地图。若财政年末为 12 月,而 TTM 截止于次年 3 月 31 日,可以用“上个 FY CFO + 本年 Q1 CFO − 上年 Q1 CFO”核对 TTM CFO;PP&E 购买也执行同一等式。两项计算都必须使用可比的独立 Q1。若后续披露重列终止经营、改变财政日历或更正历史栏目,应从最新可比披露重建四个季度,而不是强迫捷径勾稽。每个推导季度旁都要保存披露版本和发布日期。
Build four standalone quarters for ThermalLoop为 ThermalLoop 建立四个独立季度
ThermalLoop Cooling Services is a fictional operator that installs and services data-center cooling systems. All amounts are invented U.S. dollar millions. Q1 through Q4 are standalone quarters in the fiscal year ended December 31, 20X5. Reported CFO covers the consolidated group and total operations. PP&E purchases are shown below as positive magnitudes for subtraction. The example describes no real issuer or security.
虚构公司、单位与期间ThermalLoop Cooling Services 是虚构的数据中心冷却系统安装与服务商。所有金额均为教学假设,单位为百万美元。Q1 至 Q4 是截至 20X5 年 12 月 31 日财政年度的独立季度。已报告 CFO 覆盖合并集团及全部经营范围;下表把 PP&E 购买列为用于减法的正支出绝对值。本案例不描述真实发行人或证券。
| Standalone period | Revenue | Reported CFO | Cash PP&E purchases | Calculated investor FCF | FCF margin |
|---|---|---|---|---|---|
| Q1 20X5 | $105m | $28m | $18m | $28m − $18m = $10m | $10m ÷ $105m = 9.5% |
| Q2 20X5 | $112m | $34m | $22m | $34m − $22m = $12m | $12m ÷ $112m = 10.7% |
| Q3 20X5 | $118m | $31m | $27m | $31m − $27m = $4m | $4m ÷ $118m = 3.4% |
| Q4 20X5 | $125m | $45m | $30m | $45m − $30m = $15m | $15m ÷ $125m = 12.0% |
| FY/TTM ended Dec. 31, 20X5 | $460m | $138m | $97m | $138m − $97m = $41m | $41m ÷ $460m = 8.9% |
| 独立期间 | 收入 | 已报告 CFO | PP&E 现金购买 | 已计算投资者 FCF | FCF 利润率 |
|---|---|---|---|---|---|
| 20X5 Q1 | 1.05 亿美元 | 2,800 万美元 | 1,800 万美元 | 2,800 − 1,800 = 1,000 万美元 | 1,000 ÷ 10,500 = 9.5% |
| 20X5 Q2 | 1.12 亿美元 | 3,400 万美元 | 2,200 万美元 | 3,400 − 2,200 = 1,200 万美元 | 1,200 ÷ 11,200 = 10.7% |
| 20X5 Q3 | 1.18 亿美元 | 3,100 万美元 | 2,700 万美元 | 3,100 − 2,700 = 400 万美元 | 400 ÷ 11,800 = 3.4% |
| 20X5 Q4 | 1.25 亿美元 | 4,500 万美元 | 3,000 万美元 | 4,500 − 3,000 = 1,500 万美元 | 1,500 ÷ 12,500 = 12.0% |
| 截至 20X5-12-31 的 FY/TTM | 4.6 亿美元 | 1.38 亿美元 | 9,700 万美元 | 1.38 亿 − 9,700 万 = 4,100 万美元 | 4,100 ÷ 46,000 = 8.9% |
Every annual total foots across the quarters: revenue $105m + $112m + $118m + $125m = $460m; CFO $28m + $34m + $31m + $45m = $138m; PP&E purchases $18m + $22m + $27m + $30m = $97m; FCF $10m + $12m + $4m + $15m = $41m. Because the TTM end date equals the fiscal year end here, FY and TTM are identical. At another quarter-end, roll the window forward and drop the oldest standalone quarter.
年度总额均可从四个季度横向加总:收入 1.05 + 1.12 + 1.18 + 1.25 = 4.6 亿美元;CFO 2,800 + 3,400 + 3,100 + 4,500 = 1.38 亿美元;PP&E 购买 1,800 + 2,200 + 2,700 + 3,000 = 9,700 万美元;FCF 1,000 + 1,200 + 400 + 1,500 = 4,100 万美元。由于 TTM 截止日正好等于本案例财政年末,FY 与 TTM 相同;若截止日处于其他季度,应滚动窗口并移除最早单季。
FCF margin uses revenue from the identical scope and period: FCF margin = calculated investor FCF ÷ revenue × 100. ThermalLoop’s 8.9% is a calculation, not a reported accounting margin or a forecast. Q3’s lower 3.4% can be described as a period outcome; deciding whether it reflects planned installation spending, weak collections, or a problem requires CFO components and project evidence outside this calculation ticket.
FCF 利润率必须使用相同范围与期间的收入:FCF 利润率 = 已计算投资者 FCF ÷ 收入 × 100%。ThermalLoop 的 8.9% 是计算结果,不是已报告会计利润率,也不是预测。Q3 较低的 3.4% 可以被描述为该期结果;至于它源于计划安装支出、回款偏弱还是经营问题,需要本工单之外的 CFO 构成与项目证据。
Route excluded cash items through an exception queue把未纳入项目送入范围例外队列
| Item in ThermalLoop’s invented TTM disclosure | Amount | Base formula treatment | Required label or check |
|---|---|---|---|
| Capitalized internal-use software paid in cash | $15m outflow | Not deducted because the ticket specifies PP&E purchases only | Show a broader reinvestment view separately; inspect capitalization policy |
| Business acquisition, net of cash acquired | $25m outflow | Not routine PP&E capex and not deducted in base FCF | Keep visible as an acquisition cash use and scope change |
| Proceeds from equipment sold | $12m inflow | Not netted against gross PP&E purchases | A net-capex convention would be a different formula |
| Principal portion of lease payments | $8m outflow | Not separately deducted in the base formula | Check where reported CFO and financing cash already contain lease payments |
| Discontinued-operation operating cash use | $4m outflow included in CFO | Retained because base CFO covers total operations | A continuing-only measure must add back the outflow and change the scope label |
| Restructuring cash payments included in CFO | $6m outflow | Retained in reported CFO | Any exclusion creates a company- or analyst-defined adjustment |
| ThermalLoop 虚构 TTM 披露项目 | 金额 | 基础公式处理 | 必需标签或核对 |
|---|---|---|---|
| 以现金支付的资本化内部使用软件 | 流出 1,500 万美元 | 工单只指定 PP&E 购买,因此基础公式不扣除 | 另列广义再投资视图,并检查资本化政策 |
| 企业收购,扣除取得现金 | 流出 2,500 万美元 | 不属于日常 PP&E 资本开支,基础 FCF 不扣除 | 保留为收购现金用途与范围变化 |
| 出售设备所得 | 流入 1,200 万美元 | 不与 PP&E 购买总额相抵 | 净资本开支口径属于另一公式 |
| 租赁付款本金部分 | 流出 800 万美元 | 基础公式不另行扣除 | 检查已报告 CFO 与融资现金在哪里包含租赁付款 |
| 已包含在 CFO 的终止经营现金占用 | 流出 400 万美元 | 基础 CFO 覆盖全部经营,因此保留 | 持续经营口径必须加回该流出并改变范围标签 |
| 已包含在 CFO 的重组现金支付 | 流出 600 万美元 | 保留在已报告 CFO 中 | 任何剔除都会形成公司或分析者定义调整 |
The queue prevents silent netting. Subtracting $97m PP&E purchases and then also subtracting all investing cash would double count those purchases. Netting $12m sale proceeds against purchases would produce $85m “net capex” and $53m FCF, but that is not the gross-purchase convention selected here. Likewise, subtracting a $25m acquisition may answer a post-acquisition cash question, yet calling the result ordinary FCF would hide a material definition change.
例外队列用于防止暗中净额处理。先扣除 9,700 万美元 PP&E 购买,再扣除全部投资现金,会重复计算固定资产购买。若把 1,200 万美元出售所得与购买相抵,会得到 8,500 万美元“净资本开支”和 5,300 万美元 FCF,但这不是本页选择的购买总额口径。同样,扣除 2,500 万美元收购可能回答“收购后现金”问题,却不能把结果仍称为普通 FCF,否则会隐藏重大定义变化。
The $15m software payment is an investing outflow in the fictional disclosure even though it is not in the PP&E purchase line. Base FCF remains $41m by definition; a broader reinvestment FCF is $138m − $97m − $15m = $26m, with margin $26m ÷ $460m = 5.7%. Keep both labels rather than quietly replacing one.
资本化不等于不花现金虚构披露中的 1,500 万美元软件付款属于投资流出,即使它不在 PP&E 购买项目中。按定义,基础 FCF 仍为 4,100 万美元;广义再投资 FCF 为 1.38 亿 − 9,700 万 − 1,500 万 = 2,600 万美元,利润率为 2,600 万 ÷ 4.6 亿 = 5.7%。应并列保留两个标签,不能悄悄替换。
Bridge the company definition without adopting it silently调节公司口径,但不要默认接受
Assume ThermalLoop management presents “adjusted free cash flow” using a fictional policy: start with reported CFO, add back discontinued-operation operating cash use and restructuring cash payments, then deduct gross PP&E purchases, capitalized software, and lease principal. This is not the base investor convention. It is a separately named liquidity measure whose definition, reconciliation, consistency, and implications must be checked.
假设 ThermalLoop 管理层按一项虚构政策披露“调整后自由现金流”:从已报告 CFO 出发,加回终止经营的经营现金占用和重组现金支付,再扣除 PP&E 购买总额、资本化软件及租赁本金。这不是基础投资者口径,而是另行命名的流动性指标,需要检查定义、调节、一致性与含义。
| TTM reconciliation to company-defined adjusted FCF | Amount | Running total |
|---|---|---|
| Reported net cash from operating activities | $138m | $138m |
| Add discontinued-operation operating cash use | +$4m | $142m continuing-scope adjusted CFO |
| Add restructuring cash payments | +$6m | $148m |
| Subtract gross cash PP&E purchases | −$97m | $51m |
| Subtract capitalized internal-use software | −$15m | $36m |
| Subtract lease principal | −$8m | $28m adjusted FCF |
| TTM 至公司定义调整后 FCF 的调节 | 金额 | 累计结果 |
|---|---|---|
| 已报告经营活动现金净额 | 1.38 亿美元 | 1.38 亿美元 |
| 加:终止经营的经营现金占用 | +400 万美元 | 1.42 亿美元持续经营调整 CFO |
| 加:重组现金支付 | +600 万美元 | 1.48 亿美元 |
| 减:PP&E 现金购买总额 | −9,700 万美元 | 5,100 万美元 |
| 减:资本化内部使用软件 | −1,500 万美元 | 3,600 万美元 |
| 减:租赁本金 | −800 万美元 | 2,800 万美元调整后 FCF |
Company-defined adjusted FCF is $28m, below base investor FCF of $41m because the additional $23m deductions exceed the $10m add-backs. The difference reconciles exactly: $41m + $4m + $6m − $15m − $8m = $28m. The $97m PP&E deduction appears in both and cancels in the comparison. Calling one “better” would skip the real work: test whether restructuring cash is recurring, whether continuing-only scope is useful, whether lease principal improves comparability, and whether software is economically similar to equipment.
公司定义调整后 FCF 为 2,800 万美元,低于 4,100 万美元基础投资者 FCF,因为新增 2,300 万美元扣减超过 1,000 万美元加回。差额可准确调节:4,100 + 400 + 600 − 1,500 − 800 = 2,800 万美元。9,700 万美元 PP&E 扣减在两种口径中都有,比较时相互抵销。不能简单说哪个“更好”;真正工作是判断重组现金是否重复、持续经营范围是否有用、租赁本金是否改善可比性,以及软件与设备是否具有类似经济作用。
Audit the calculation cells before using the output使用结果之前逐格审计计算单元
| Workpaper cell | Stored value | Source or formula | Pass condition |
|---|---|---|---|
| PERIOD_KEY | FY/TTM ended 20X5-12-31 | Four standalone fiscal quarters | No overlapping cumulative period and no missing week |
| CFO_REPORTED | $138m | Cash-flow statement operating subtotal | Matches statement column and retains stated operation scope |
| PPE_SIGNED_RAW | −$97m | Investing line as printed | Sign and label copied exactly; no asset-sale netting |
| PPE_MAGNITUDE | $97m | Absolute value of PPE_SIGNED_RAW | Converted once and only once for subtraction |
| FCF_INVESTOR | $41m | CFO_REPORTED − PPE_MAGNITUDE | Also equals $138m + (−$97m) |
| REVENUE_MATCHED | $460m | Income statement for identical entity and period | No continuing-only or acquired-scope mismatch |
| FCF_MARGIN | 8.9% | FCF_INVESTOR ÷ REVENUE_MATCHED | Uses unrounded inputs; percentage rounded only for display |
| EXCEPTION_QUEUE | $15m software; $25m acquisition; $12m sale proceeds; $8m lease principal | Notes and other cash-flow lines | Every excluded cash item remains named and traceable |
| 底稿单元 | 储存值 | 来源或公式 | 通过条件 |
|---|---|---|---|
| PERIOD_KEY | 截至 20X5-12-31 的 FY/TTM | 四个独立财政季度 | 没有重叠累计期间,也没有遗漏周数 |
| CFO_REPORTED | 1.38 亿美元 | 现金流量表经营小计 | 与报表栏目一致,并保留声明的经营范围 |
| PPE_SIGNED_RAW | −9,700 万美元 | 按原样复制的投资项目 | 符号与名称准确,没有净掉资产出售所得 |
| PPE_MAGNITUDE | 9,700 万美元 | PPE_SIGNED_RAW 的绝对值 | 只转换一次并仅用于减法 |
| FCF_INVESTOR | 4,100 万美元 | CFO_REPORTED − PPE_MAGNITUDE | 也等于 1.38 亿 +(−9,700 万) |
| REVENUE_MATCHED | 4.6 亿美元 | 同一主体与期间的利润表 | 不存在持续经营或收购范围错配 |
| FCF_MARGIN | 8.9% | FCF_INVESTOR ÷ REVENUE_MATCHED | 使用未舍入输入,只在展示时四舍五入 |
| EXCEPTION_QUEUE | 软件 1,500 万;收购 2,500 万;出售所得 1,200 万;租赁本金 800 万 | 附注与其他现金流项目 | 每项排除现金仍有名称且可追溯 |
The raw signed PP&E cell and the positive-magnitude cell should both remain in the workpaper. That small duplication creates an audit trail: a reviewer can see what the filing printed, how the calculation stores capex, and why the formula subtracts $97m. Do not paste a positive number over the original negative line. Likewise, preserve full-precision quarterly values even when the filing displays rounded millions; sum the reported precision available, calculate the annual result, and round the presentation only at the end. A one-decimal margin should not be reverse-engineered into a supposedly exact cash amount.
底稿应同时保留带原始符号的 PP&E 单元和正绝对值单元。这种看似重复的设计形成审计轨迹:复核者可以看到财报原来怎样列示、计算表怎样储存资本开支,以及公式为何扣除 9,700 万美元。不能用正数覆盖原始负数项目。同样,即使披露以百万为单位四舍五入,也应保留可获得的季度精度,先加总并计算年度结果,最后才舍入展示。不能从一位小数的利润率反推一个看似精确的现金金额。
Adding back the $4m discontinued-operation cash use changes CFO scope from total operations to a continuing-only analytical view. A continuing-only FCF margin therefore also needs revenue excluding the discontinued business for the same four quarters. ThermalLoop does not supply that revenue split, so this page calculates no continuing-only margin. A scope adjustment in the numerator without a matching denominator would look precise but remain invalid.
持续经营口径需要匹配分母加回 400 万美元终止经营现金占用,会把 CFO 范围从全部经营改成仅持续经营的分析视图。持续经营 FCF 利润率因此还需要同四个季度、剔除终止业务后的收入。ThermalLoop 没有提供这项收入拆分,所以本页不计算持续经营利润率。只调整分子却不匹配分母,结果即使看起来精确也无效。
Close total cash before comparing the calculated output比较计算结果前先闭合总现金
| ThermalLoop TTM cash check | Amount | Composition |
|---|---|---|
| Reported operating cash flow | +$138m | Cash-flow statement subtotal |
| Reported investing cash flow | −$125m | −$97m PP&E − $15m software − $25m acquisition + $12m asset-sale proceeds |
| Reported financing cash flow | −$30m | Illustrative net financing amount including disclosed lease and other financing cash |
| Exchange-rate effect | +$2m | Illustrative translation effect |
| Net decrease in cash within statement scope | −$15m | $138m − $125m − $30m + $2m |
| Beginning cash within statement scope | $60m | Illustrative reported balance |
| Ending cash within statement scope | $45m | $60m − $15m |
| ThermalLoop TTM 现金核对 | 金额 | 构成 |
|---|---|---|
| 已报告经营现金流 | +1.38 亿美元 | 现金流量表小计 |
| 已报告投资现金流 | −1.25 亿美元 | −9,700 万 PP&E −1,500 万软件 −2,500 万收购 +1,200 万资产出售所得 |
| 已报告融资现金流 | −3,000 万美元 | 包含已披露租赁及其他融资现金的虚构净额 |
| 汇率影响 | +200 万美元 | 虚构折算影响 |
| 报表范围内现金净减少 | −1,500 万美元 | 1.38 亿 −1.25 亿 −3,000 万 +200 万 |
| 报表范围内期初现金 | 6,000 万美元 | 虚构已报告余额 |
| 报表范围内期末现金 | 4,500 万美元 | 6,000 万 −1,500 万 |
Neither $41m base FCF nor $28m adjusted FCF replaces a cash-flow-statement section, so neither belongs in the closing equation. The cash check validates that CFO and investing inputs came from a coherent statement and that excluded items remain visible. It also shows why “free” is not “change in cash”: acquisitions, asset sales, financing, and translation affect ending cash without entering the chosen base formula.
无论 4,100 万美元基础 FCF 还是 2,800 万美元调整后 FCF,都不能替代现金流量表的任何类别,因此都不应塞入现金闭合等式。现金核对用于确认 CFO 与投资输入来自一张一致报表,并让被排除项目继续可见。它也说明“自由”不等于“现金净变动”:收购、资产出售、融资和折算会改变期末现金,却不进入所选基础公式。
In real work, CFO, PP&E purchases, other investing lines, revenue, and cash balances are copied with locators. ThermalLoop’s figures are entirely invented.
已报告事实真实工作中,CFO、PP&E 购买、其他投资项目、收入和现金余额都应带定位复制。ThermalLoop 数字完全虚构。
Standalone and TTM FCF, FCF margins, broader reinvestment FCF, adjusted FCF, and the cash close are formula outputs.
计算单季度与 TTM FCF、FCF 利润率、广义再投资 FCF、调整后 FCF 和现金闭合均为公式输出。
PP&E-only base capex, positive-magnitude storage, total-operation CFO, and every management adjustment are explicit choices.
假设与政策仅使用 PP&E 的基础资本开支、以正绝对值储存、全口径 CFO 和所有管理层调整都是明确选择。
Recurrence, maintenance needs, acquisition economics, lease comparability, and cash availability require evidence beyond the calculation.
判断与缺失证据重复性、维护需求、收购经济、租赁可比性和现金可用性都需要计算以外的证据。
For comparison, keep formula ID, period length, fiscal dates, entity scope, currency, and treatment queue identical. If they cannot be aligned, present separate labeled series instead of a false ranking. This calculation work order establishes traceable arithmetic; it does not diagnose why FCF changed, forecast the next period, or decide whether the amount supports valuation or distributions.
进行比较时,公式编号、期间长度、财政日期、主体范围、币种与例外队列处理必须一致。无法对齐时,应展示独立命名序列,而不是制造虚假排名。本计算工单只建立可追溯算术,不诊断 FCF 变化原因,不预测下期,也不判断金额是否支持估值或分配。
Upload the complete cash-flow package, not two copied numbers上传完整现金流资料包,而不是两个抄录数字
Upload the complete annual filing and each interim filing needed for the TTM window, plus the matching earnings releases. Include cash-flow statements, revenue statements, PP&E and capitalized-software notes, acquisition and disposal disclosures, discontinued-operation note, lease note, noncash investing and financing schedule, company FCF reconciliation, and cash-balance reconciliation. State entity, fiscal dates, standalone versus cumulative columns, currency, units, framework, audit status, and restatements.
Ask Stock Explained to extract each CFO, PP&E purchase, revenue, and adjustment with exact page, table, column, label, sign, and period; then request a quarter-derivation grid, base FCF calculation, company-definition bridge, and total-cash check. Open every locator in the uploaded originals. Verify that cumulative periods were differenced correctly, parenthetical outflows were converted once, acquisitions and sale proceeds were not netted into gross capex, software and leases follow the chosen labels, and all subtotals recalculate. Leave unsupported classifications unresolved.
上传 TTM 窗口所需的完整年度披露、各中期披露及同期业绩公告。材料包括现金流量表、收入报表、PP&E 与资本化软件附注、收购与处置披露、终止经营附注、租赁附注、非现金投资融资明细、公司 FCF 调节和现金余额调节。声明主体、财政日期、单季或累计栏目、币种、单位、框架、审计状态与重述。
要求 Stock Explained 提取每项 CFO、PP&E 购买、收入与调整,返回准确页码、表格、栏目、名称、符号和期间;再生成季度还原表、基础 FCF 计算、公司口径桥与总现金核对。打开上传原件中的每个位置,核实累计期间相减正确、括号流出只转换一次、收购与出售所得没有被净入购买总额、软件与租赁遵循所选标签,并重算全部小计。证据不足的分类保持未解决。
Upload the full filings for the selected period, require line-level locators and signs, and verify every quarter, adjustment, and closing-cash subtotal in the originals.
上传所选期间的完整披露,要求行级定位与符号,并在原件中核验每个季度、调整和期末现金小计。
Open Stock Explained打开“一眼看懂这只股票”Questions that arise after the FCF ticket is completeFCF 工单完成后常见的问题
Choose one sign convention. If the statement line is −$18m, add the signed line to $28m CFO: $28m + (−$18m) = $10m. If you store capex as a positive $18m magnitude, subtract it: $28m − $18m = $10m. Never calculate $28m − (−$18m).
PP&E 购买为负数时,应相减还是相加?只能选择一种符号口径。若报表项目为 −1,800 万美元,就把带符号行加到 2,800 万 CFO:2,800 +(−1,800)= 1,000 万。若把资本开支存成正的 1,800 万绝对值,就做减法:2,800 −1,800 =1,000 万。绝不能写成 2,800 −(−1,800)。
First derive standalone quarters. Q2 equals six-month cumulative minus Q1; Q3 equals nine-month minus six-month; Q4 equals full year minus nine-month. Sum the latest four standalone CFO amounts and the matching four standalone PP&E purchase magnitudes, then subtract. Do not add overlapping cumulative columns.
如何从累计季度披露计算 TTM FCF?先还原独立季度:Q2 等于六个月累计减 Q1;Q3 等于九个月累计减六个月;Q4 等于全年减九个月。把最近四个独立季度的 CFO 与对应 PP&E 购买绝对值分别求和后相减,不能把重叠累计栏直接相加。
Not under this gross-purchase convention. ThermalLoop deducts $97m purchases and keeps $12m sale proceeds outside base FCF. Netting them would create $85m net capex and $53m FCF, a different labeled formula. Preserve both gross cash lines and state which convention is used.
资产出售所得应冲减资本开支吗?本页购买总额口径下不冲减。ThermalLoop 扣除 9,700 万购买,并把 1,200 万出售所得留在基础 FCF 外。若相抵,就会形成 8,500 万净资本开支与 5,300 万 FCF,属于另一项需标记的公式。应保留两项总额现金流并声明所选口径。
The answer depends on the disclosed definition. The base ticket deducts PP&E only, so $15m software is outside its $41m FCF. A separately labeled broader reinvestment view deducts software and equals $26m. Read the capitalization policy and use the same treatment across periods and peers.
资本化软件是否应计入自由现金流?取决于披露定义。基础工单只扣除 PP&E,因此 1,500 万软件支出不进入 4,100 万 FCF;另行标记的广义再投资视图扣除软件后为 2,600 万美元。应阅读资本化政策,并在各期和同业间保持处理一致。
ThermalLoop adds back $10m of discontinued-operation and restructuring cash use but deducts $23m of software and lease principal beyond the base formula. Thus $41m + $10m − $23m = $28m. Adjusted does not mean higher; it means differently defined, so the reconciliation controls interpretation.
为什么管理层调整后 FCF 低于简单计算?ThermalLoop 加回终止经营与重组现金占用合计 1,000 万美元,却在基础公式之外扣除软件与租赁本金合计 2,300 万美元。因此 4,100 +1,000 −2,300 =2,800 万美元。“调整后”不等于更高,只表示定义不同,解释必须服从调节表。
Primary sources for the FCF calculation inputs支持 FCF 计算输入的一手来源
The sources support cash-flow-statement structure, PP&E context, internal-use software context, and the SEC’s cautions that free cash flow lacks a uniform definition and should not imply unrestricted discretionary cash. Exact classification and disclosure requirements depend on framework, jurisdiction, facts, and effective dates. They do not validate fictional ThermalLoop.
This calculation ticket is educational, not accounting, audit, legal, tax, or individualized investment advice. FCF does not by itself establish maintenance needs, liquidity, solvency, valuation, distribution capacity, or future returns. Use complete current filings and qualified help when scope or classification is material.
以上来源支持现金流量表结构、PP&E 背景、内部使用软件背景,以及 SEC 关于自由现金流定义不统一、不得暗示全部为可自由支配现金的提醒。准确分类与披露要求取决于框架、司法辖区、事实和生效日期;这些来源不验证虚构 ThermalLoop。
本计算工单仅供学习,不构成会计、审计、法律、税务或个性化投资建议。FCF 不能单独证明维护需求、流动性、偿债能力、估值、分配能力或未来回报。若范围或分类影响重大,应使用完整当前披露并寻求合格专业帮助。
- SEC Division of Corporation Finance — Non-GAAP Financial Measures C&DIs
- SEC — Beginners’ Guide to Financial Statements
- FASB — Statement No. 95, Statement of Cash Flows
- IFRS Foundation — IAS 7 Statement of Cash Flows
- IFRS Foundation — IAS 16 Property, Plant and Equipment
- FASB — ASU 2018-15 Internal-Use Software Implementation Costs