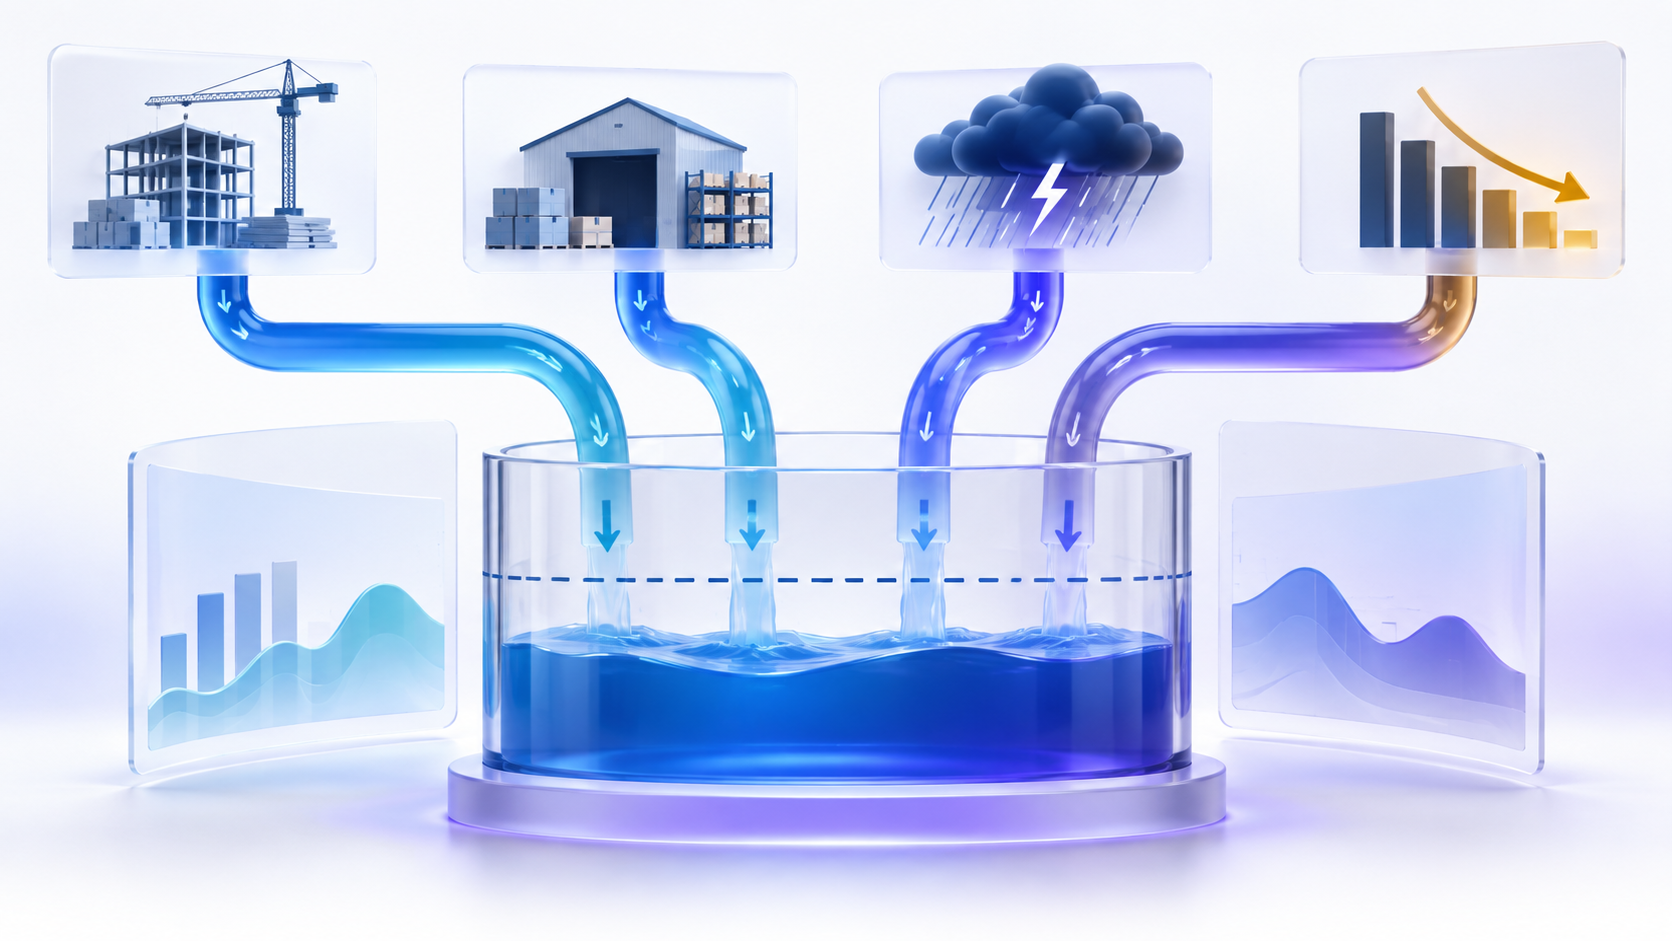
The direct answer: identify the negative line first直接答案:先确认哪一层为负
Negative operating cash flow means operations consumed cash during the stated period; negative investing cash flow means investing uses exceeded investing proceeds; negative financing cash flow means repayments, distributions, or other financing uses exceeded financing inflows; and a total cash decrease is the combined result, including any exchange-rate or scope adjustments. None is automatically good or bad. Diagnose the cause, map the funding source, compare available liquidity with unavoidable uses, and estimate a clearly defined cash runway. Then test whether the cause is temporary, repeatable, or deteriorating.
经营现金流为负,表示在所列期间内经营活动消耗现金;投资现金流为负,表示投资用途超过投资回收;融资现金流为负,表示还债、分配或其他融资用途超过融资流入;现金总额减少则是上述项目加上汇率或口径调节后的合计结果。任何一种都不能自动判定好坏。应继续判断原因、画出资金来源、把可用流动性与不可避免的用途比较,并按明确口径估算现金跑道,最后检验原因究竟是暂时、可重复还是持续恶化。
Triage four different meanings of “negative”先分诊四种不同的“负”
| What is negative? | Literal meaning | Question that changes the diagnosis |
|---|---|---|
| Operating cash flow (OCF) | Operating activities used more cash than they provided in the period | Was cash absorbed by growth or timing, or by weaker demand, collection, and margins? |
| Investing cash flow | Purchases and other investing uses exceeded sale proceeds and investing receipts | Does the spending add productive capacity, replace worn assets, acquire a business, or cover failed projects? |
| Financing cash flow | Debt repayment, dividends, repurchases, and other financing uses exceeded new funding | Was surplus cash returned, debt deliberately reduced, or financing withdrawn while cash was scarce? |
| Net change in cash | All classified flows and reconciling effects reduced the cash total | Which section caused the fall, and how much ending cash is unrestricted and available? |
| 哪一项为负? | 字面含义 | 会改变判断的问题 |
|---|---|---|
| 经营现金流(OCF) | 本期经营活动使用的现金超过其提供的现金 | 现金被增长和时点占用,还是需求、回款与利润率变弱? |
| 投资现金流 | 资产购买及其他投资用途超过处置与投资回收 | 支出是在增加有效产能、替换老旧资产、收购业务,还是为失败项目买单? |
| 融资现金流 | 偿债、股息、回购及其他融资用途超过新取得资金 | 是在返还剩余现金、主动降债,还是现金紧张时融资渠道收缩? |
| 现金净变动 | 全部分类现金流与调节影响使现金总额下降 | 下降由哪一部分造成,期末现金中多少不受限且真正可用? |
Keep period and scope aligned. A quarterly OCF deficit can sit inside positive full-year OCF for a seasonal operator. Consolidated cash can also hide cash trapped in subsidiaries or pledged to lenders. Start with the issuer’s reported subtotals, cash definition, and reconciliation; do not silently substitute free cash flow or an adjusted management measure for the line the question concerns.
期间和口径必须一致。季节性企业某一季度经营现金流为负,全年仍可能为正;合并现金也可能掩盖留在子公司或质押给贷款人的资金。应从发行人披露的小计、现金定义和调节表开始,不能悄悄用自由现金流或管理层调整指标替换正在讨论的现金流项目。
Classify the cause before deciding whether it is tolerable先给原因分类,再判断能否承受
New sites, equipment, acquisitions, launch inventory, or customer acquisition can consume cash before they contribute. Test approval gates, completion, utilization, and expected funding rather than assuming “growth” makes every outflow sound.
增长投入新场站、设备、收购、上市备货或获客可能先消耗现金、后产生贡献。应检查审批关口、完工、利用率与预期融资,不能因为冠以“增长”就认定所有流出都合理。
Receivables, inventory, contract assets, payables, and customer advances can move cash across periods. A timing explanation becomes credible only when billing terms, aging, subsequent collection, and reversal match it.
经营时点应收、存货、合同资产、应付和客户预付款会把现金在期间之间移动。只有开票条款、账龄、期后回款与反转情况相互吻合,“时点差异”才可信。
A predictable low season or construction cycle can create temporary deficits. Compare like-for-like quarters and a full cycle, then ask whether the current trough is deeper or longer than prior ones.
周期或季节性可预测的淡季或建设周期可能形成暂时缺口。应比较可比季度与完整周期,并判断本次低谷是否比过去更深或持续更久。
Cash settlements may lag the expense and recur after the announced program. Reconcile provisions, payments, remaining obligations, insurance recoveries, and repeated “one-time” programs.
重组、索赔或诉讼现金结算可能晚于费用确认,并在项目宣布后持续发生。应核对准备金、付款、剩余义务、保险赔偿,以及反复出现的所谓“一次性”项目。
Dividends, repurchases, and debt repayment can make financing cash flow negative. The key test is whether post-distribution liquidity and covenant headroom remain adequate for operations and commitments.
资本返还股息、回购与偿债会使融资现金流为负。关键是分配后流动性及契约余量能否覆盖经营和承诺。
Lower volumes, price pressure, cost overruns, slow collection, cancellations, and supplier tightening can create a deficit that does not self-correct. Look for several indicators pointing in the same direction.
经营恶化销量下降、价格压力、成本超支、回款放缓、取消订单及供应商收紧条款,可能形成不会自行修复的缺口。需要寻找多个方向一致的指标。
A planned receivable build can begin as growth timing and become operating deterioration if invoices age, customers dispute milestones, and borrowing replaces the missing collections. Preserve both the original explanation and the later evidence.
原因会跨类别变化计划中的应收增加起初可能属于增长时点,但若发票持续老化、客户争议里程碑、借款不断替代缺失回款,它就可能转为经营恶化。应同时保留最初解释与后续证据。
Map who finances the deficit and on what terms画出谁为缺口融资以及附带什么条件
| Funding source | What it can signal | Terms to verify |
|---|---|---|
| Opening unrestricted cash | Past funding is being consumed | Minimum operating balance, trapped cash, restrictions, and burn rate |
| Operating inflow from another segment or season | Internal cross-funding may bridge a planned trough | Segment seasonality, transfer limits, and recurrence |
| Customer advances or longer supplier terms | Stakeholders finance the operating cycle | Refund rights, performance obligations, supplier concentration, and reversibility |
| Asset sales | Capital is being recycled or liquidity raised | Asset productivity, carrying value, replacement needs, and recurrence |
| Debt facilities | Lenders bridge or permanently fund the gap | Committed availability, borrowing base, covenants, security, rate, maturity, and conditions to draw |
| Equity issuance | Owners absorb the deficit | Net proceeds, dilution, issuance conditions, and whether the operating cause changed |
| 资金来源 | 可能说明什么 | 必须核验的条款 |
|---|---|---|
| 期初不受限现金 | 过去取得的资金正在被消耗 | 最低经营现金、受困资金、限制与消耗速度 |
| 其他分部或旺季经营流入 | 内部交叉融资可能跨过计划低谷 | 分部季节性、转移限制与可重复性 |
| 客户预付款或延长供应商账期 | 利益相关方为经营周期提供资金 | 退款权、履约义务、供应商集中度与可逆性 |
| 出售资产 | 资本正在循环利用或为流动性变现 | 资产生产力、账面值、替换需求与可重复性 |
| 债务额度 | 贷款人暂时或长期填补缺口 | 承诺可用额、借款基础、契约、担保、利率、到期日与提款条件 |
| 发行权益 | 所有者承担资金缺口 | 净收入、稀释、发行条件以及经营原因是否改变 |
Quoted liquidity is not necessarily drawable liquidity. Subtract letters of credit and already used capacity; test borrowing-base limits and covenants at the projected low point; separate committed from uncommitted facilities. A funding source that expires before the cash use ends does not solve duration risk. A source that is available only after an asset sale or equity raise is a plan, not cash on hand.
披露的流动性不一定等于可以提款的流动性。应扣除信用证和已占用额度,在预计现金最低点测试借款基础和契约,并区分承诺额度与非承诺额度。若资金来源在现金用途结束前到期,就没有解决期限风险;必须先出售资产或发行权益才能获得的资金只是一项计划,并非手头现金。
Estimate runway without turning it into a forecast估算现金跑道,但不要把它当作预测
Indicative runway in months = (unrestricted cash + committed undrawn capacity currently available − minimum operating cash − near-term maturities excluded from burn) ÷ normalized recurring monthly cash burn. Show a cash-only version and a facility-inclusive version. If recurring burn is zero or positive, use a commitment-coverage schedule instead of forcing a runway number.
明确现金跑道公式指示性现金跑道(月)=(不受限现金+当前可用的承诺未提款额度−最低经营现金−未计入消耗速度的近期到期款)÷标准化后的每月重复现金消耗。应分别展示仅现金版本与包含授信版本。若重复消耗为零或现金净流入,则改用承诺覆盖表,不能强行计算跑道。
- Normalize with enough periods to include seasonality, but retain a downside case for weaker collection or margins.
- Include maintenance spending required to keep operations running; keep discretionary expansion separately visible.
- Do not count restricted cash, an uncommitted line, or a facility blocked by covenant or borrowing-base conditions.
- Recalculate after maturities, planned settlements, construction commitments, dividends, or policy changes.
- 用足够期间覆盖季节性,并保留回款或利润率更弱的下行情景。
- 纳入维持运营所必需的维护支出,把可裁减扩建支出另行列示。
- 不要把受限现金、非承诺额度或因契约与借款基础条件无法使用的额度算入。
- 出现到期债务、计划结算、建设承诺、股息或政策变化后重新计算。
Two scenarios: similar cash declines, different risk两个情景:相近的现金减少,不同的风险
PolarGate Cold Storage is fictional. The following are two independent illustrative full-year scenarios in CU millions, not consecutive years and not a real company’s data. Reported facts are invented for teaching; calculations follow those facts; interpretations remain conditional.
PolarGate Cold Storage 是虚构的冷库建设与运营商。以下是两个相互独立的完整年度情景,单位为 CU 百万,并非连续年度,也不对应真实公司。用于教学的已披露事实为虚构;计算以这些事实为基础;解释仍保留条件。
| Illustrative reported item | Controlled expansion | Collection breakdown |
|---|---|---|
| Operating cash flow | +24 | −24 |
| Investing cash flow | −72: new facilities −68; maintenance −4 | −8: maintenance −6; minor expansion −2 |
| Financing cash flow | +28: term-loan draw +40; repayment −12 | +10: revolving-credit draw |
| Net cash change | −20 | −22 |
| Opening / ending cash | 70 / 50 | 60 / 38 |
| Primary missing evidence | Build budget, committed funding, completion and occupancy | Receivable aging, disputes, subsequent receipts and covenant headroom |
| 演示性披露项目 | 受控扩建 | 回款失控 |
|---|---|---|
| 经营现金流 | +24 | −24 |
| 投资现金流 | −72:新设施 −68;维护 −4 | −8:维护 −6;小规模扩建 −2 |
| 融资现金流 | +28:定期贷款提款 +40;偿还 −12 | +10:循环额度提款 |
| 现金净变动 | −20 | −22 |
| 期初/期末现金 | 70/50 | 60/38 |
| 首要缺失证据 | 建设预算、承诺融资、完工与出租率 | 应收账龄、争议、期后收款与契约余量 |
In controlled expansion, arithmetic is 24 − 72 + 28 = −CU20m. OCF remains positive, and construction explains the deficit. The judgment improves only if CU50m ending cash is unrestricted, the remaining build is funded, cost overruns are contained, and new capacity can reach useful occupancy. Negative total cash here records a deliberate funding schedule; it does not prove the project is valuable.
在受控扩建情景中,算术为 24−72+28=−CU20。经营现金流仍为正,建设支出解释了缺口。只有当 CU50 期末现金不受限、剩余建设已获融资、成本超支受控且新产能可达到有效出租率时,判断才会改善。此处现金总额为负记录的是主动融资进度,并不能证明项目具有价值。
In the collection breakdown, arithmetic is −24 − 8 + 10 = −CU22m. Assume ending unrestricted cash is CU38m, currently available committed revolver capacity is CU12m, minimum operating cash is CU8m, a CU6m maturity is outside the burn estimate, and normalized recurring burn is CU2.5m per month: CU2.0m operating deficit plus CU0.5m maintenance spending. Cash-only runway is (38 − 8 − 6) ÷ 2.5 = 9.6 months. Facility-inclusive runway is (38 + 12 − 8 − 6) ÷ 2.5 = 14.4 months.
在回款失控情景中,算术为 −24−8+10=−CU22。假设期末不受限现金为 CU38、当前可用承诺循环额度为 CU12、最低经营现金为 CU8、另有 CU6 近期到期债务未计入消耗速度,标准化重复现金消耗为每月 CU2.5,其中经营缺口 CU2.0、维护支出 CU0.5。仅现金跑道=(38−8−6)÷2.5=9.6 个月;包含额度的跑道=(38+12−8−6)÷2.5=14.4 个月。
The 9.6- and 14.4-month figures are scenario outputs. Faster collection extends them; more disputes, covenant failure, cost inflation, or facility withdrawal shortens them. The adverse signal is not merely negative OCF, but negative OCF financed by a shrinking, conditional debt source while receivables remain unresolved.
这是解释,不是预测9.6 和 14.4 个月只是情景结果。加快回款会延长跑道;更多争议、契约违约、成本上涨或额度撤回会缩短跑道。不利信号不只是经营现金流为负,而是应收问题未解决时,只能依赖不断缩小且附条件的债务来源来融资。
Write a diagnosis that can change with evidence写出能够随证据更新的诊断
- Name the negative subtotal, period, currency, units, cash scope, and exact amount.
- Assign a primary and secondary cause; state the reported evidence and the strongest alternative explanation.
- Map every funding source to availability, conditions, cost, maturity, and remaining capacity.
- Calculate cash-only and facility-inclusive coverage under a base and downside burn assumption.
- Choose the next deciding evidence: collection, occupancy, capex completion, settlement, covenant test, refinancing, or distribution change.
- 写明为负的小计、期间、币种、单位、现金口径和准确金额。
- 指定主要与次要原因,同时写出披露证据和最强替代解释。
- 把每项资金来源连接到可用性、条件、成本、期限和剩余额度。
- 在基准与下行消耗假设下,分别计算仅现金和包含额度的覆盖时间。
- 选择下一项决定性证据:回款、出租率、资本项目完工、结算、契约测试、再融资或分配变化。
A defensible conclusion is conditional: “PolarGate’s expansion scenario shows a funded investing deficit with positive OCF, subject to completion and occupancy. Its collection scenario shows an operating deficit with less than one year of cash-only runway under stated assumptions, making receivable resolution and revolver availability decisive.” This says what is known, what was calculated, and what could reverse the view.
可辩护结论应带条件:“PolarGate 扩建情景显示投资缺口已有融资且经营现金流为正,但仍取决于完工和出租率;回款情景显示经营缺口,按所列假设,仅现金跑道不足一年,因此应收解决与循环额度可用性具有决定作用。”这段话同时说明已知事实、计算结果以及可能推翻判断的证据。
Build a funding diagnosis from uploaded liquidity evidence从上传的流动性证据建立资金诊断
InfiniSynapse operates Stock Explained and publishes this page. Upload comparable cash flow statements, balance sheets, cash and restricted-cash notes, receivable aging, capital commitments, construction budgets, debt maturity schedules, credit agreements, covenant disclosures, customer-advance notes, supplier-finance terms, and management’s liquidity discussion. Ask the tool to separate each negative subtotal, cause, funding source, and duration assumption with source pages.
Use the output as a review map, not a solvency score. Verify every number, sign, facility term, covenant, quotation, and page reference against the uploaded original; independently recompute net cash change and both runway versions. Leave missing agreements and conditional funding visibly unresolved. Do not assume the workflow retrieves complete filings, current balances, or lender decisions that were not provided.
InfiniSynapse 运营“一眼看懂这只股票”并发布本页。可上传可比现金流量表、资产负债表、现金与受限现金附注、应收账龄、资本承诺、建设预算、债务到期表、授信协议、契约披露、客户预付款附注、供应链融资条款及管理层流动性讨论;要求工具按来源页码分开记录每项负数小计、原因、资金来源与期限假设。
输出只应作为复核地图,而不是偿付能力评分。每个数字、正负号、授信条款、契约、引文与页码都要回到上传原件核验,并独立复算现金净变动和两种跑道。缺失协议与附条件融资必须保持未决。不要假设该工作流会取得未提供的完整披露、当前余额或贷款人决定。
Upload cash flow, debt, commitment, and liquidity notes; identify the negative layer and verify every runway input before drawing a conclusion.
上传现金流、债务、承诺与流动性附注,确认负数出现在哪一层,并在得出结论前核验每项跑道输入。
Open Stock Explained打开“一眼看懂这只股票”Questions after a negative-cash-flow diagnosis完成负现金流诊断后的常见问题
It can reflect productive expansion or necessary asset renewal, but the negative sign alone says only that investing uses exceeded receipts. Test project economics, completion risk, maintenance needs, utilization, and funding. Overbuilding or an overpriced acquisition also creates negative investing cash flow.
投资现金流为负可能是积极信号吗?它可能来自有效扩建或必要资产更新,但负号本身只说明投资用途超过回收。仍要检验项目经济性、完工风险、维护需求、利用率与融资。过度建设或高价收购同样会形成负投资现金流。
There is no universal count. A seasonal or development-stage model may have planned deficits, while one severe period can matter if liquidity is thin. Compare a full business cycle, the cause, trend, funding conditions, and evidence of reversal rather than applying a fixed threshold.
经营现金流连续负多少期才危险?没有通用次数。季节性或开发阶段模式可能计划性消耗现金,而流动性薄弱时,一个严重期间就可能重要。应比较完整经营周期、原因、趋势、融资条件与反转证据,而不是套用固定阈值。
No. Include only capacity that is committed and currently drawable under borrowing-base, covenant, collateral, and other conditions. Deduct letters of credit and used amounts. Show cash-only runway separately because lenders may not renew a facility or may restrict access later.
未提款授信是否总应计入现金跑道?不是。只能纳入承诺且在借款基础、契约、担保及其他条件下当前可提款的额度,并扣除信用证和已使用金额。还应单列仅现金跑道,因为贷款人以后可能不续期或限制提款。
A cash-generative company may repay debt, pay dividends, or repurchase shares without replacement financing. That can produce negative financing cash flow. Strength depends on post-payment liquidity, obligations, covenant headroom, and whether operating cash generation is durable—not on the subtotal alone.
为什么融资现金流为负仍可能与财务稳健并存?现金创造充足的公司可能用现金偿债、支付股息或回购,而不取得替代融资,因此融资现金流为负。是否稳健取决于付款后的流动性、义务、契约余量与经营现金持续性,而不是该小计本身。
Receivables continuing to age, rising disputes or credit losses, repeated covenant relief, customer cancellations, and weak subsequent receipts would weaken it. A documented collection after period-end and normalization of aging would support timing, provided the cash was not replaced by factoring or extended customer terms.
什么证据会推翻“只是回款时点”的解释?应收继续老化、争议或信用损失增加、反复获得契约豁免、客户取消以及期后收款疲弱,都会削弱该解释。若期后确实收回款项且账龄正常化,则支持时点解释,但还要确认现金并非来自保理或延长客户条款。
Primary sources and diagnostic boundary第一手来源与诊断边界
The SEC guide and IAS 7 support the distinction among operating, investing, and financing cash flows. SEC liquidity guidance emphasizes cash requirements, funding sources, commitments, trends, and covenants. FASB ASU 2014-15 supplies U.S. GAAP going-concern disclosure context. These sources do not prescribe this page’s cause classifier or runway formula.
PolarGate and all figures, facilities, and scenarios are fictional. Runway is highly sensitive to burn normalization, minimum cash, facility access, maturities, and management actions; it is not a forecast. This diagnosis is not an audit, solvency opinion, individualized investment advice, or prediction of returns.
SEC 指南和 IAS 7 支持经营、投资与融资现金流的区分。SEC 流动性指引强调现金需求、资金来源、承诺、趋势与契约;FASB ASU 2014-15 提供美国通用会计准则下持续经营披露背景。这些来源并未规定本文的原因分类或现金跑道公式。
PolarGate 及所有数字、授信和情景均为虚构。现金跑道对消耗速度标准化、最低现金、额度可用性、到期债务与管理行动高度敏感,不能当作预测。本诊断不构成审计、偿付能力意见、个性化投资建议或收益预测。
- U.S. Securities and Exchange Commission — Beginners’ Guide to Financial Statements
- IFRS Foundation — IAS 7 Statement of Cash Flows
- U.S. Securities and Exchange Commission — Financial Reporting Manual, Topic 9
- U.S. Securities and Exchange Commission — MD&A Guidance, Release FR-72
- Financial Accounting Standards Board — ASU 2014-15, Going Concern