Understanding begins when you can draw the business能把生意画出来,才算开始看懂
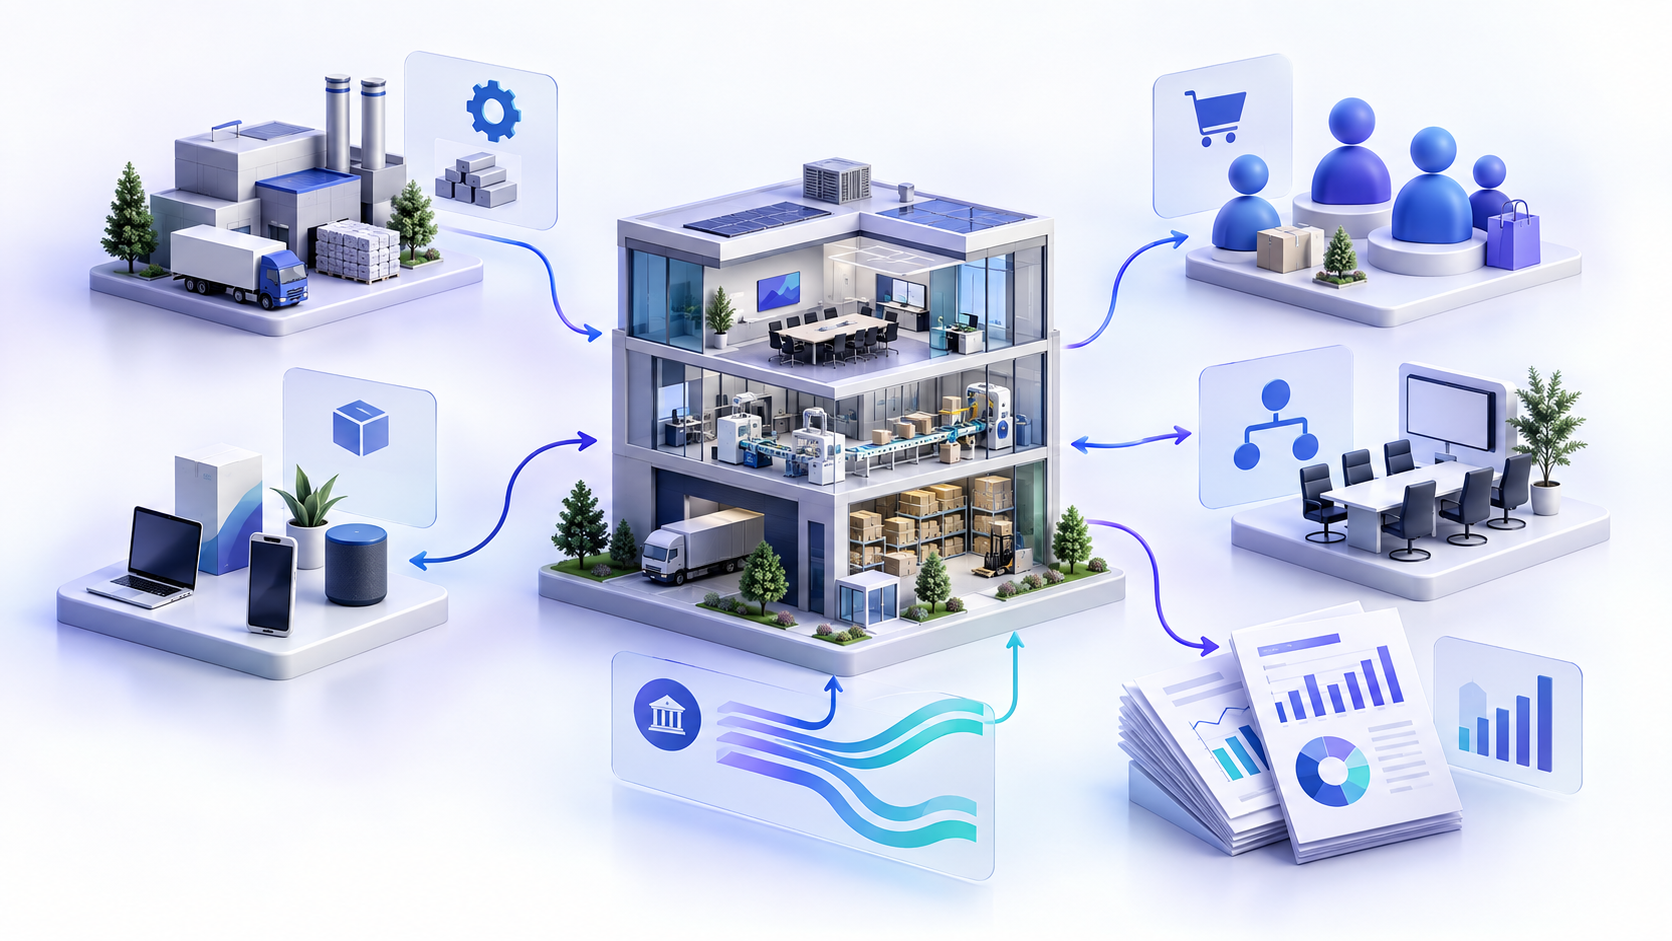
To understand a company before investing, build a company map before using valuation ratios. Mark the legal entities you are buying into, the customer’s reason to pay, the company’s position between suppliers and users, the event that turns an order into reported revenue, the cash-collection point, the costs that cannot shrink quickly, and the financing needed to bridge those events. Then describe how the system fails. If the map cannot connect a customer promise to revenue, cash, and shareholder claims using primary disclosures, the company is not yet understood.
投资前看懂一家公司,第一步不是套估值倍数,而是画出公司地图:你买入权益对应哪些法律主体,客户为什么付款,公司位于供应商与最终用户之间的哪一段,订单在什么事件发生后变成收入,现金何时真正收回,哪些成本无法迅速缩减,以及这些时点之间需要什么融资。最后还要画出系统如何失败。若无法利用原始披露把一项客户承诺连接到收入、现金和股东权益,就还没有真正看懂这家公司。
Draw the boundary of the company you would own先画清你将拥有的公司边界
A brand is not necessarily the listed company. Begin with the issuer’s legal name, exchange symbol, reporting date, fiscal year-end, and reporting currency. Then identify material subsidiaries, joint ventures, non-controlling interests, and businesses classified for sale. Ask which entity signs customer contracts, owns intellectual property, carries debt, employs people, and holds cash. Consolidated statements combine controlled entities, but economics can still be trapped by minority ownership, local restrictions, guarantees, or lender claims.
品牌名称不一定等于上市主体。先记录发行人的法律名称、交易代码、报告日期、财政年度截止日和报告币种,再识别重要子公司、合营安排、非控股权益以及被分类为待售的业务。逐一追问:哪个主体与客户签约,哪个主体持有知识产权,债务由谁承担,员工受雇于谁,现金又留在哪里。合并报表会把受控主体汇总起来,但经济利益仍可能受到少数股东、本地限制、担保或贷款人权利的约束。
| Map layer | Question to write down | Primary-document location |
|---|---|---|
| Ownership perimeter | What exact equity claim does the listed share represent? | Cover page, organization note, subsidiary exhibit, equity note |
| Operating perimeter | Which entities make, sell, install, finance, or service the offer? | Business section, segment note, geographic disclosures |
| Claim perimeter | Who has a contractual claim ahead of common shareholders? | Debt, lease, pension, commitments, guarantees, and preferred-equity notes |
| Time perimeter | What changed after the latest annual reporting date? | Later quarterly and current filings, dated issuer releases |
| 地图层 | 要写下的问题 | 原始披露位置 |
|---|---|---|
| 所有权边界 | 上市股票究竟代表哪一项权益请求权? | 封面、组织架构附注、子公司附件、权益附注 |
| 经营边界 | 哪些主体负责生产、销售、安装、融资或售后服务? | 业务章节、分部附注、地区披露 |
| 请求权边界 | 哪些合同权利排在普通股东之前? | 债务、租赁、养老金、承诺、担保及优先权益附注 |
| 时间边界 | 最近年度报告日之后发生了什么变化? | 之后的季度与重大事项申报、注明日期的公司公告 |
If a presentation describes a fast-growing operation, confirm that the listed shareholders own its economics and that the same operation is included in the reported segment figures. Similar names and shared branding are not sufficient evidence.
边界核对若演示材料突出一个高速增长业务,要确认上市公司股东确实拥有其经济利益,并确认该业务包含在所披露的分部数字中。名称相似或共用品牌并不能构成充分证据。
Replace the product list with a customer promise别抄产品清单,改写客户承诺
Product descriptions tell you what is sold; a customer promise explains why money changes hands. Name the economic customer, user, purchasing approver, and payer—they may differ. State the costly problem, credible alternative, pricing basis, commitment length, and evidence of renewal or repeat purchase. This turns vague demand claims into observable behavior.
产品说明只告诉你卖什么,客户承诺才解释钱为什么会转手。分别识别经济客户、实际用户、采购批准者和付款者,因为它们可能不同。写清代价高昂的问题、可信替代方案、定价依据、承诺期,以及续约或重复购买证据,把笼统需求转成可观察行为。
What event causes the buyer to act now—capacity shortage, regulation, equipment failure, a new site, or a scheduled replacement cycle?
触发器什么事件让买方必须现在行动:产能短缺、合规要求、设备故障、新场地启用,还是计划内更换周期?
Can the customer buy from a rival, perform the work internally, postpone it, repair an older asset, or accept the problem? The real competitor may be inaction.
选择客户能否选择竞争对手、自行完成、推迟采购、维修旧资产,或暂时忍受问题?真正的竞争者有时是什么也不做。
Which disclosed measure would change if the promise is valued: unit volume, installed base, utilization, backlog conversion, contract duration, retention, or price per unit?
证明如果客户确实重视这项承诺,哪个披露指标会变化:销量、装机量、利用率、积压订单转化、合同期限、留存率,还是单位价格?
Which party captures the value before it reaches shareholders—suppliers, distributors, employees, landlords, lenders, tax authorities, or a platform owner?
价值流失价值到达股东之前,会被哪一方获取:供应商、分销商、员工、房东、贷款人、税务机关,还是平台所有者?
Locate the company inside the value chain确定公司在价值链中的位置
Draw arrows from critical input to supplier, company activity, channel, payer, and end use. Mark who owns inventory and bears defects, delays, returns, and customer credit. A distributor can report large sales with little bargaining power; an asset-light service provider can depend on scarce technicians; a manufacturer can finance components months before collection. The map reveals where negotiating power and cash exposure sit.
从关键投入开始画箭头,依次连接供应商、公司活动、渠道、付款者和最终用途,并标出谁拥有存货、承担缺陷、延期、退货和信用风险。分销商可能收入很大却缺少议价权;轻资产服务商可能依赖稀缺技术人员;制造商可能在收款前数月垫付零部件。地图由此揭示议价权与现金暴露的位置。
| Link to inspect | Healthy-looking evidence | Contrary question |
|---|---|---|
| Supplier → company | Input prices fell | Is the benefit contracted away to customers, or offset by minimum purchases? |
| Company → channel | Shipments to distributors rose | Did end users buy the goods, or did channel inventory merely increase? |
| Company → customer | Backlog expanded | Can orders be cancelled, repriced, delayed, or fulfilled at an unattractive margin? |
| Customer → cash | Reported revenue grew | Did receivables, contract assets, or collection days grow faster? |
| 要检查的连接 | 表面上的正面证据 | 必须追问的反向问题 |
|---|---|---|
| 供应商 → 公司 | 投入价格下降 | 好处是否通过合同让给客户,或被最低采购承诺抵消? |
| 公司 → 渠道 | 向分销商出货增加 | 终端用户真的买走了吗,还是渠道库存只是上升? |
| 公司 → 客户 | 积压订单扩大 | 订单能否取消、重定价、延期,或只能以很差的利润率履约? |
| 客户 → 现金 | 报告收入增长 | 应收款、合同资产或回款天数是否增长得更快? |
PolarSpan case: one order, five different clocksPolarSpan 案例:一张订单上的五只时钟
PolarSpan Thermal Services is a fictional cold-chain equipment company created for this lesson, not a real issuer. It buys refrigeration modules, configures them for pharmaceutical warehouses, installs the systems, and sells remote-monitoring service. The illustrative contract covers ten systems. The following “reported facts” are invented terms presented as though extracted from a contract summary: equipment price $150,000 per system; installation $20,000 per system; monitoring $12,000 per installed system per year; a 20% equipment deposit at order; and supplier module cost of $96,000 per system due before delivery.
PolarSpan Thermal Services 是为本教程虚构的冷链设备企业,并非真实发行人。它采购制冷模块,为医药仓库完成配置与安装,并销售远程监测服务。演示合同包含十套系统。以下“披露事实”均为虚构条款,假定来自合同摘要:每套设备价格 15 万美元;每套安装费 2 万美元;每套已安装系统每年监测费 1.2 万美元;下单时收取设备价款的 20% 作为定金;供应商模块成本为每套 9.6 万美元,并在交货前支付。
| Illustrative event | Commercial meaning | Accounting / cash treatment used in this example |
|---|---|---|
| Day 0: signed order | Customer commits subject to contract terms | Order value is not automatically revenue; $300,000 deposit cash is received and recorded as a contract liability in this illustration. |
| Day 30: modules paid | PolarSpan funds production before acceptance | $960,000 supplier cash payment for ten modules; no customer equipment revenue yet. |
| Day 75: delivery and acceptance | Control of equipment transfers under the assumed contract | $1.5m equipment revenue is recognized; the remaining $1.2m is invoiced, subject to actual policy and collectability. |
| Day 105: equipment invoice collected | Credit exposure ends for the equipment balance | $1.2m cash receipt; collection is not new revenue because revenue was recognized at acceptance in this example. |
| Day 120: installation accepted | A separate promised service is completed | $200,000 installation revenue and invoice under the illustrative assumptions. |
| Following 12 months: monitoring | Stand-ready service is delivered over time | $120,000 total monitoring revenue recognized across the service period, not entirely at contract signing. |
| 演示事件 | 商业含义 | 本例采用的会计 / 现金处理 |
|---|---|---|
| 第 0 天:签署订单 | 客户按合同条款作出承诺 | 订单金额不会自动成为收入;本例收到 30 万美元定金现金,并记为合同负债。 |
| 第 30 天:支付模块款 | PolarSpan 在客户验收前为生产垫资 | 十套模块支付 96 万美元供应商款;此时尚无客户设备收入。 |
| 第 75 天:交付并验收 | 按照本例合同假设,设备控制权转移 | 确认 150 万美元设备收入;剩余 120 万美元开票,实际处理仍取决于会计政策和可收回性。 |
| 第 105 天:收回设备尾款 | 设备应收款对应的信用暴露结束 | 收到 120 万美元现金;本例收入已在验收时确认,因此回款不会再次形成收入。 |
| 第 120 天:安装验收 | 一项单独承诺的服务完成 | 按照演示假设,确认并开票 20 万美元安装收入。 |
| 之后 12 个月:监测服务 | 持续待命服务随时间履行 | 12 万美元监测收入在服务期内确认,而非签约时一次确认。 |
Calculation, not a reported fact: just before delivery, the simple equipment cash bridge is $960,000 supplier payment minus $300,000 customer deposit = $660,000, before payroll, freight, tax, and other costs. Interpretation: the business can grow orders and still consume financing because supplier cash precedes customer acceptance and final collection. Missing evidence includes cancellation rights, refundability, acceptance clauses, bad-debt history, supplier terms, inventory ownership, and whether installation is truly a separate performance obligation.
以下是研究者计算,并非披露事实:在设备交付前,简单的设备资金桥为 96 万美元供应商付款减去 30 万美元客户定金,即 66 万美元;其中尚未包括工资、运费、税费和其他成本。判断是:即使订单增长,业务仍可能消耗融资,因为供应商付款早于客户验收与尾款回收。缺失证据包括取消权、定金是否可退、验收条款、坏账历史、供应商账期、存货所有权,以及安装是否确实属于单独履约义务。
The revenue timing above is an illustrative assumption, not a universal rule. Real treatment depends on the contract, applicable accounting standards, performance obligations, transfer of control, estimates, and the company’s disclosed policy. The analytical lesson is to keep order, revenue, invoice, and cash dates separate.
假设边界以上收入时点只是演示假设,并非普遍规则。真实处理取决于合同、适用会计准则、履约义务、控制权转移、估计以及公司披露的会计政策。分析重点是始终把订单、收入、开票和现金日期分开。
Add the costs that cannot leave and the cash that must arrive把撤不掉的成本与必须到位的现金加进地图
Classify costs by behavior rather than by income-statement label. A module purchase may vary with delivered systems; certified technicians, a monitoring center, warehouse leases, software maintenance, and minimum supplier commitments may persist when orders slow. Separate capacity cost from unit cost and note the time required to remove each commitment. A high reported gross margin does not protect shareholders if fixed operating capacity, interest, and required maintenance absorb the remaining cash.
成本应按行为分类,而不只是照抄利润表名称。模块采购可能随交付套数变化;认证技术人员、监控中心、仓库租赁、软件维护和供应商最低采购承诺,则可能在订单放缓后仍持续。把单位成本和产能成本分开,并记录解除每项承诺需要多长时间。即使报告毛利率很高,若固定经营产能、利息和必要维护吞噬剩余现金,股东也得不到保护。
Customer triggers disappear, but field teams, sites, and systems remain. Look for break-even volume, backlog quality, cancellation rights, and the speed at which capacity can be reduced.
销量失败客户触发需求消失,但现场团队、场地和系统仍然存在。要查找盈亏平衡销量、积压订单质量、取消权,以及产能能够缩减的速度。
Orders exist, but components, certification, labor, or acceptance delays prevent delivery. Revenue, invoicing, and collections move later while operating commitments continue.
履约失败订单存在,但零部件、认证、人工或验收延迟阻碍交付。收入、开票和回款向后推移,经营承诺却继续发生。
The company ships more but discounts, warranty work, freight, channel fees, or service labor capture the benefit. Test contribution per unit rather than celebrating sales alone.
经济性失败公司出货增加,但折扣、保修、运费、渠道费用或服务人工拿走了收益。应检验每单位贡献,而不是只庆祝销售增长。
Profitable contracts still require cash before collection. Map deposits, supplier terms, inventory days, receivables, debt maturities, covenants, leases, and potential dilution.
融资失败即使合同有利润,企业仍可能在回款前需要现金。应画出定金、供应商账期、库存天数、应收款、债务到期、契约、租赁与潜在稀释。
Finish with a seven-sentence company map用七句话完成公司地图
- We would own a claim on [legal issuer and material operating entities], behind [senior contractual claims].
- The economic customer pays because [costly problem or desired outcome], and can instead [credible alternative].
- The company controls [specific value-chain activity] but depends on [supplier, channel, labor, license, or geography].
- An order becomes reported revenue when [disclosed recognition event], while cash is normally collected [payment timing].
- Growth requires [inventory, equipment, people, credit, or acquisition spending], funded by [internal cash, deposits, debt, or equity].
- The system fails first if [volume, execution, economics, or financing mechanism] breaks.
- The most important missing fact is [named disclosure], which should appear in [specific filing, note, or future operating update].
- 我们拥有的是对【法律发行主体及重要经营主体】的权益请求权,排在【优先合同请求权】之后。
- 经济客户付款,是因为【代价高昂的问题或希望获得的结果】,其可信替代方案是【替代选择】。
- 公司控制价值链中的【具体活动】,但依赖【供应商、渠道、劳动力、许可或地区】。
- 订单在【披露的确认事件】发生时成为报告收入,而现金通常在【付款时点】收回。
- 增长需要投入【存货、设备、人员、信用或收购支出】,资金来自【内部现金、定金、债务或股权】。
- 如果【销量、履约、经济性或融资机制】失效,整个系统会首先在这里断裂。
- 最重要的缺失事实是【明确披露项】,预计可在【具体申报文件、附注或未来经营更新】中找到。
Every bracket must be filled with evidence or marked unknown. Do not decorate an unknown with a management slogan. Once the seven sentences are defensible, financial analysis has context and valuation can begin. Until then, a low multiple may describe hidden fragility, while a high growth rate may describe cash-hungry activity that belongs economically to suppliers or lenders.
每个括号都必须由证据填入,或明确标为未知。不要用管理层口号装饰未知项。只有当七句话都能被证据支撑时,财务分析才有语境,估值才适合开始。在此之前,较低倍数可能反映隐藏的脆弱性,较高增长率也可能只是大量消耗现金、经济利益更多流向供应商或贷款人的活动。
Assemble a multi-document company map with AI用 AI 整理多文档公司地图
Prepare documents by role, not as one undifferentiated upload: the latest annual filing for identity and business structure; later interim and current filings for recency; the segment, revenue-policy, debt, commitments, subsidiary, and customer-concentration notes; and any investor material used only for operating context. Ask for a map of entities, counterparties, contractual events, revenue triggers, payment timing, cost commitments, financing links, and missing disclosures. Require every important statement to carry a source filename, reporting period, page or note, and evidence status.
Use InfiniSynapse Stock Explained to organize the submitted material into a draft that you can interrogate, not as an authority that fills gaps. Verify every material entity relationship, number, date, contract term, accounting conclusion, and risk statement against the uploaded original disclosure. Check surrounding footnotes and recalculate any derived amount. If documents conflict, a table is unreadable, or the output cannot point to its source, preserve the conflict as unresolved instead of choosing the smoother narrative.
准备文件时应按用途分组,而不是全部混成一次上传:用最新年报确认主体与业务结构;用之后的阶段性和重大事项申报补足时效;单独标出分部、收入政策、债务、承诺、子公司和客户集中附注;投资者材料只用于补充经营语境。要求工具生成主体、交易对手、合同事件、收入触发、付款时点、成本承诺、融资连接和缺失披露地图,并给每项重要表述附上文件名、报告期间、页码或附注号及证据状态。
可用 InfiniSynapse“一眼看懂这只股票”把提交资料整理成便于追问的草稿,但不能让工具自行填补空白。每个重要主体关系、数字、日期、合同条款、会计判断和风险表述,都必须回到上传的原始披露中核验;同时阅读上下文附注,并复算所有衍生数字。如果文档相互冲突、表格无法辨认,或输出不能定位来源,就保留“未决”状态,不能选择更顺耳的叙述。
Bring the annual filing, later updates, relevant notes, and one customer-to-cash question you want the documents to answer.
准备年度申报、之后的更新、相关附注,以及一个希望文档回答的“客户到现金”问题。
Open Stock Explained打开“一眼看懂这只股票”Questions raised by the company map公司地图画完后常见的问题
Not automatically. An order may indicate a contract or backlog, while revenue recognition depends on the promised goods or services, performance obligations, transfer of control, applicable standards, estimates, and the company’s accounting policy. Payment can occur before or after revenue. Read the revenue note and contract terms.
签署订单就等于确认收入吗?不一定。订单可能代表合同或积压订单,收入确认还取决于承诺的商品或服务、履约义务、控制权转移、适用准则、估计以及公司的会计政策。付款既可能早于收入,也可能晚于收入。必须阅读收入附注与合同条款。
Separate user, purchaser, economic beneficiary, and payer. Trace the contract, invoice, channel arrangement, and end use. If a distributor buys inventory, determine whether disclosed demand reflects distributor shipments or end-customer consumption, and who bears return and credit risk.
如何判断谁才是真正的客户?把用户、采购者、经济受益者和付款者分开,再沿合同、发票、渠道安排和最终用途追踪。如果分销商购入存货,要判断披露的需求究竟是向分销商出货,还是终端客户消耗,并确认谁承担退货与信用风险。
Growth can require inventory, supplier prepayments, equipment, hiring, installation, and customer credit before cash is collected. Map the amount and timing of each commitment. Profitable accounting revenue does not remove a timing gap, and deposits help only to the extent they are available and not refundable.
为什么增长中的公司仍会缺现金?增长可能要求企业在收款前先投入存货、供应商预付款、设备、招聘、安装和客户信用。应分别标出每项承诺的金额与时点。会计上有利润的收入不会消除时间缺口;客户定金也只有在可以使用且无需退款的范围内提供帮助。
Mark it as missing and avoid creating false precision. Look for a segment note, contract-balance disclosure, later filing, regulator submission, or consistently defined issuer metric. If the measure remains unavailable, narrow the conclusion to what reported evidence supports and state what cannot be known.
如果年报没有披露我需要的经营指标怎么办?把它标为缺失,不要制造虚假精度。继续查看分部附注、合同余额披露、后续申报、监管文件或公司持续一致定义的指标。若仍不可得,就把结论缩小到报告证据能够支持的范围,并明确哪些事情无法知道。
Move on when you can defend the seven-sentence map with primary sources, distinguish orders from revenue and cash, identify rigid costs and funding gaps, and describe a concrete failure route. Valuation still requires separate assumptions about future performance, risk, dilution, and the price input’s date.
什么时候可以从理解公司进入估值?当你能用原始资料支撑七句公司地图,分清订单、收入与现金,识别刚性成本和资金缺口,并描述一条具体失败路径时,才适合继续。估值仍需另行处理未来表现、风险、稀释以及价格输入日期等假设。
Primary references and boundaries一手参考资料与边界
The filing references above focus mainly on U.S. public companies, while IFRS 15 supplies an international standard-setting reference for revenue from customer contracts. Use the regulator, filing forms, and accounting framework applicable to the actual issuer. PolarSpan, its contract, chronology, prices, costs, and cash bridge are entirely fictional teaching material.
A company map supports understanding; it does not establish fair value, suitability, or future return. Even a well-understood operation can be financed poorly, purchased at an unfavorable price, or unsuitable for a particular investor’s horizon, liquidity needs, diversification, taxes, and capacity for loss.
以上申报资料主要面向美国上市公司,IFRS 15 则提供客户合同收入的国际准则制定机构参考。研究真实发行人时,应使用其所在市场适用的监管机构、申报形式和会计框架。PolarSpan、其合同、时间线、价格、成本和资金桥均为虚构教学材料。
公司地图只能帮助理解业务,不能直接确定公允价值、个人适配性或未来回报。即使经营模式已经看懂,公司仍可能融资不当、买入价格不利,或不适合某位投资者的期限、流动性需求、分散安排、税务与承受损失能力。