Use AI for assembly; use controls for acceptance让 AI 负责组装,让控制负责验收
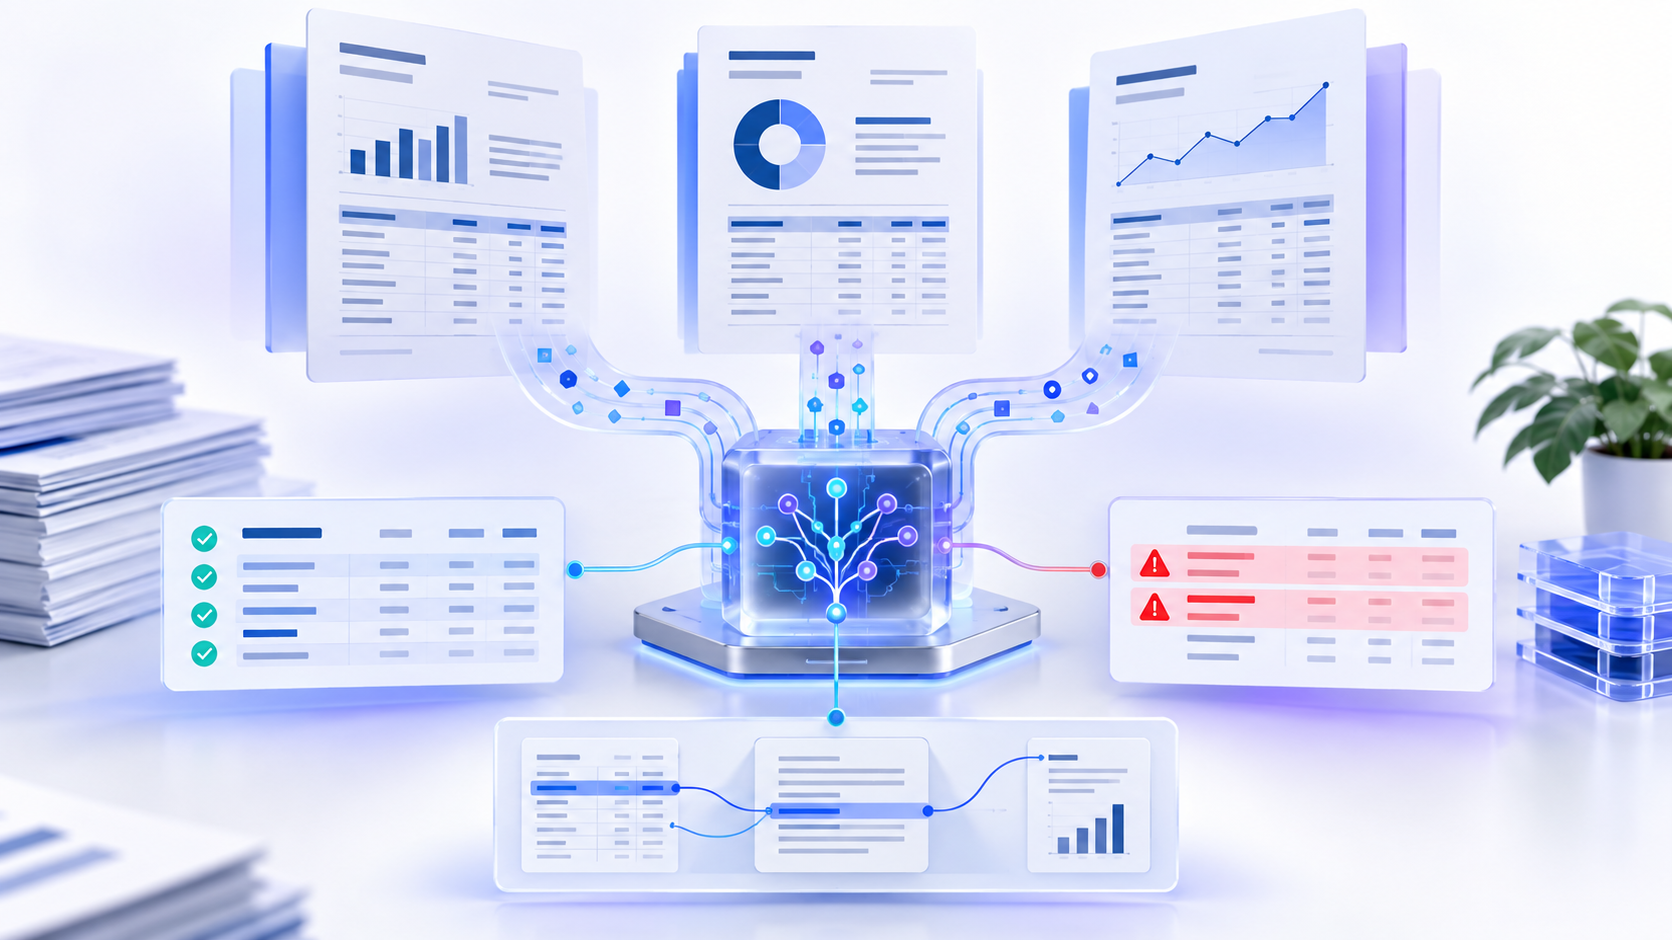
A reliable AI financial statement workflow has three lanes. The draft lane inventories the package, confirms searchable text or flags OCR, and extracts statements and relevant notes with page-level provenance. The control lane normalizes currency, units, signs, periods, scope, and reclassifications; then tests Assets = Liabilities + Equity, beginning cash + net cash movement + exchange effect = ending cash, and net income against cash-flow and equity roll-forwards. Ratios use only approved normalized cells. The correction lane returns each failure to the original page, preserves the before/after record, and separates reported facts, calculations, assumptions, judgments, and gaps. InfiniSynapse operates Stock Explained, which organizes a plain-language stock brief from user-provided files and text. It does not replace source filings or accountants, guarantee extraction accuracy, or provide a real-time market-data service.
可靠的 AI 财务报表工作流有三条线。草稿线先清点上传的年报或季报包,确认文件有可搜索文字层,否则标记 OCR 风险,再从利润表、资产负债表、现金流量表、权益变动表与相关附注抽取数字,并保留页级来源。控制线统一币种、单位、正负号、期间、合并范围与重分类,然后检验“资产=负债+权益”、“期初现金+现金净变动+汇率影响=期末现金”,并把净利润与现金流调节和权益滚动连接;比率只能引用已批准的规范化单元格。纠错线把每个失败控制带回原页,修正数值或分类,保留修改前后记录,并分开报告事实、计算、假设、判断与缺失信息。InfiniSynapse 运营 Stock Explained;它依据用户提供的文件与文本整理通俗股票说明。它不能替代原始申报或会计师,不保证抽取自动准确,也不应被当作实时市场数据服务。
Before analysis, make the file package auditable分析前,先让文件包可审计
| Manifest field | Why it controls the AI draft | Reject or flag when |
|---|---|---|
| Entity and consolidation scope | Prevents parent-only figures from mixing with consolidated statements | Legal entity, subsidiaries, or continuing-operation scope is unclear |
| Exact period and statement type | Separates a fiscal year, quarter, year-to-date column, and point-in-time balance | A flow period is compared with the wrong duration or balance date |
| Currency and displayed unit | Distinguishes dollars, thousands, and millions before arithmetic | The unit appears once in a header and extraction omitted it |
| Document version and filing date | Keeps an amendment or recast from competing with the original | Two versions exist without a declared authority |
| Text layer and page image | Searchable text supports location; the rendered page confirms columns and signs | The scan is unreadable, cropped, or has no reviewable original |
| Audit/review status | Prevents an AI summary from upgrading the assurance attached to a source | The package mixes audited annual and unaudited interim numbers silently |
| 清单字段 | 为何能控制 AI 草稿 | 何时拒绝或标记 |
|---|---|---|
| 主体与合并范围 | 防止母公司单体数字与合并报表混合 | 法律主体、子公司或持续经营范围不清 |
| 准确期间与报表类型 | 区分财政年度、单季、年初至今列与时点余额 | 期间流量和错误时长或资产负债表日比较 |
| 币种与显示单位 | 算术前区分元、千元与百万元 | 单位只在表头出现一次,而抽取遗漏 |
| 文件版本与申报日期 | 避免修订版或重列版和原版竞争 | 存在两个版本却未声明权威版本 |
| 文字层与页面图像 | 可搜索文字用于定位,渲染页面用于确认列和正负号 | 扫描不可读、裁切或没有可复核原件 |
| 审计/审阅状态 | 防止 AI 摘要提高来源原有的保证程度 | 文件包静默混合经审计年度数与未经审计中期数 |
OCR is an intermediary, not authority. Preserve the original page beside OCR text and mark low-confidence cells, merged headers, parentheses, and ruled-table boundaries. InfiniSynapse’s public knowledge-base documentation says scanned PDFs are not supported in that context, so do not claim Stock Explained can reliably read an image-only filing. Prefer a text-based filing; if lawful OCR is used elsewhere, verify every material cell visually. Remove account numbers, personal data, credentials, and unnecessary sensitive material before upload.
OCR 是中间层,不是权威来源。任何 OCR 文本都要与原页面并存,并标记低置信单元格、手写标记、上标、合并表头、括号与表格线。InfiniSynapse 的公开知识库文档明确说明该场景不支持扫描 PDF,因此不能宣称 Stock Explained 能可靠读取纯图像申报。条件允许时获取带文字层的正式文件;若在其他合法工具中执行 OCR,重大单元格必须逐个目视核对后才能分析。上传前还要删除账户号码、个人资料、凭证等不必要敏感信息。
Meet the deliberately messy two-period package认识这组故意设置陷阱的两期文件
VoltRiver Components is an invented precision-sensor manufacturer. Its 20X4 and 20X5 statements, notes, and extraction errors are fictional teaching data in US dollars. Income-statement values below are normalized to millions; source balance-sheet and cash-flow pages display thousands.
虚构来源包VoltRiver Components 是虚构精密传感器制造商。20X4 与 20X5 报表、附注和抽取错误均为美元教学数据。下列利润表已规范为百万美元,而资产负债表与现金流量表原页显示单位为千美元。
| Normalized income statement ($m) | 20X4 recast | 20X5 | Change |
|---|---|---|---|
| Revenue | $240 | $276 | +15.0% |
| Cost of goods sold | ($156) | ($190) | +21.8% expense |
| Gross profit / margin | $84 / 35.0% | $86 / 31.2% | +$2; −3.8 percentage points |
| Selling, general, and administrative | ($40) | ($42) | +5.0% expense |
| Research and development | ($16) | ($19) | +18.8% expense |
| Operating income / margin | $28 / 11.7% | $25 / 9.1% | −$3; −2.6 percentage points |
| Interest / tax expense | ($4) / ($6) | ($5) / ($5) | Separate lines |
| Net income / margin | $18 / 7.5% | $15 / 5.4% | −$3; −2.1 percentage points |
| 规范化利润表(百万美元) | 20X4 重列 | 20X5 | 变化 |
|---|---|---|---|
| 收入 | 2.40 亿 | 2.76 亿 | +15.0% |
| 销售成本 | (1.56 亿) | (1.90 亿) | 费用 +21.8% |
| 毛利 / 毛利率 | 8,400 万 / 35.0% | 8,600 万 / 31.2% | 金额 +200 万;−3.8 个百分点 |
| 销售、一般及管理费用 | (4,000 万) | (4,200 万) | 费用 +5.0% |
| 研发费用 | (1,600 万) | (1,900 万) | 费用 +18.8% |
| 营业利润 / 营业利润率 | 2,800 万 / 11.7% | 2,500 万 / 9.1% | 金额 −300 万;−2.6 个百分点 |
| 利息 / 所得税费用 | (400 万)/(600 万) | (500 万)/(500 万) | 保持分行 |
| 净利润 / 净利率 | 1,800 万 / 7.5% | 1,500 万 / 5.4% | 金额 −300 万;−2.1 个百分点 |
Note 7 says VoltRiver moved $6m of 20X4 outbound shipping from SG&A to cost of goods sold and recast the prior column. Before recast, 20X4 showed COGS $150m, SG&A $46m, and gross profit $90m; operating income was still $28m. Comparing unrecast 37.5% gross margin with 20X5’s 31.2% would report a 6.3-point decline. The comparable recast decline is 3.8 points. This is a classification correction in the analytical table, not a claim that the company changed total profit.
附注 7 说明 VoltRiver 把 20X4 的 600 万对外运输费用从 SG&A 重分类到销售成本,并重列比较列。重列前 20X4 的 COGS 为 1.50 亿、SG&A 为 4,600 万、毛利为 9,000 万,营业利润仍为 2,800 万。若用未重列毛利率 37.5% 对比 20X5 的 31.2%,会得到下降 6.3 个百分点;真正可比的重列降幅是 3.8 个百分点。这是分析表的分类修正,不是声称公司改变了总利润。
Make every extracted cell carry a passport让每个抽取单元格携带护照
| Cell passport field | VoltRiver example | Control |
|---|---|---|
| Raw label and value | “Purchases of property and equipment (43,000)” | Keep parentheses and original typography |
| Normalized value | −$43m | Apply source unit × 0.001; retain outflow sign |
| Coordinates | 20X5 cash-flow statement, investing section, page 58, current-year column | Open locator and inspect row-column intersection |
| Period and state | Year ended December 31, 20X5; period flow | Do not treat as a year-end balance |
| Classification | Investing cash outflow; capital expenditure | Do not move into operating cash flow |
| Evidence status | Reported fact after visual check | Before check: AI-extracted, unverified |
| Transformation | Used in FCF = OCF − purchases of PP&E | Formula references only approved cell IDs |
| 单元格护照字段 | VoltRiver 示例 | 控制 |
|---|---|---|
| 原始标签与数值 | “购买物业设备(43,000)” | 保留括号与原始排版 |
| 规范化数值 | −4,300 万美元 | 来源单位乘 0.001;保留流出符号 |
| 坐标 | 20X5 现金流量表、投资活动、58 页、本期列 | 打开定位并检查行列交点 |
| 期间与状态 | 截至 20X5 年 12 月 31 日止年度;期间流量 | 不能当作年末余额 |
| 分类 | 投资现金流出;资本开支 | 不能移动到经营现金流 |
| 证据状态 | 目视核验后为报告事实 | 核验前:AI 抽取、未验证 |
| 转换 | 用于 FCF=OCF−购买 PP&E | 公式只能引用已批准单元格 ID |
A narrow PDF extraction places 20X4 COGS $156m under 20X5. The page image and year header correct it to current-year $190m.
列错位窄版 PDF 抽取把 20X4 的 COGS 1.56 亿放到 20X5 列。页面图像与年份表头确认本期应为 1.90 亿。
Turning “(43,000)” into positive 43,000 reverses investing cash direction and corrupts free cash flow.
括号丢失把“(43,000)”变成正数 43,000,会颠倒投资现金方向并破坏自由现金流。
The $310,000 total-assets source is in thousands: normalized total assets are $310m, not $310bn or $310,000m.
单位跳变总资产来源显示 310,000,但单位是千美元;规范后为 3.10 亿,不是 3,100 亿或 310,000 百万。
Using the originally presented 20X4 gross-profit classification exaggerates the comparable margin decline.
重列被忽略沿用 20X4 原始毛利分类会夸大可比毛利率降幅。
Do not calculate until the three-statement controls pass三表控制通过前,不要开始计算
| 20X5 control ($m after normalization) | Formula | Result |
|---|---|---|
| Balance sheet | Assets $310 = liabilities $170 + equity $140 | Pass |
| Net income to OCF | $15 NI + $18 D&A − $12 AR increase − $14 inventory increase + $7 AP increase + $3 accrual increase | $17 OCF |
| Net cash movement | $17 OCF − $43 PP&E purchases + $2 asset-sale proceeds + $24 financing | $0 before exchange effect |
| Cash closure | $24 opening + $0 net movement − $4 exchange effect | $20 closing cash; pass |
| Debt roll-forward | $80 opening debt + $30 proceeds − $10 repayments | $100 closing debt; pass |
| Equity roll-forward | $120 opening + $15 NI + $4 share issuance + $1 OCI | $140 closing equity; pass |
| 20X5 控制(规范后百万美元) | 公式 | 结果 |
|---|---|---|
| 资产负债表 | 资产 3.10 亿=负债 1.70 亿+权益 1.40 亿 | 通过 |
| 净利润到 OCF | 净利润 1,500 万+折旧摊销 1,800 万−应收增加 1,200 万−库存增加 1,400 万+应付增加 700 万+应计增加 300 万 | OCF 1,700 万 |
| 现金净变动 | OCF 1,700 万−投资 4,100 万+融资 2,400 万 | 汇率影响前为 0 |
| 现金闭合 | 期初 2,400 万+净变动 0−汇率影响 400 万 | 期末现金 2,000 万;通过 |
| 债务滚动 | 期初债务 8,000 万+借款 3,000 万−偿还 1,000 万 | 期末债务 1.00 亿;通过 |
| 权益滚动 | 期初权益 1.20 亿+净利润 1,500 万+发行股份 400 万+OCI 100 万 | 期末权益 1.40 亿;通过 |
The $4m exchange effect is the designed missing line. A draft that reports a cash error without searching between financing cash flow and ending cash is incomplete. A balancing control does not prove every classification is right: equal and opposite errors can balance. Pair equations with notes, trends, recalculated subtotals, and source coordinates. Use tolerance only for disclosed rounding; record it instead of forcing a zero residual.
400 万汇率影响是案例中故意设置的缺失行。若 AI 草稿看到现金不平,却没有在融资现金流与期末现金之间寻找汇率行,分析就不完整。勾稽平衡也不能证明每项分类都正确,因为等额反向错误仍可平衡。恒等式必须结合附注、可比趋势、小计重算与来源坐标。只有披露确有四舍五入时才能使用容差,并应明确记录,不能强行把残差改成零。
Income and cash-flow statements cover a period; balance sheets show a date. A turnover ratio often needs an average balance. Do not divide a single quarterly flow by an annual denominator or silently combine year-to-date and standalone-quarter data.
流量、余额与平均值必须分开利润表和现金流量表覆盖一个期间,资产负债表对应一个日期;周转率通常需要平均余额。不能用单季流量除以全年分母,也不能静默混合年初至今数与单季数。
Convert the AI draft into a correction table把 AI 草稿变成纠错表
| AI draft claim | Validation result | Corrected record |
|---|---|---|
| “Revenue grew 15%.” | ($276m ÷ $240m) − 1 = 15%; units and periods match | Approved calculation |
| “Gross margin improved to 43.5%.” | Column shift used $156m COGS: ($276m − $156m) ÷ $276m | Reject; correct margin = ($276m − $190m) ÷ $276m = 31.2%, down 3.8 points |
| “Total assets are $310bn.” | Source header says $ thousands | Correct to $310m; balance equation passes |
| “Free cash flow is $60m.” | Lost parentheses treated $43m capex as inflow: $17m + $43m | Correct investor convention: $17m OCF − $43m PP&E purchases = −$26m |
| “Current ratio is 2.03×.” | AI excluded $15m current debt from current liabilities | Current assets $142m ÷ current liabilities $85m = 1.67× |
| “Cash does not reconcile by $4m.” | AI omitted exchange-rate effect | Add reported −$4m exchange effect; ending cash closes at $20m |
| “Gross margin fell 6.3 points.” | AI compared unrecast 20X4 with current classification | Use recast 35.0% to 31.2%: decline 3.8 points |
| AI 草稿主张 | 验证结果 | 纠正后记录 |
|---|---|---|
| “收入增长 15%。” | 2.76 亿÷2.40 亿−1=15%;单位与期间一致 | 批准该计算 |
| “毛利率改善至 43.5%。” | 列错位使用 COGS 1.56 亿:(2.76 亿−1.56 亿)÷2.76 亿 | 拒绝;正确为(2.76 亿−1.90 亿)÷2.76 亿=31.2%,下降 3.8 个百分点 |
| “总资产为 3,100 亿美元。” | 来源表头为千美元 | 更正为 3.10 亿;资产负债恒等式通过 |
| “自由现金流为 6,000 万。” | 括号丢失使 4,300 万 capex 被当成流入:1,700 万+4,300 万 | 按常见投资者口径更正:OCF 1,700 万−PP&E 购买 4,300 万=−2,600 万 |
| “流动比率为 2.03 倍。” | AI 从流动负债中漏掉 1,500 万短债 | 流动资产 1.42 亿÷流动负债 8,500 万=1.67 倍 |
| “现金差 400 万无法勾稽。” | AI 漏掉汇率影响 | 加入报告的 −400 万汇率影响;期末现金闭合至 2,000 万 |
| “毛利率下降 6.3 个百分点。” | AI 用未重列 20X4 与本期分类比较 | 使用重列 35.0% 对 31.2%:下降 3.8 个百分点 |
20X5 revenue is $276m and purchases of PP&E are a $43m cash outflow after unit and sign verification.
报告事实完成单位与符号核验后,20X5 收入为 2.76 亿,购买 PP&E 是 4,300 万现金流出。
Revenue growth 15%, gross margin 31.2%, current ratio 1.67×, and FCF −$26m are reproducible formulas.
计算收入增长 15%、毛利率 31.2%、流动比率 1.67 倍和 FCF −2,600 万均为可复算公式。
Using OCF minus PP&E purchases as FCF is an analyst convention, not a required statement subtotal.
假设把 OCF 减购买 PP&E 定义为 FCF 是分析者口径,不是报表必列小计。
Lower margins and negative FCF suggest pressure, but causes require cost, pricing, inventory, capex, and reclassification notes.
判断与缺口利润率降低和负 FCF 表明压力,但原因仍需成本、定价、库存、capex 与重分类附注支持。
Release the analysis only after the acceptance gate通过验收门后再发布分析
- Freeze the uploaded source manifest and mark missing statements, notes, versions, or comparison periods.
- Approve extracted cells only after checking header, year, unit, sign, row, column, and page image.
- Approve normalization only after documenting currency conversion, recast mapping, continuing-operation scope, and current/noncurrent classification.
- Run statement equations and roll-forwards; route every residual to a source page rather than inventing a plug.
- Recalculate every material ratio outside the AI draft from approved cells and show formula, denominator, period, and rounding.
- Publish citations beside claims and retain the rejected draft, corrected value, reviewer, date, and reason.
- 冻结上传来源清单,标记缺少的报表、附注、版本或比较期。
- 只有检查表头、年份、单位、符号、行、列与页面图像后,才能批准抽取单元格。
- 只有记录币种转换、重列映射、持续经营范围与流动/非流动分类后,才能批准规范化。
- 运行报表恒等式与滚动;每个残差都回到来源页,不得虚构塞数项。
- 用批准单元格在 AI 草稿之外复算重大比率,并展示公式、分母、期间与舍入。
- 把引用放在主张旁,并保留被拒草稿、纠正值、复核人、日期与原因。
An anomaly queue is not a list of conclusions. Prioritize by materiality, control failure, and decision impact: a thousand-versus-million error outranks wording; a $4m unexplained cash gap outranks a rounding difference. Stop when the original is missing, illegible, or inconsistent. “Unable to verify” is valid. Human review should challenge arithmetic and accounting meaning; specialist review may be necessary for complex recognition, consolidation, fair value, tax, or legal issues.
异常队列不是结论列表。优先级应由重要性、控制失败和决策影响决定:千与百万的单位错误高于措辞偏好,无法解释的 400 万现金差高于一位小数舍入。若原件缺失、不可读或内部矛盾,应停止并写“无法核验”,这本身就是有效结果。人工既要复核算术,也要挑战会计含义;复杂确认、合并、公允价值、税务或法律问题可能需要专业人士。
Use Stock Explained as a source-bound drafting surface把 Stock Explained 用作受来源约束的草稿界面
InfiniSynapse publishes this page and operates Stock Explained, so treat the product description as first-party information. Publicly described behavior supports working from user-provided files and text to organize a plain-language stock brief; broader InfiniSynapse documentation supports file and data-source uploads and knowledge bases for definitions and prior context. This page does not claim that Stock Explained automatically retrieves every filing, performs guaranteed OCR, supplies live prices, replaces an accountant, or guarantees correct accounting. Provide complete, sanitized, text-searchable statements and notes, plus a short control memo naming entity, periods, currency, units, source hierarchy, reclassifications, and required equations.
Request an extraction table before interpretation: original label, raw and normalized values, unit, sign, period, statement, page, row/column, and evidence status. Then request common-size statements, period mappings, three-statement controls, formulas, anomalies, and missing evidence. Keep facts, calculations, assumptions, and judgments separate. Open each material locator and manually recalculate totals, margins, ratios, cash closure, debt, and equity roll-forwards. If the page image contradicts extracted text, the original wins; unresolved conflicts stay unverified.
InfiniSynapse 发布本页并运营 Stock Explained,因此产品描述属于第一方信息。公开说明支持依据用户提供的文件与文本整理通俗股票说明;更广泛的 InfiniSynapse 文档支持文件与数据源上传,以及用知识库补充定义和历史背景。本页不宣称 Stock Explained 会自动获取所有申报、提供有保证的 OCR、供应实时价格、替代会计师或保证会计结论正确。应提供完整、已脱敏、可搜索文字的报表和附注,以及一份简短控制备忘录,列明主体、期间、币种、单位、来源优先级、重分类和必须通过的恒等式。
解释前先要求抽取表:原始标签、原值、规范值、单位、符号、期间、报表、页码、行列与证据状态;再要求共同尺度表、可比期映射、三表控制、公式、异常队列与缺失证据列表。事实、计算、假设与判断必须分开。逐个打开上传原件中的重大定位,人工复算合计、利润率、比率、现金闭合、债务与权益滚动。若页面图像与抽取文本冲突,以原始页面为准;若来源无法解决冲突,结果保持未验证。
Upload complete searchable statements, notes, and a control memo; preserve citations and manually recalculate every decision-relevant output.
上传完整可搜索的报表、附注与控制备忘录,保留引用,并人工复算每项影响判断的输出。
Open Stock Explained打开“一眼看懂这只股票”Questions after the AI draft arrivesAI 草稿生成后的问题
Do not assume it can. InfiniSynapse’s public knowledge-base documentation says scanned PDFs are not supported there. Prefer a regulator-hosted text filing or searchable PDF. If OCR is lawfully created elsewhere, keep the page image and visually verify every material cell, sign, and column.
AI 能分析纯图像财务报表 PDF 吗?不能先验假设可以。InfiniSynapse 公开知识库文档说明该场景不支持扫描 PDF。优先使用监管机构文字申报或可搜索 PDF;若在其他合法工具中生成 OCR,要保留页面图像并目视核验每个重大单元格、符号与列。
Equal and opposite errors, a shifted pair of cells, or a misplaced subtotal can preserve the equation. The balance test is necessary but insufficient. Check row-column coordinates, note classifications, subtotals, roll-forwards, and cross-period movements.
为什么 AI 抽取错误时资产负债表仍可能平衡?等额反向错误、一对单元格同时错位或小计位置错误仍可能保持恒等式。平衡检验必要但不充分,还要核对行列坐标、附注分类、小计、滚动与跨期变动。
When the source convention uses parentheses for deductions or cash outflows, preserve that economic sign in the normalized layer. Also retain the raw display. Do not force every expense negative without reading the table convention, because some roll-forwards present additions as positive.
规范化后括号数都应保持负数吗?若来源约定括号代表扣减或现金流出,规范层要保留该经济符号,同时保存原始显示。但不能不读表格约定就把所有费用强制设负,因为某些滚动表会把增加额列为正数。
Every ratio that affects the conclusion. Recheck source cells, units, numerator, denominator, period, average versus ending balance, sign, and rounding. A mathematically correct formula can still be conceptually wrong when it mixes quarterly and annual periods or reported and adjusted values.
哪些 AI 比率必须人工复核?所有影响结论的比率都要复核。检查来源单元格、单位、分子、分母、期间、平均余额还是期末余额、符号与舍入。公式即使算术正确,混合单季与全年或报告值与调整值时仍会概念错误。
No. It organizes a brief from user-provided files and text. Material outputs require source verification, and complex accounting may need a qualified professional. The public description does not make it a complete filing collector, guaranteed-accuracy system, or real-time price service.
Stock Explained 能替代会计师或提供实时市场数据吗?不能。它依据用户提供的文件与文本组织说明;重大输出需要回到来源核验,复杂会计问题可能需要合格专业人士。公开描述不支持把它视为完整申报收集器、保证准确系统或实时价格服务。
Official references for sources, statements, and product scope来源、报表与产品范围的官方参考
InfiniSynapse publishes this page and operates Stock Explained. Product statements are therefore first-party descriptions, not independent evaluations. Features, supported inputs, and interfaces may change; check current official documentation before relying on a workflow.
This page is educational, not accounting, audit, legal, tax, market-data, or individualized investment advice. The VoltRiver package is fictional. AI output can omit context or contain errors; source documents and qualified human review control material conclusions.
InfiniSynapse 发布本页并运营 Stock Explained,因此产品陈述是第一方描述,不是独立评价。功能、支持输入与界面可能变化;依赖某项流程前应核对当前官方文档。
本页仅供学习,不构成会计、审计、法律、税务、市场数据或个性化投资建议。VoltRiver 文件包为虚构。AI 输出可能遗漏背景或出现错误;重大结论应由原始文件与合格人工复核控制。